


European index futures are posting modest gains but remain close to two-month lows and are heading for their weakest week since April 2026. Investors are concerned about the combination of high energy prices, higher interest rates and the risk of stagflation. The Stoxx Europe 600 is up around 0.5% today but is down more than 2% for the week. The DAX and FTSE 100 are both gaining around 0.5%, while the CAC 40 is up approximately 0.6%. Oil prices remain the main source of pressure. Brent crude rose to around $110 per barrel overnight on Friday, its highest level in four months, and despite pulling back toward $105, it is still up more than 10% this week amid the risk of further supply disruptions.
Key developments in Europe
-
Tanker traffic through the Persian Gulf remains heavily restricted following direct clashes between U.S. forces and the Iranian navy, while the seizure of Yemen’s Mocha port by Iran-backed Houthis increases the threat to Saudi oil export routes in the Red Sea.
-
The ECB raised its deposit rate by 25 bp on Thursday to 2.50%, the highest level since April 2025. The decision highlights the central bank’s growing concerns that rising commodity prices could spill over into core inflation.
-
Eurozone CPI inflation accelerated to 3.3% y/y in August, with energy prices rising 14.3%. Money markets are currently pricing in a probability of more than 90% for a third ECB rate hike before year-end. Despite this, EURUSD remains relatively flat today.
-
Higher bond yields and rising production costs have hit growth, industrial and consumer stocks particularly hard, increasing pressure on European equities in recent days alongside weakness in Wall Street indices.
-
Global investors are focused today on U.S. CPI data at 14:30. Following a strong NFP report showing employment growth of 162,000, a higher-than-expected inflation reading could further strengthen expectations for a Fed rate hike at its September 16 meeting.
-
In individual stocks, Vetoquinol is up 16% despite a 22% y/y increase in first-half net profit, flatexDEGIRO is down 5% following the resignation of its supervisory board chairman, while Alstom is gaining around 2.2% after securing contracts worth more than €1.2 billion.
UK data surprise analysts
UK GDP rose 0.4% m/m versus expectations of 0.0% and 0.3% previously. Sterling strengthened against the U.S. dollar as the improvement visible in today’s UK data was broad-based.
-
On a 3M/3M basis, GDP rose 0.4% versus a forecast of 0.3% and 0.4% previously.
-
GDP increased 1.6% y/y versus expectations of 1.0% and 1.1% previously.
-
UK industrial production rose 0.2% m/m in August versus an expected decline of 0.2% and a previous drop of 0.2%.
-
Industrial production increased 0.6% y/y versus a forecast of 0.2% and a previous decline of 0.2%.
-
Manufacturing production rose 0.9% m/m versus expectations of 0.2% and a previous decline of 0.5%.
-
Manufacturing production increased 2.6% y/y versus 0.5% previously.
-
The goods trade balance came in at -£20.96 billion versus expectations of -£22.4 billion and -£23.01 billion previously.
-
The non-EU goods trade balance came in at -£9.66 billion versus -£10.45 billion previously.
-
Construction output increased 0.1% m/m versus expectations of 0.1% and a previous decline of 0.1%.
-
Services output rose 0.4% m/m versus 0.0% previously.
UK data came in clearly stronger than expected, indicating that the economy entered the second half of the year with more momentum than the consensus had anticipated. GDP rose 0.4% m/m in August versus expectations of stagnation, while the 1.6% y/y growth rate significantly exceeded the 1.0% forecast, reducing concerns about a sharp slowdown in activity. Manufacturing stood out particularly positively, with output rising 0.9% m/m and 2.6% y/y, suggesting that the improvement in economic conditions is not limited solely to the services sector. Another positive signal is the narrowing of the trade deficit, although its level remains high and continues to represent a structural weakness of the UK economy. From a market perspective, the data set is supportive for sterling and may limit the Bank of England’s room for rapid monetary easing, particularly if resilient economic growth is accompanied by persistent inflationary pressure.
GBPUSD chart (H1 interval)

Source: xStation5
Alstom secures contracts worth more than €1.2 billion in the UK
European rail industry giant Alstom has signed contracts with TransPennine Express worth a combined more than €1.2 billion for the supply and long-term maintenance of a new fleet of battery-electric trains in northern England. The agreement includes the delivery of 29 five-car BEMU trainsets worth around €930 million and maintenance contracts valued at approximately €230 million.
The new trains, designed and manufactured in the UK, will mark the first deployment of the Adessia platform in the British market and are intended to support the Transpennine Route Upgrade and the decarbonisation of rail transport.
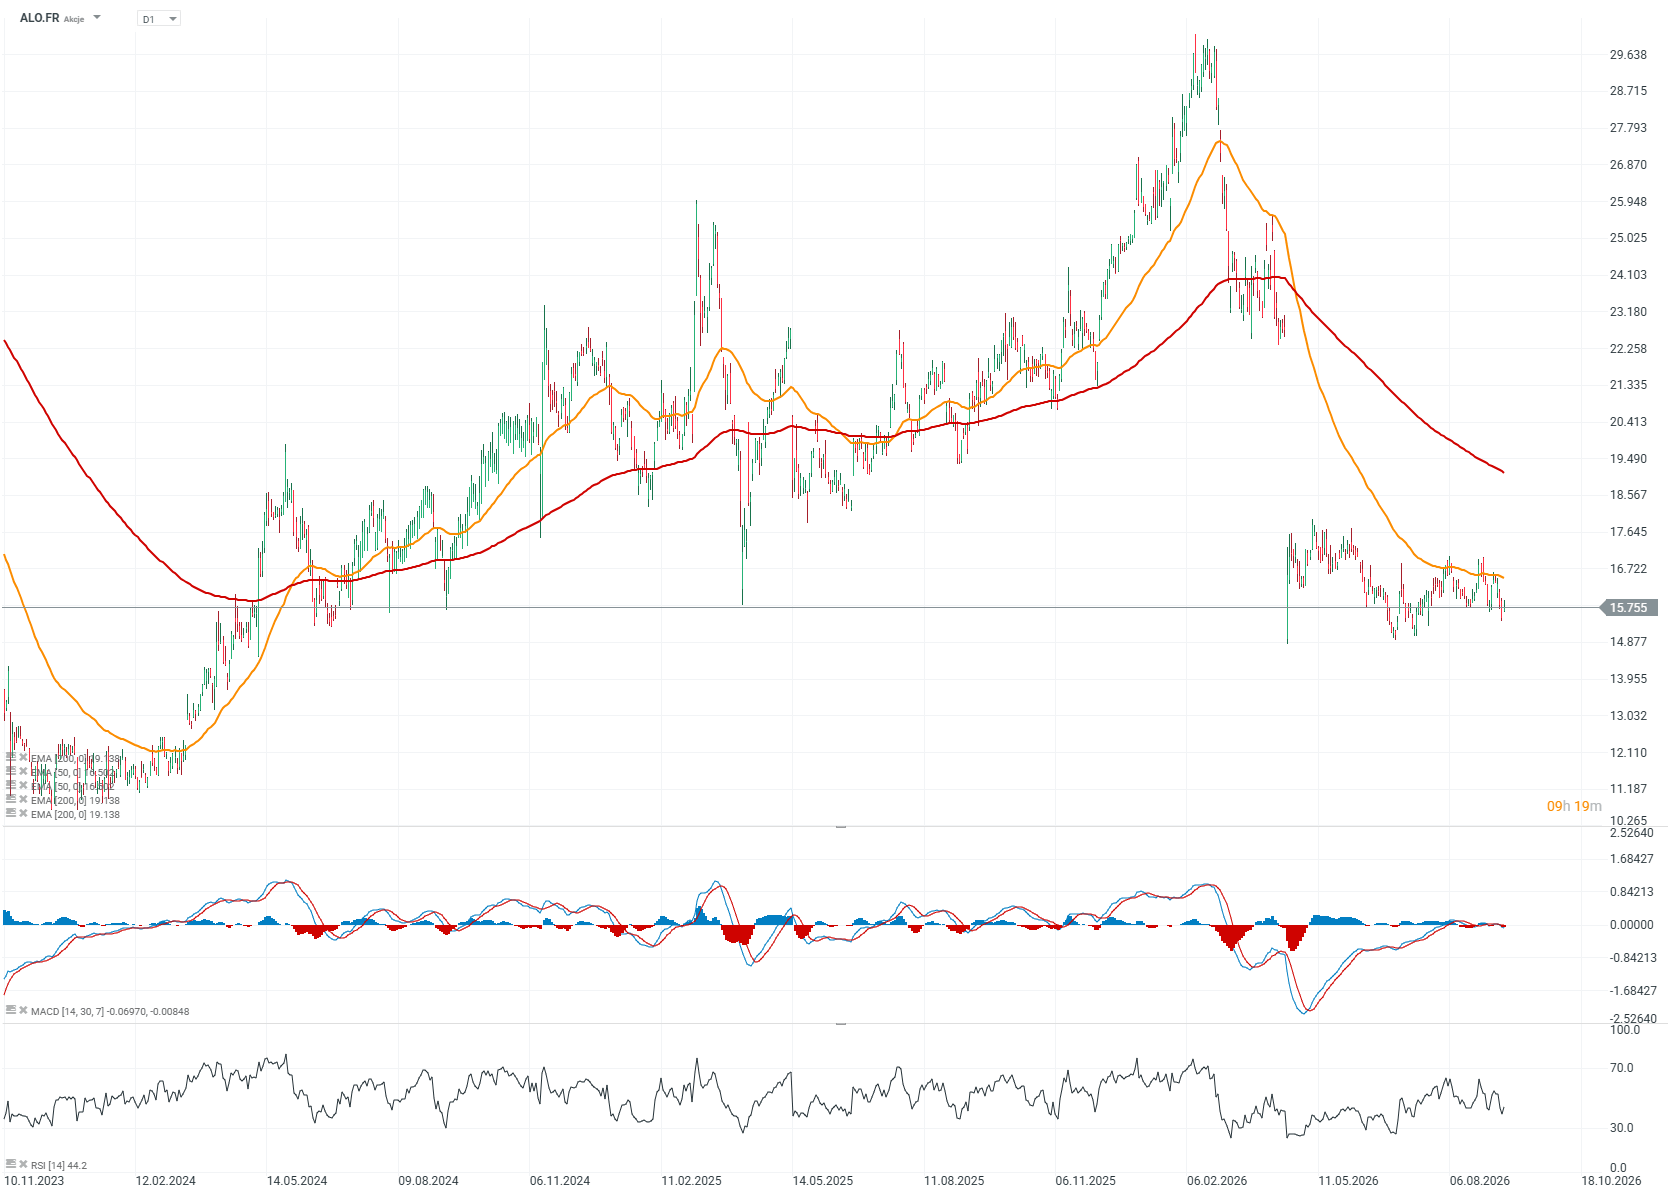
Deliveries are expected to begin in 2032, while the project also includes charging infrastructure and maintenance, demonstrating the broad scope of Alstom’s capabilities in delivering comprehensive rail projects. Alstom shares are still trading around 50% below their February 2026 highs.
Alstom chart (ALO.FR), D1 interval
The stock’s reaction to the contract appears very muted and has failed to reverse sentiment around the company’s shares. The stock is trading around 20% below its 200-day EMA and has remained in a deep downtrend since the spring of this year.
Source: xStation5


Daily Summary: Bitcoin Excites Investors Despite the Fed's Hawkish Shift🏛️


What could halt the uptrend❓

BREAKING: US industrial production & manufacturing data lower than expected


Market warp: Rate Forecasts and Semiconductors in the Spotlight
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.