


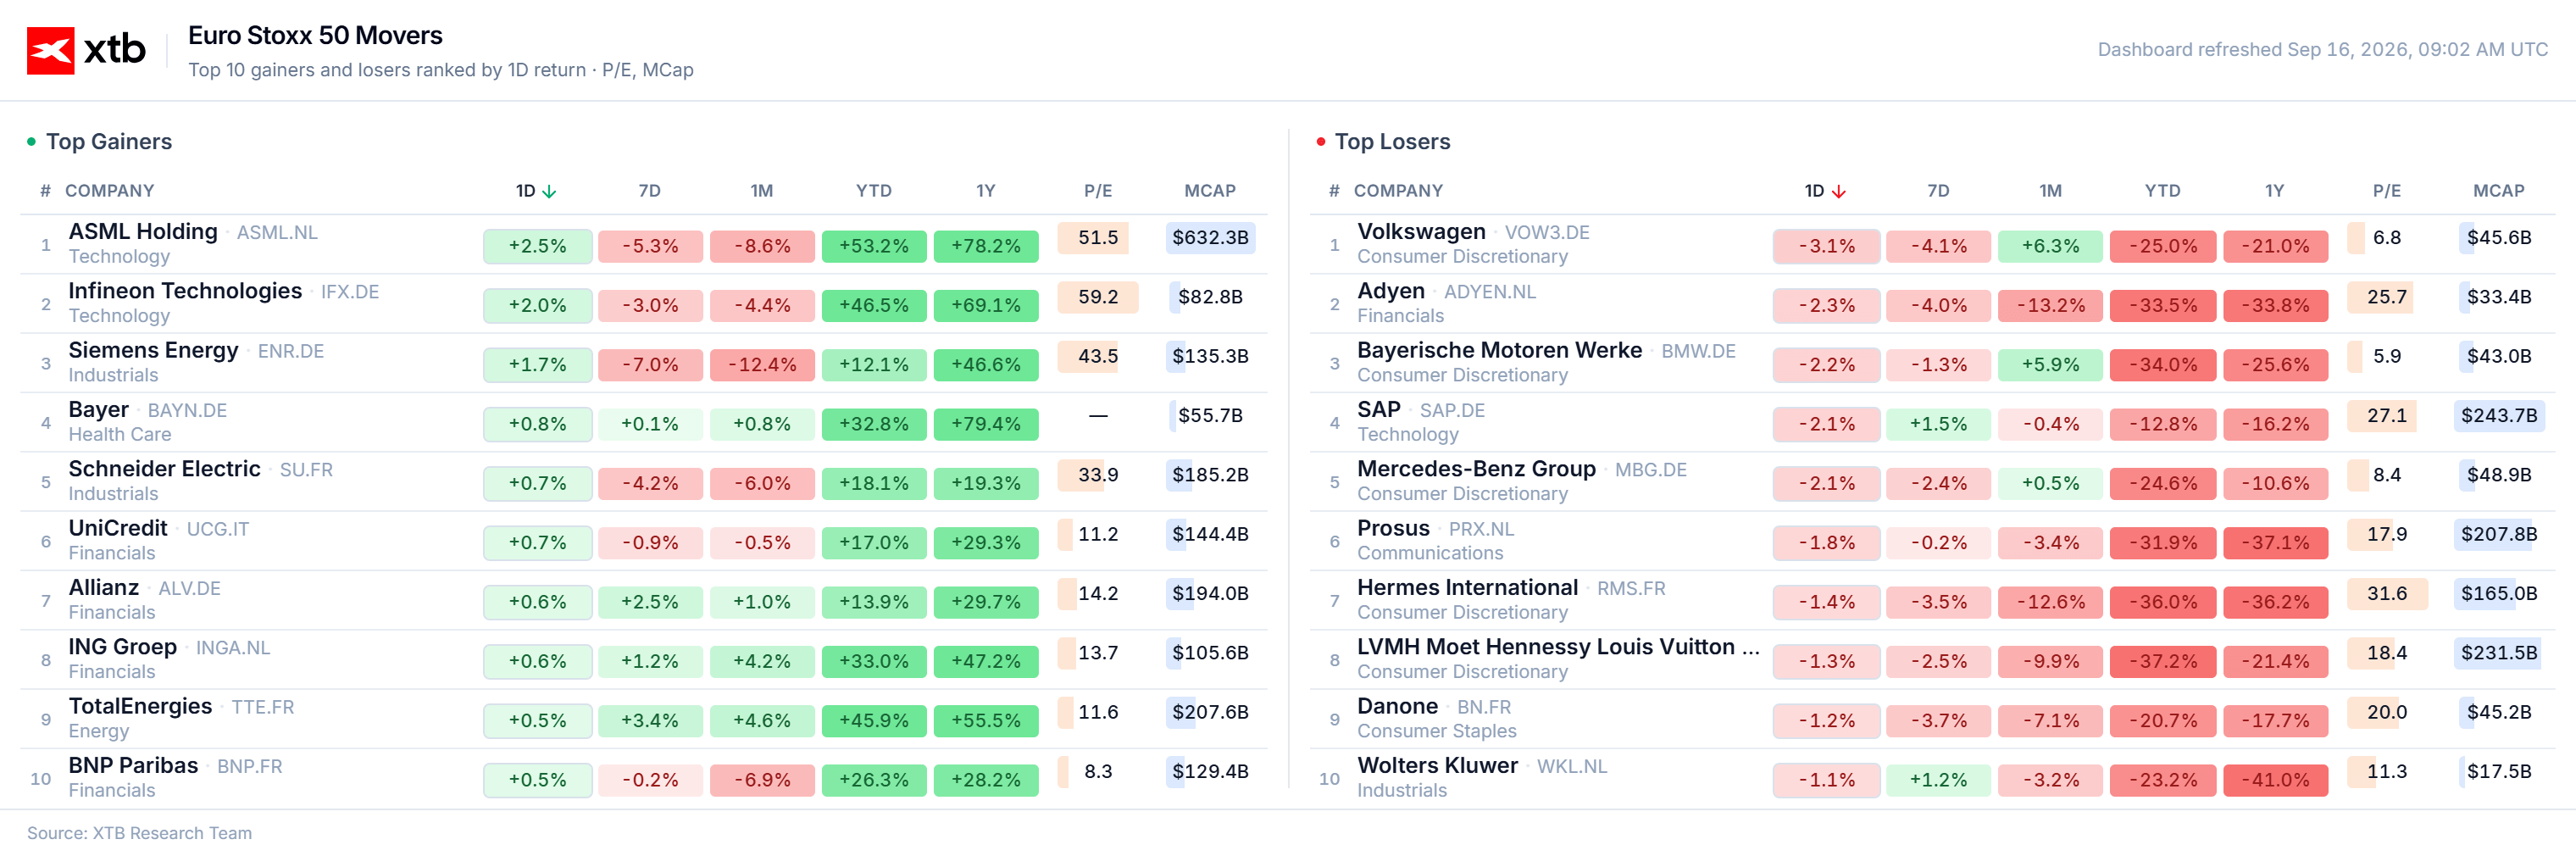
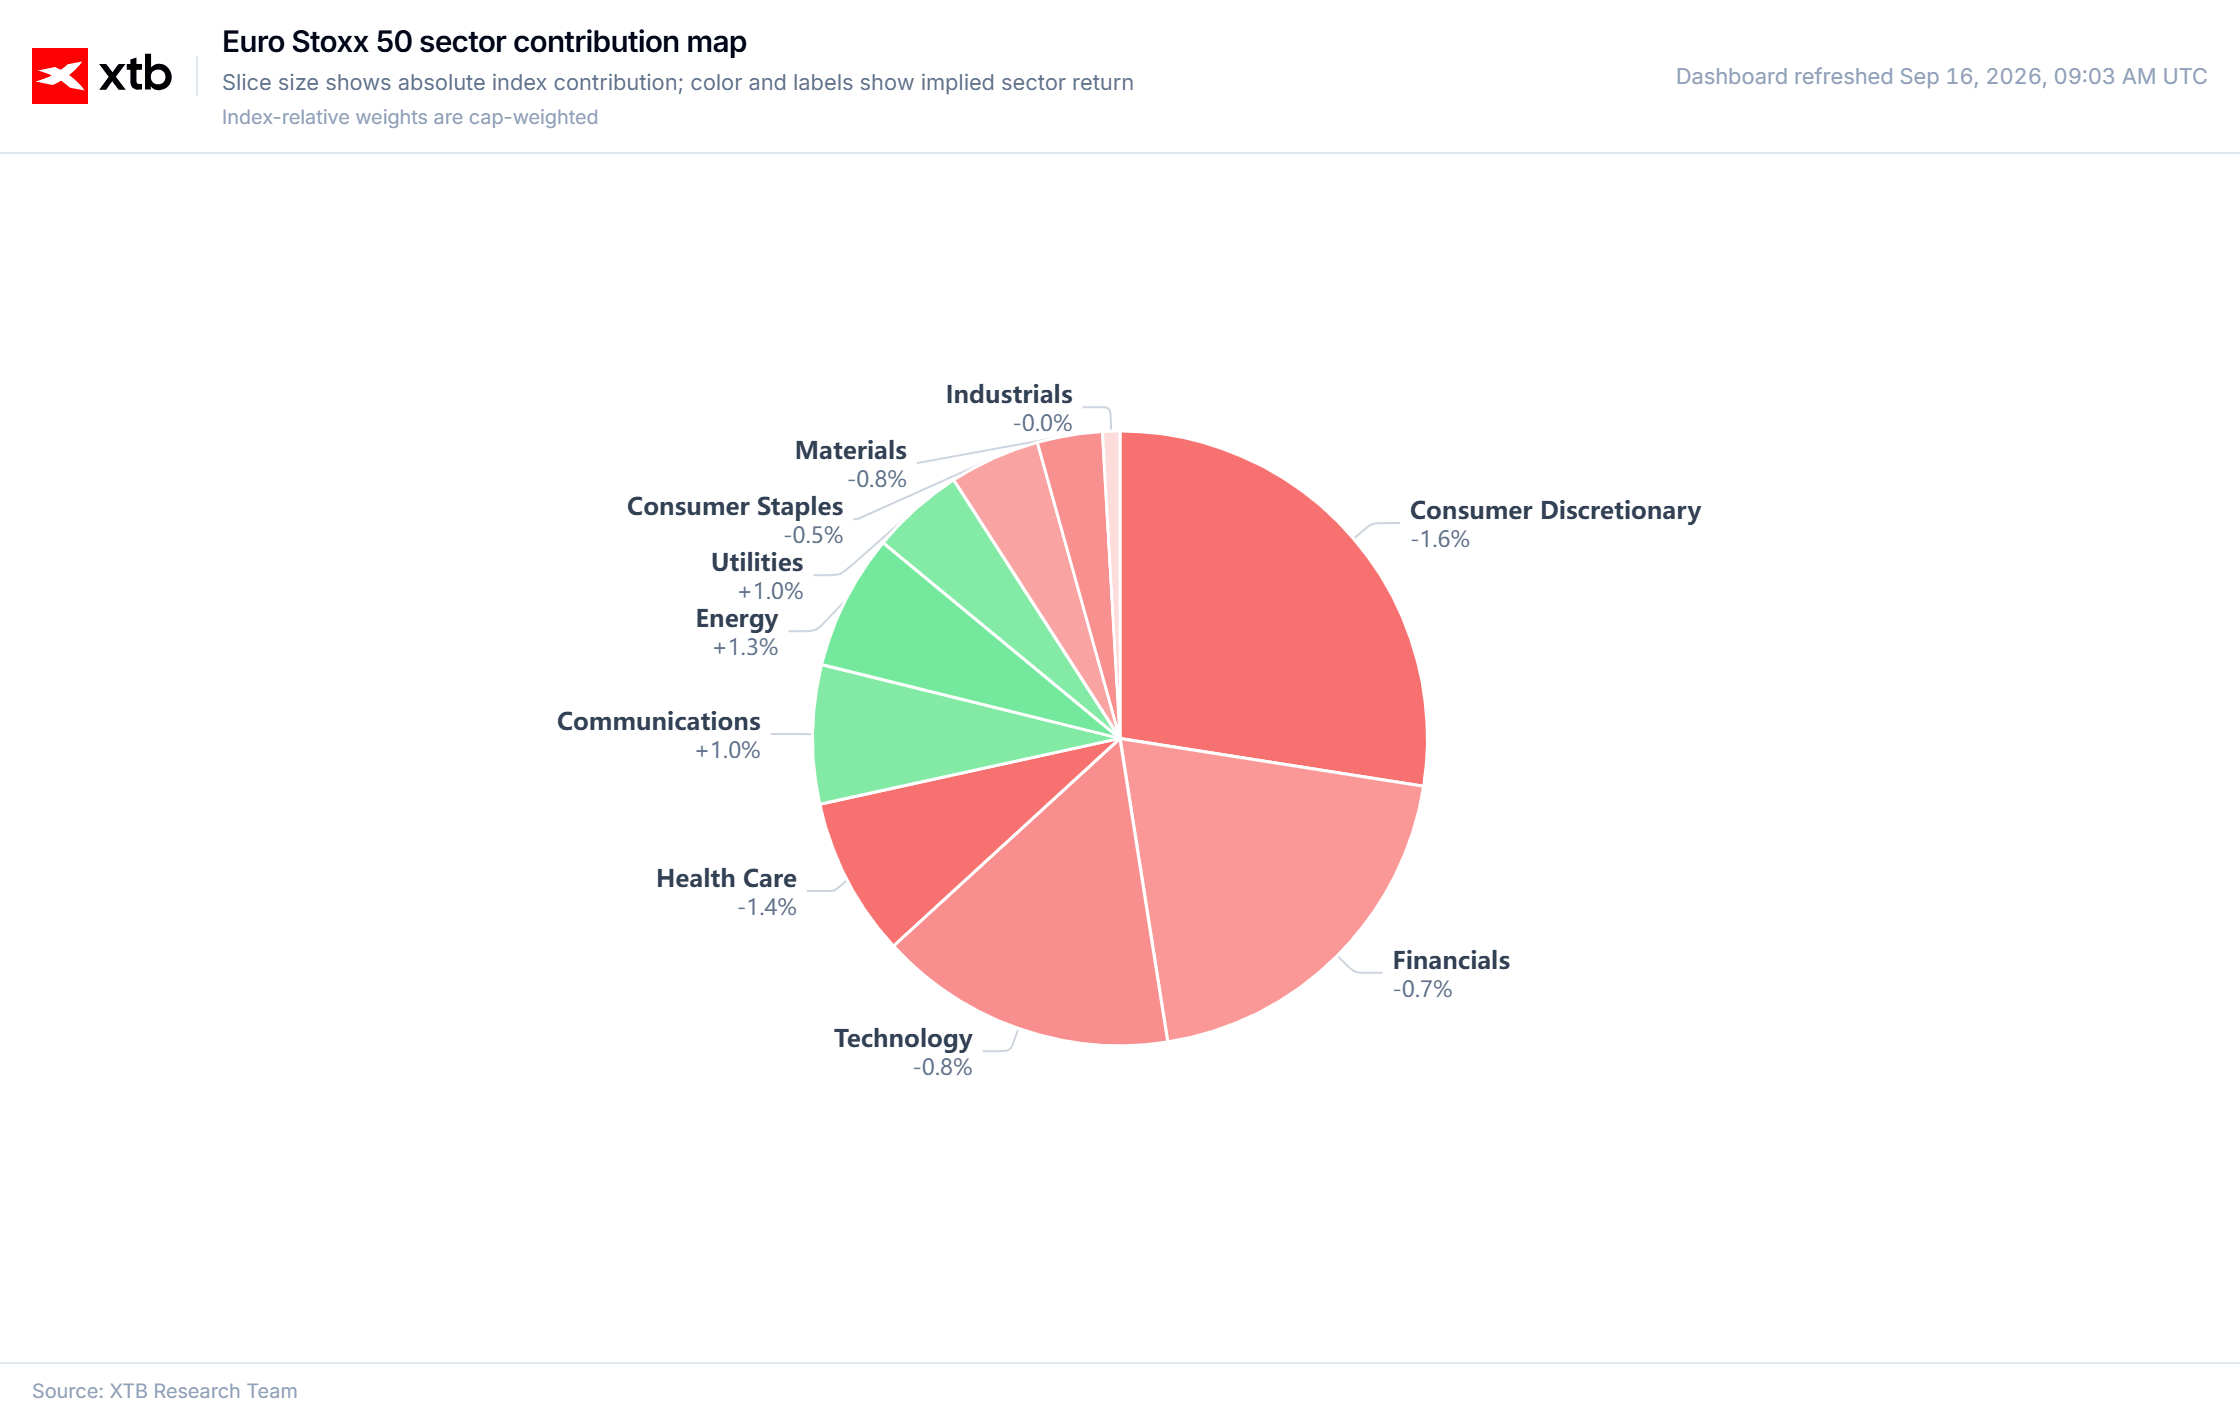
The first half of Wednesday’s session brought a slowdown in declines, but sentiment remains jittery and investor concerns are still elevated. European equities are mostly lower, with losses averaging around 0.2%. This trend is deepened by the WIG20, whose futures are down about 0.7%.
- One of the main downward pressures on indices remains the situation in the Middle East. As the WSJ reports, oil company executives are increasingly starting to openly describe the situation as an oil crisis. Forecasts for restoring the East-West pipeline to full functionality are becoming extreme, with speculation ranging from days to months. Oil prices remain above USD 108 per barrel, while the European gas contract has fallen below EUR 79.
- Bitcoin lost about 5% in yesterday’s session and dropped below USD 76,000. This follows a U.S. Senate vote on the “Clarity” bill that is at risk of failing. The bill is intended to significantly simplify and regulate cryptocurrency trading.
- A moderate improvement in sentiment in the memory market may come from SK Hynix, which has reached an agreement with labor unions on the payment of bonuses.
- Bloomberg reports that OpenAI is reportedly in the process of raising another funding round, this time said to amount to around USD 1.2 trillion.
- The market is reducing volatility and volume while awaiting the Fed’s interest rate decision. The decision will be published two hours before the end of trading in the U.S., and the Fed Chair’s press conference will begin at the close of the session. Comments from the press conference and potential Fed intentions, which Kevin Warsh is conspicuously trying not to reveal, may prove just as important, if not more important, than the decision itself.
Company News
- Soitec (SOI.FR): The stock is up around 6% after a valuation-supportive note from JPMorgan, which pointed to a strong outlook for the photonics industry.
- Stellantis (STLAM.IT): The automaker is down about 2% on the back of negative publications from an investment firm. At the same time, the firm pointed to a better outlook for BMW, which is up about 1%.
- Renault (RNO.FR): The automaker announced a new investment in Brazil in cooperation with China’s Geely Holding; the stock is down about 3%.
- ASML (ASML.NL): Positive news from SK Hynix is supporting semiconductor valuations. ASML is up about 2%, while Siemens and Infineon are up about 1%.
Macroeconomic Data
- Sweden’s unemployment rate rose to 8.5%.
- UK CPI came in in line with expectations and rose to 3.1% year over year. Core inflation held at 2.6% year over year.
- UK retail sales slowed its growth rate to 3.4% year over year.
- One hour before the U.S. session opens, U.S. retail sales data will be released. The market expects monthly growth to accelerate to 0.8%.
- One hour after the U.S. session opens, the EIA is set to publish data on weekly changes in crude oil and distillate inventories. The market expects crude inventories to fall by 1.7 million barrels and gasoline inventories to fall by 1.2 million barrels.


Daily Summary: Bitcoin Excites Investors Despite the Fed's Hawkish Shift🏛️


What could halt the uptrend❓

Russia is taking over Nestlé's domestic assets 🍫 Shares are down nearly 3% 💥

BREAKING: US industrial production & manufacturing data lower than expected
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.