


The US EV sector leader will release its Q3 results today after the close of US trading. Since the late-July lows, Elon Musk’s company has gained as much as 25%, and the recent vehicle delivery report significantly exceeded analysts’ estimates.
This creates a set of heightened expectations for a company that is increasingly struggling to stay above the profitability threshold.
Financial figures
Elon Musk enjoys substantial trust from shareholders and investors, something that can be seen even in the company’s valuation multiples. That trust is not unconditional. Understanding the “investment story” the CEO has been telling the market for decades is key to understanding how investors may react to the earnings release.
From a financial data perspective:
- The market expects revenue to rise to around USD 28.34bn, corresponding to about 1% year-over-year growth.
- In the Automotive segment, despite higher vehicle deliveries, a decline of just under USD 1bn is expected, from USD 21.2bn to USD 20.2bn.
- Services will have to make up for that shortfall, rising to USD 4.35bn, meaning roughly 20% year-over-year growth.
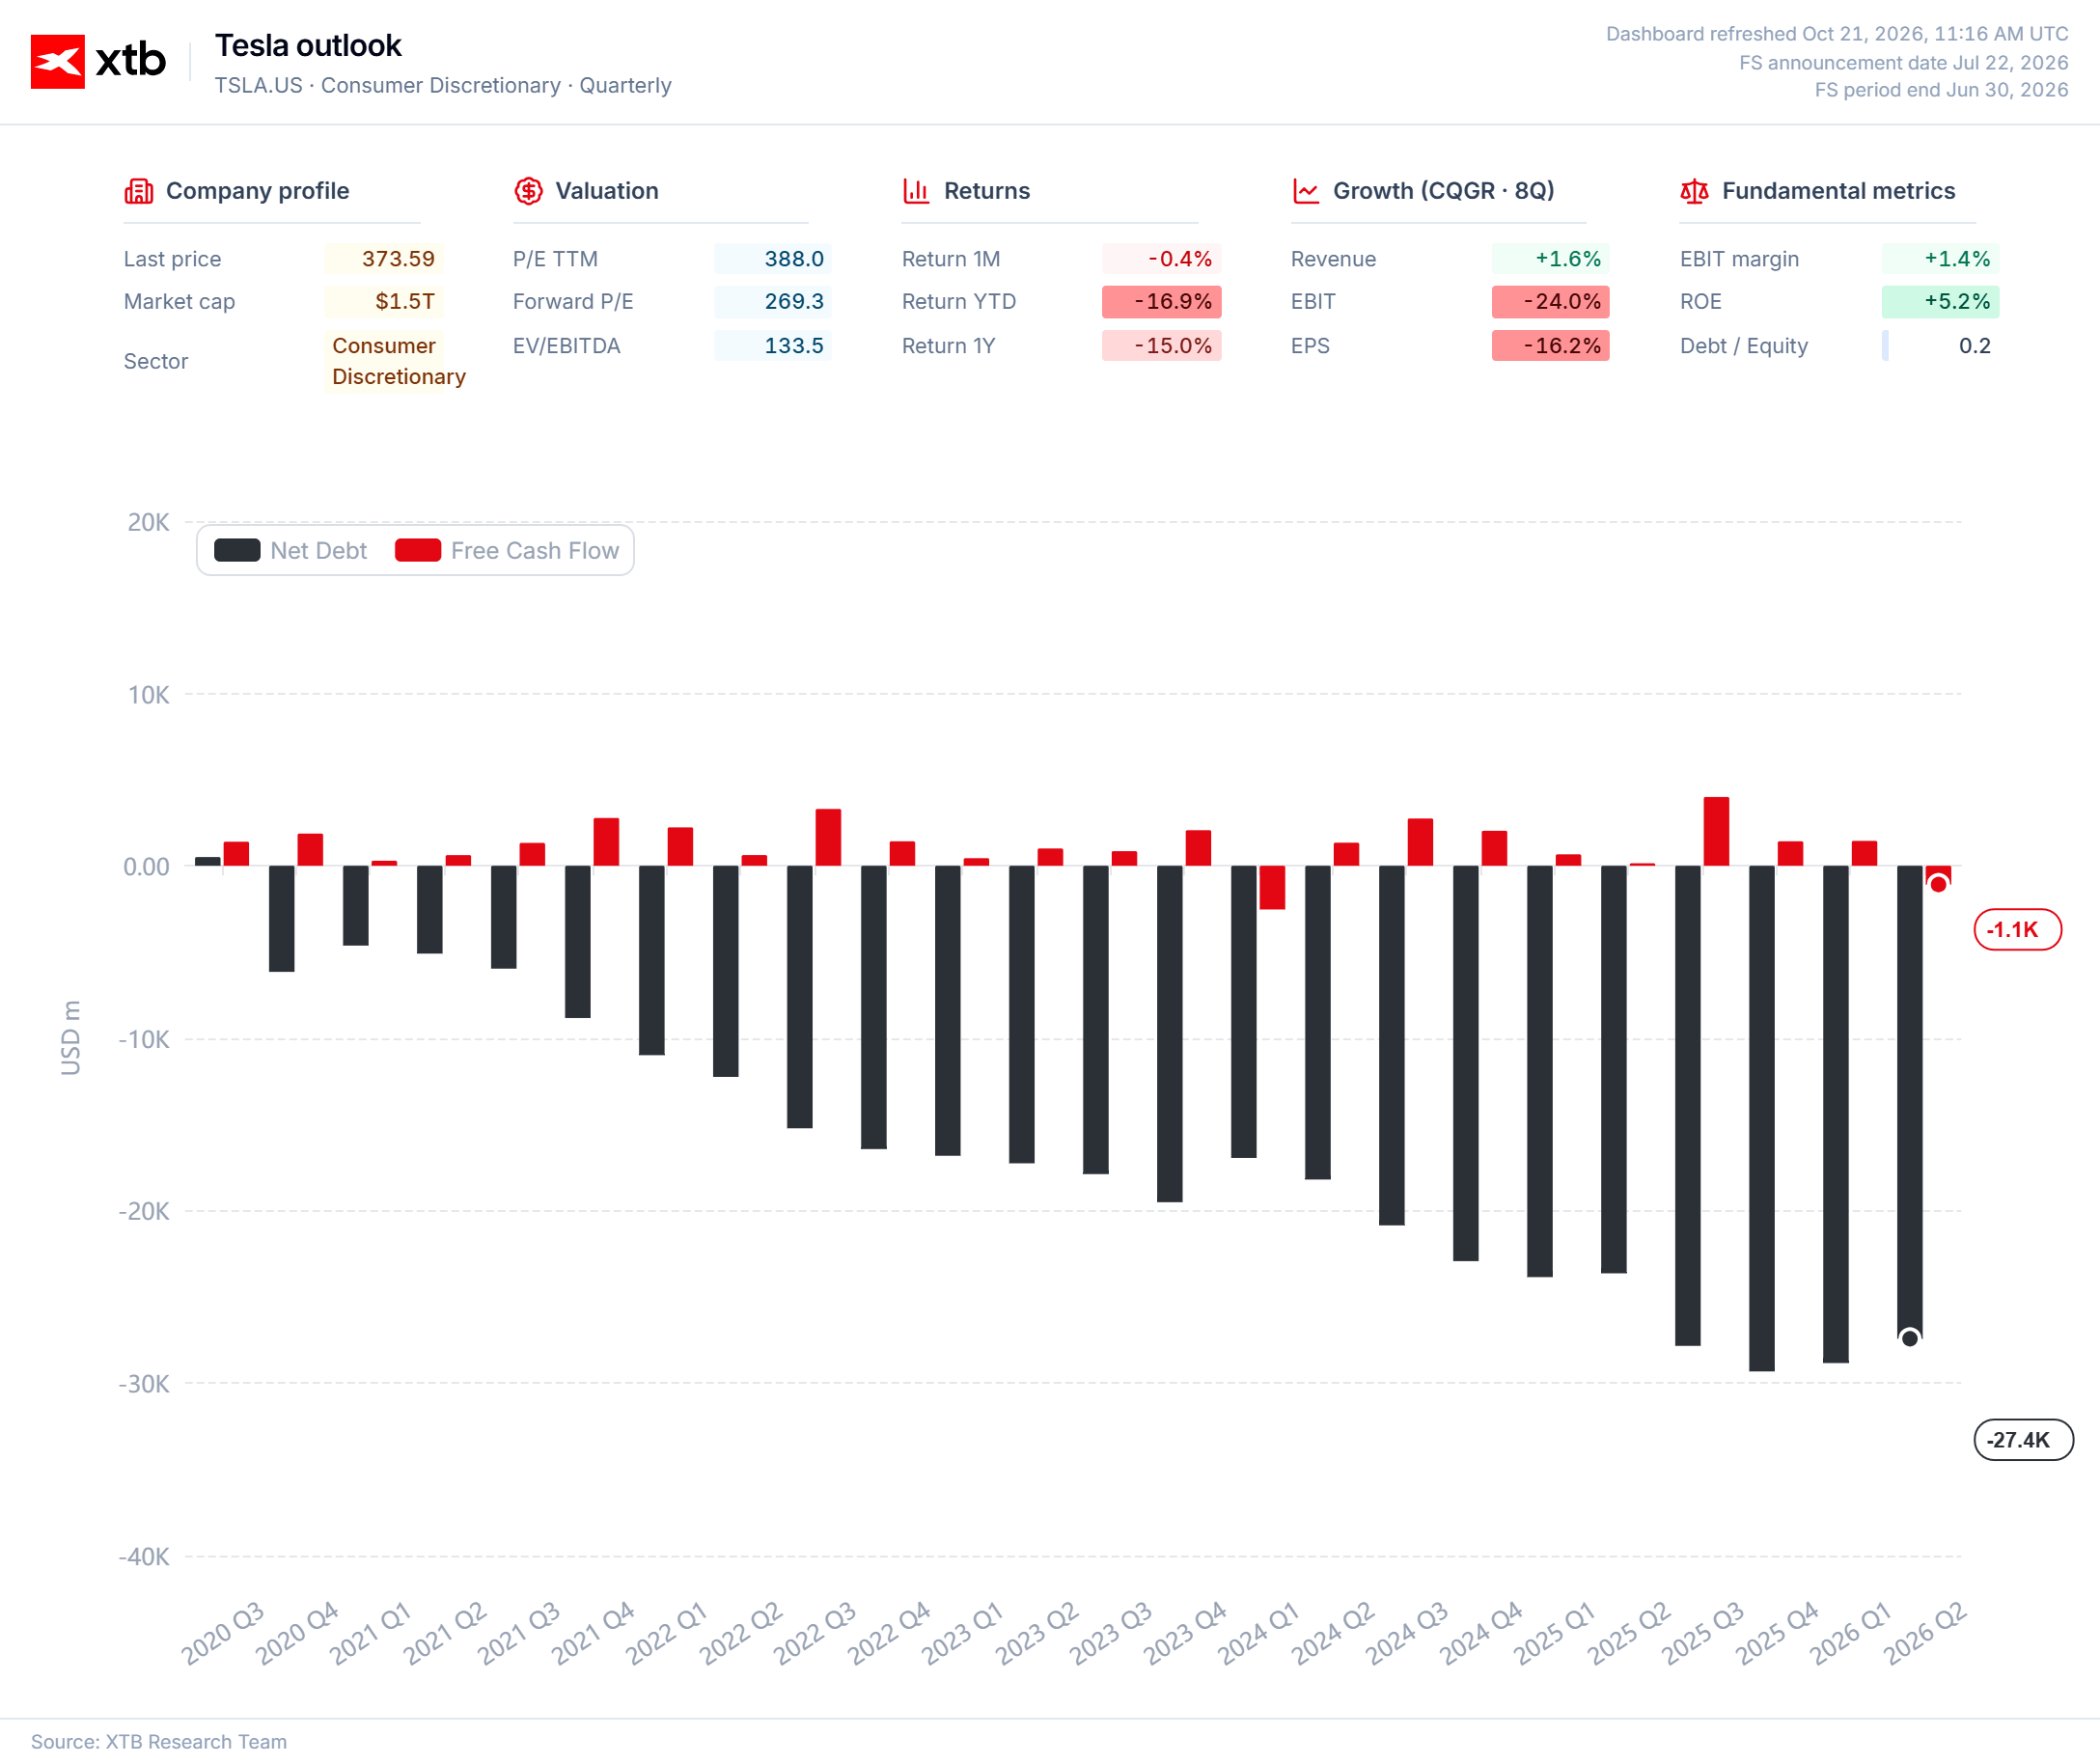
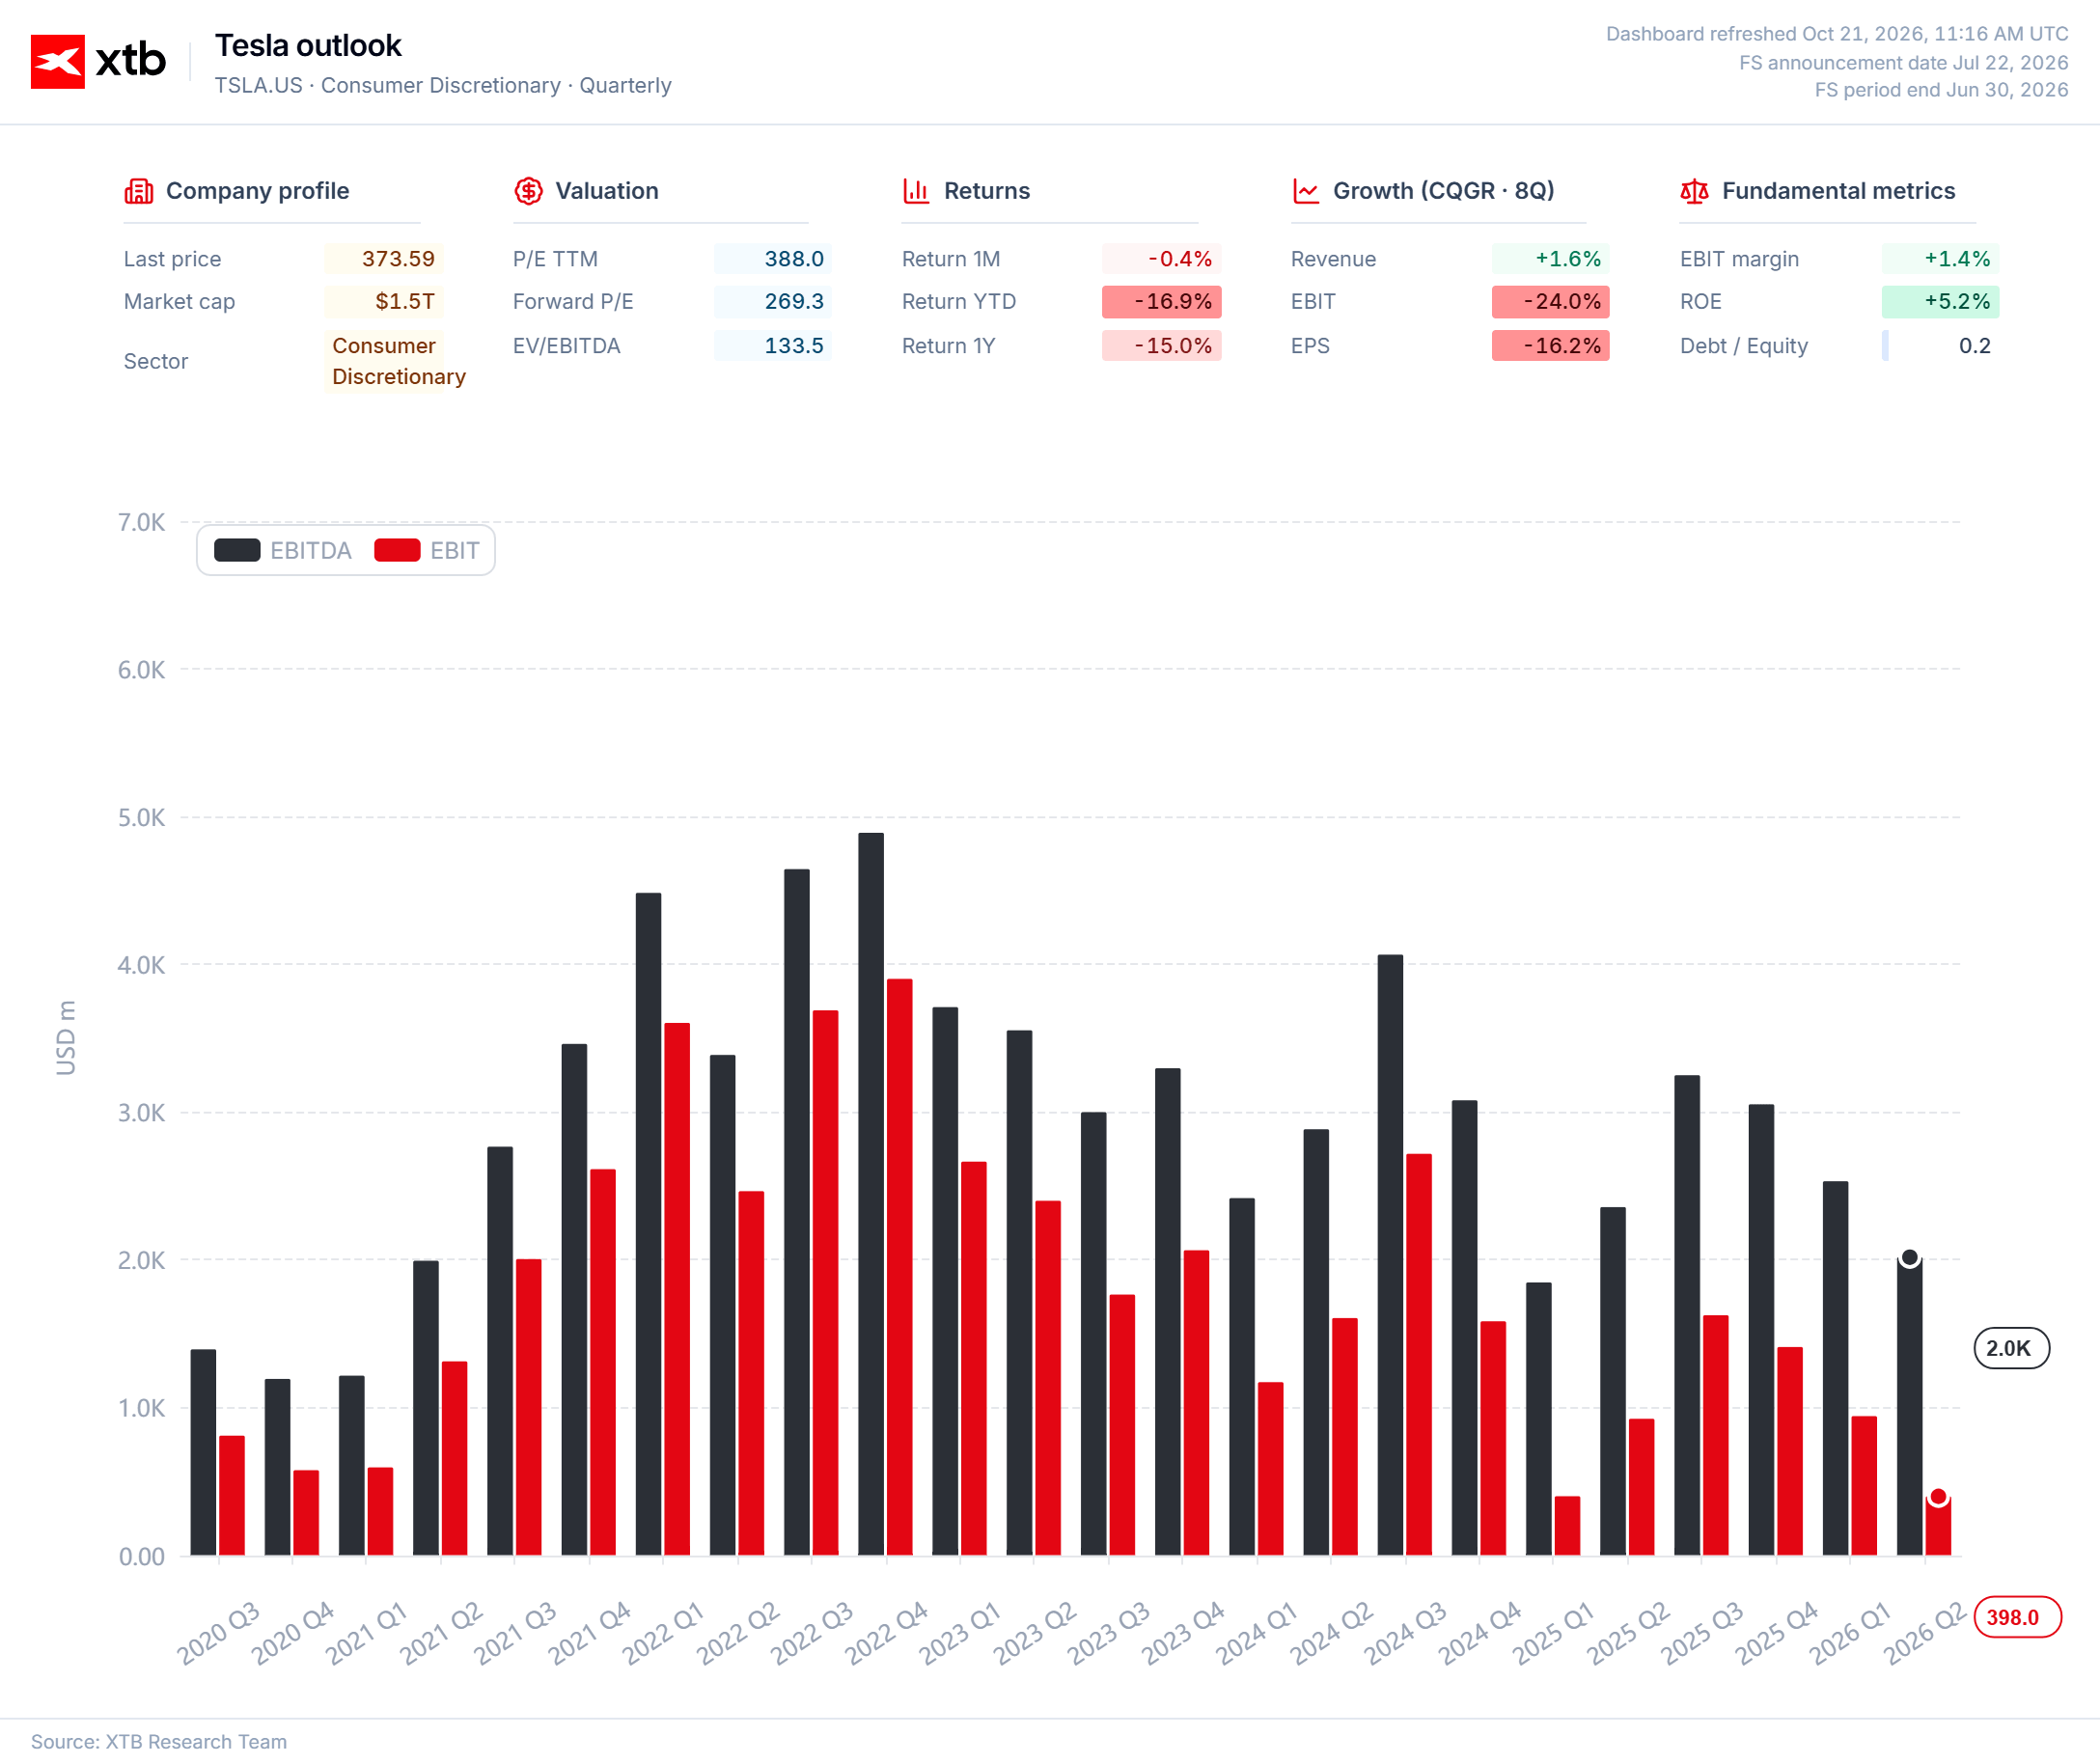
- Margin and operating profit look very weak. The market expects margin to fall by almost half to 2.5%, and operating profit of about USD 720m.
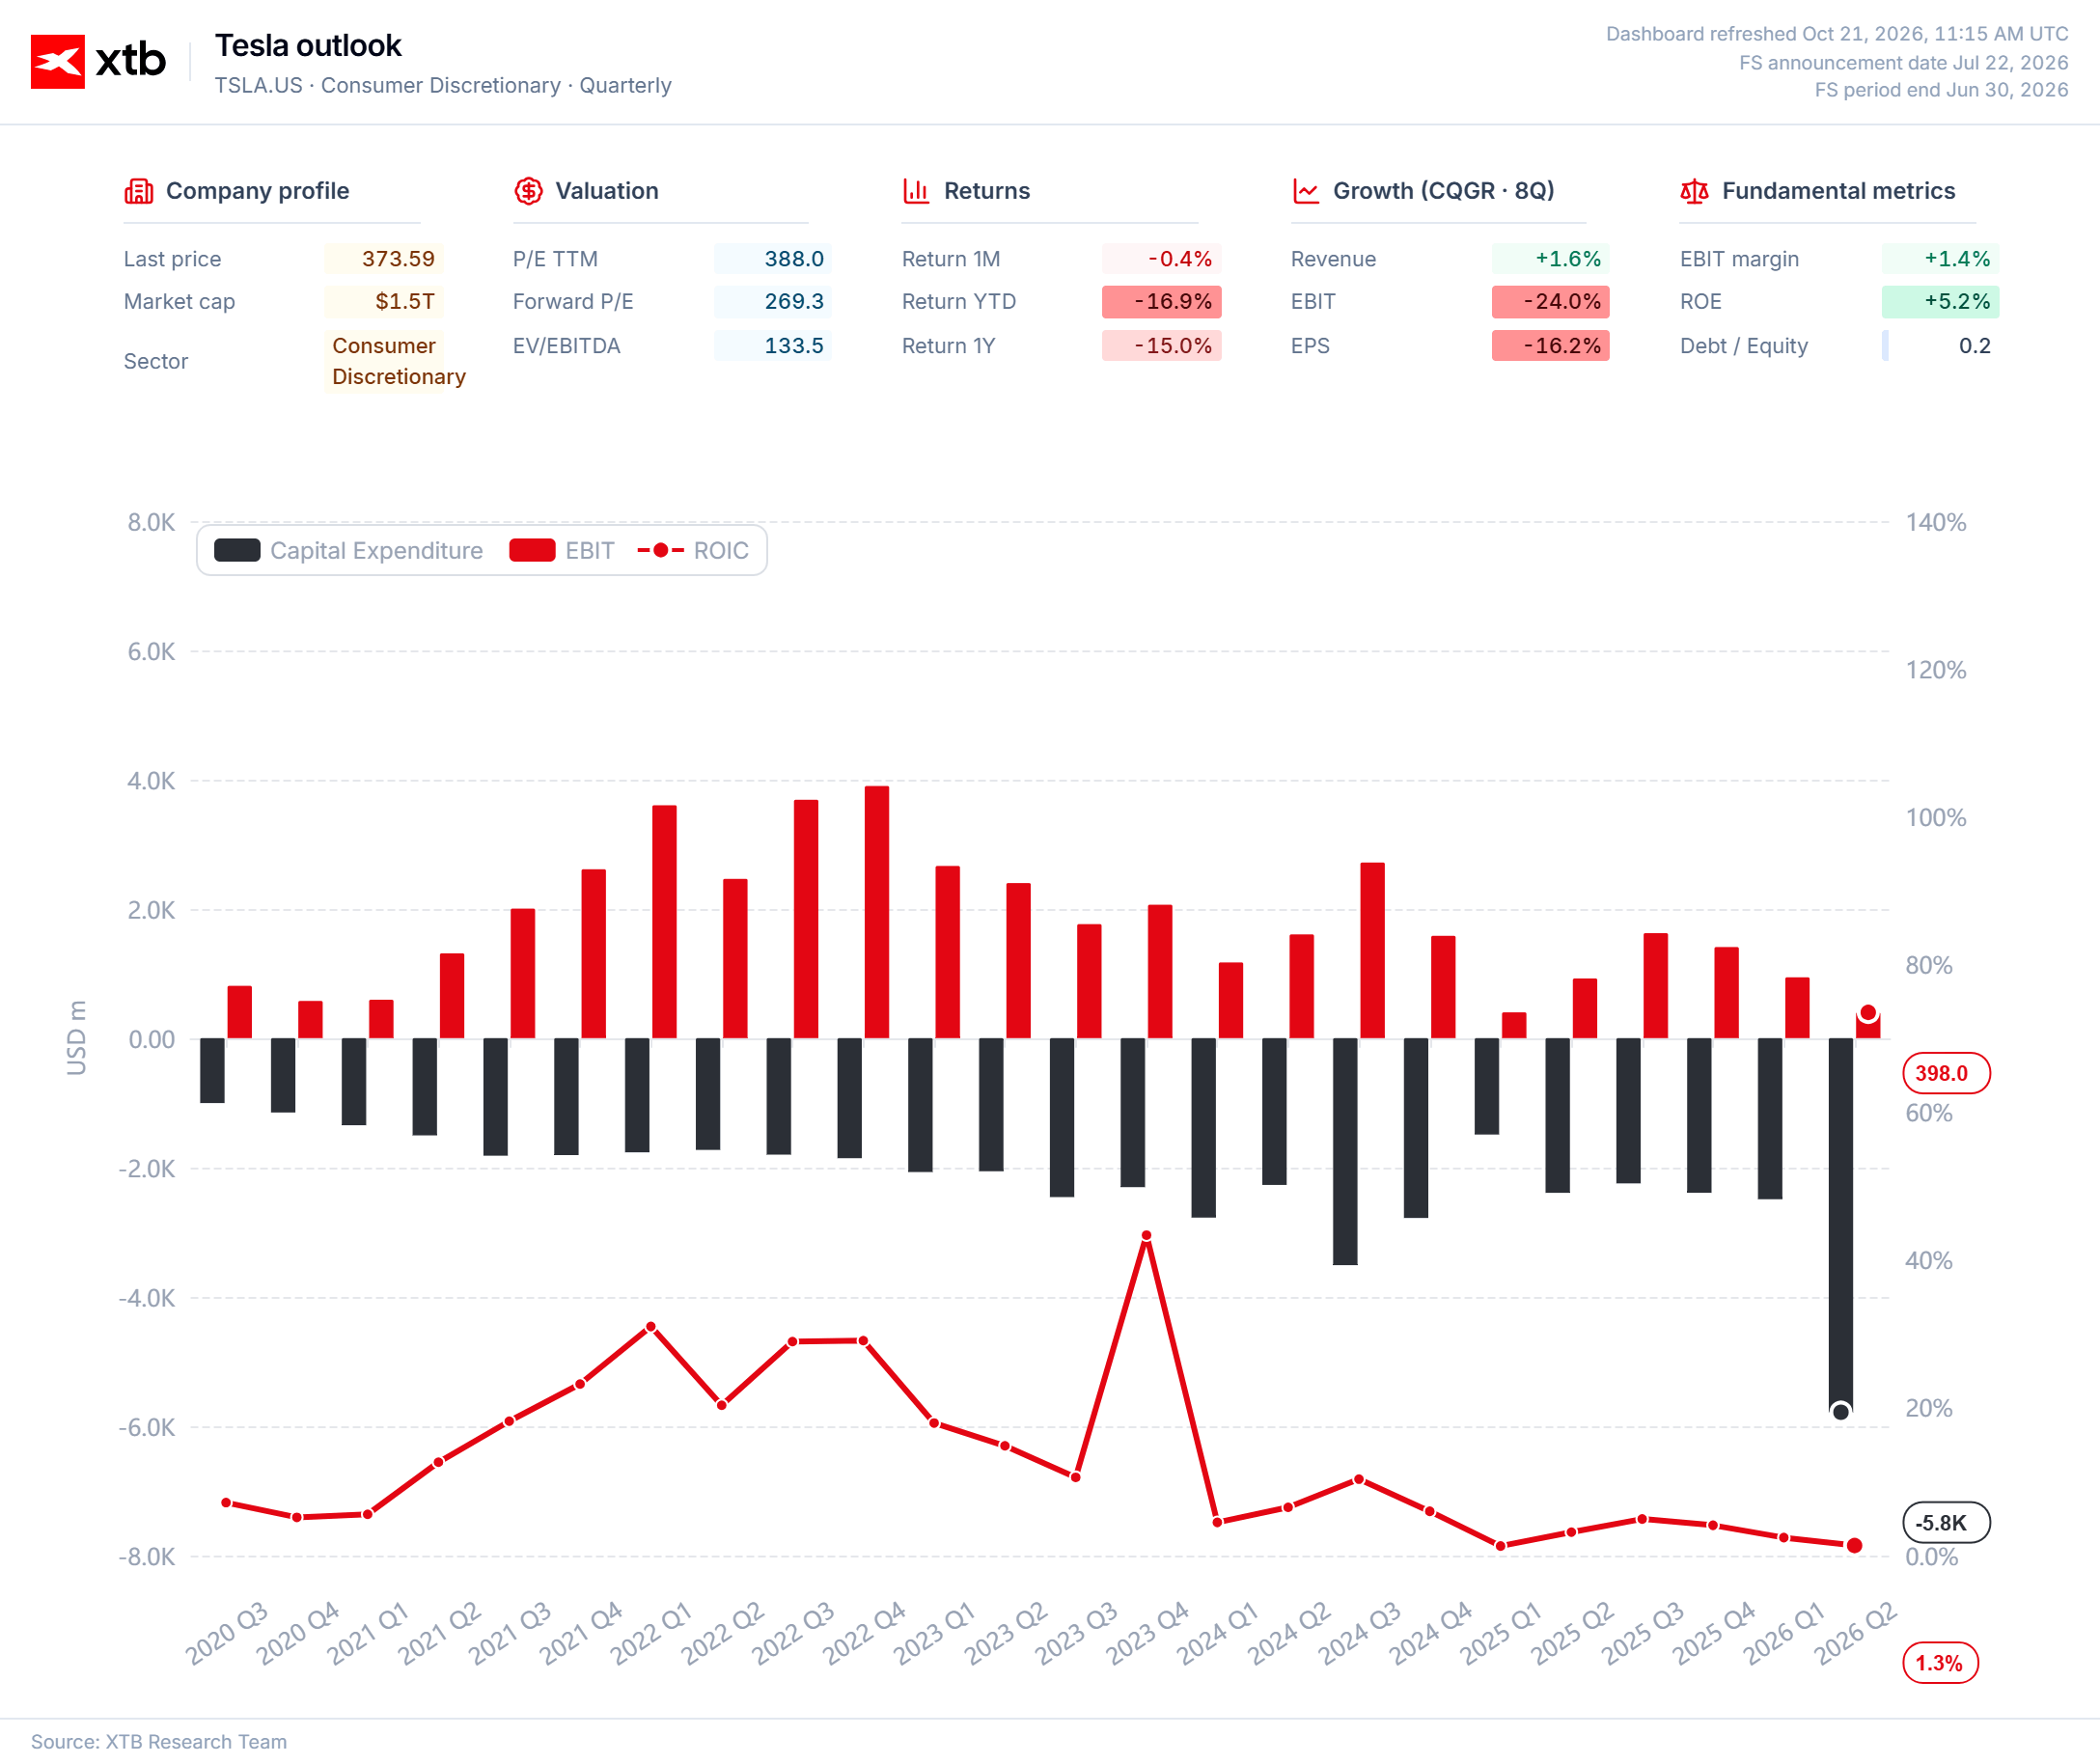
- Due to expected CAPEX increasing above USD 7.77bn, free cash flow is projected to drop to a negative USD 4.5bn.
Within this fairly pessimistic consensus, two investor groups stand out: those looking for qualitative signals or hard evidence of improved operational efficiency, and those who may once again be satisfied with promises.
Price action and shifting expectations suggest the market is not bracing for one weak quarter, but several, which the company is expected to offset over time. Operating profit and services margin will be key to that.
Operating profit needs to show the company is not losing market share and can, over the long term, implement the benefits of scale, effectively earning more from the same base.
A solid services margin will also be necessary. It is much easier to defend and expand and cannot, and in fact must, take over part of the profitability burden from the Automotive business.
CAPEX could also prove moderately important if it comes in different from expectations. Both lower and higher CAPEX can be interpreted as a sign of strength or weakness. Ultimately, capital spending should remain balanced around the consensus.
Earnings quality
A key question is whether Tesla’s recent suprise in vehicle deliveries was organic. Bloomberg analyses indicate a major risk to earnings quality is that a large recent batch of vehicle sales in Shanghai may have been supported by a significant price cut.
Given competition from both Europe and China, which has been consistently pushing the company’s margins lower, this could be very bad news in the context of an already weak earnings season.
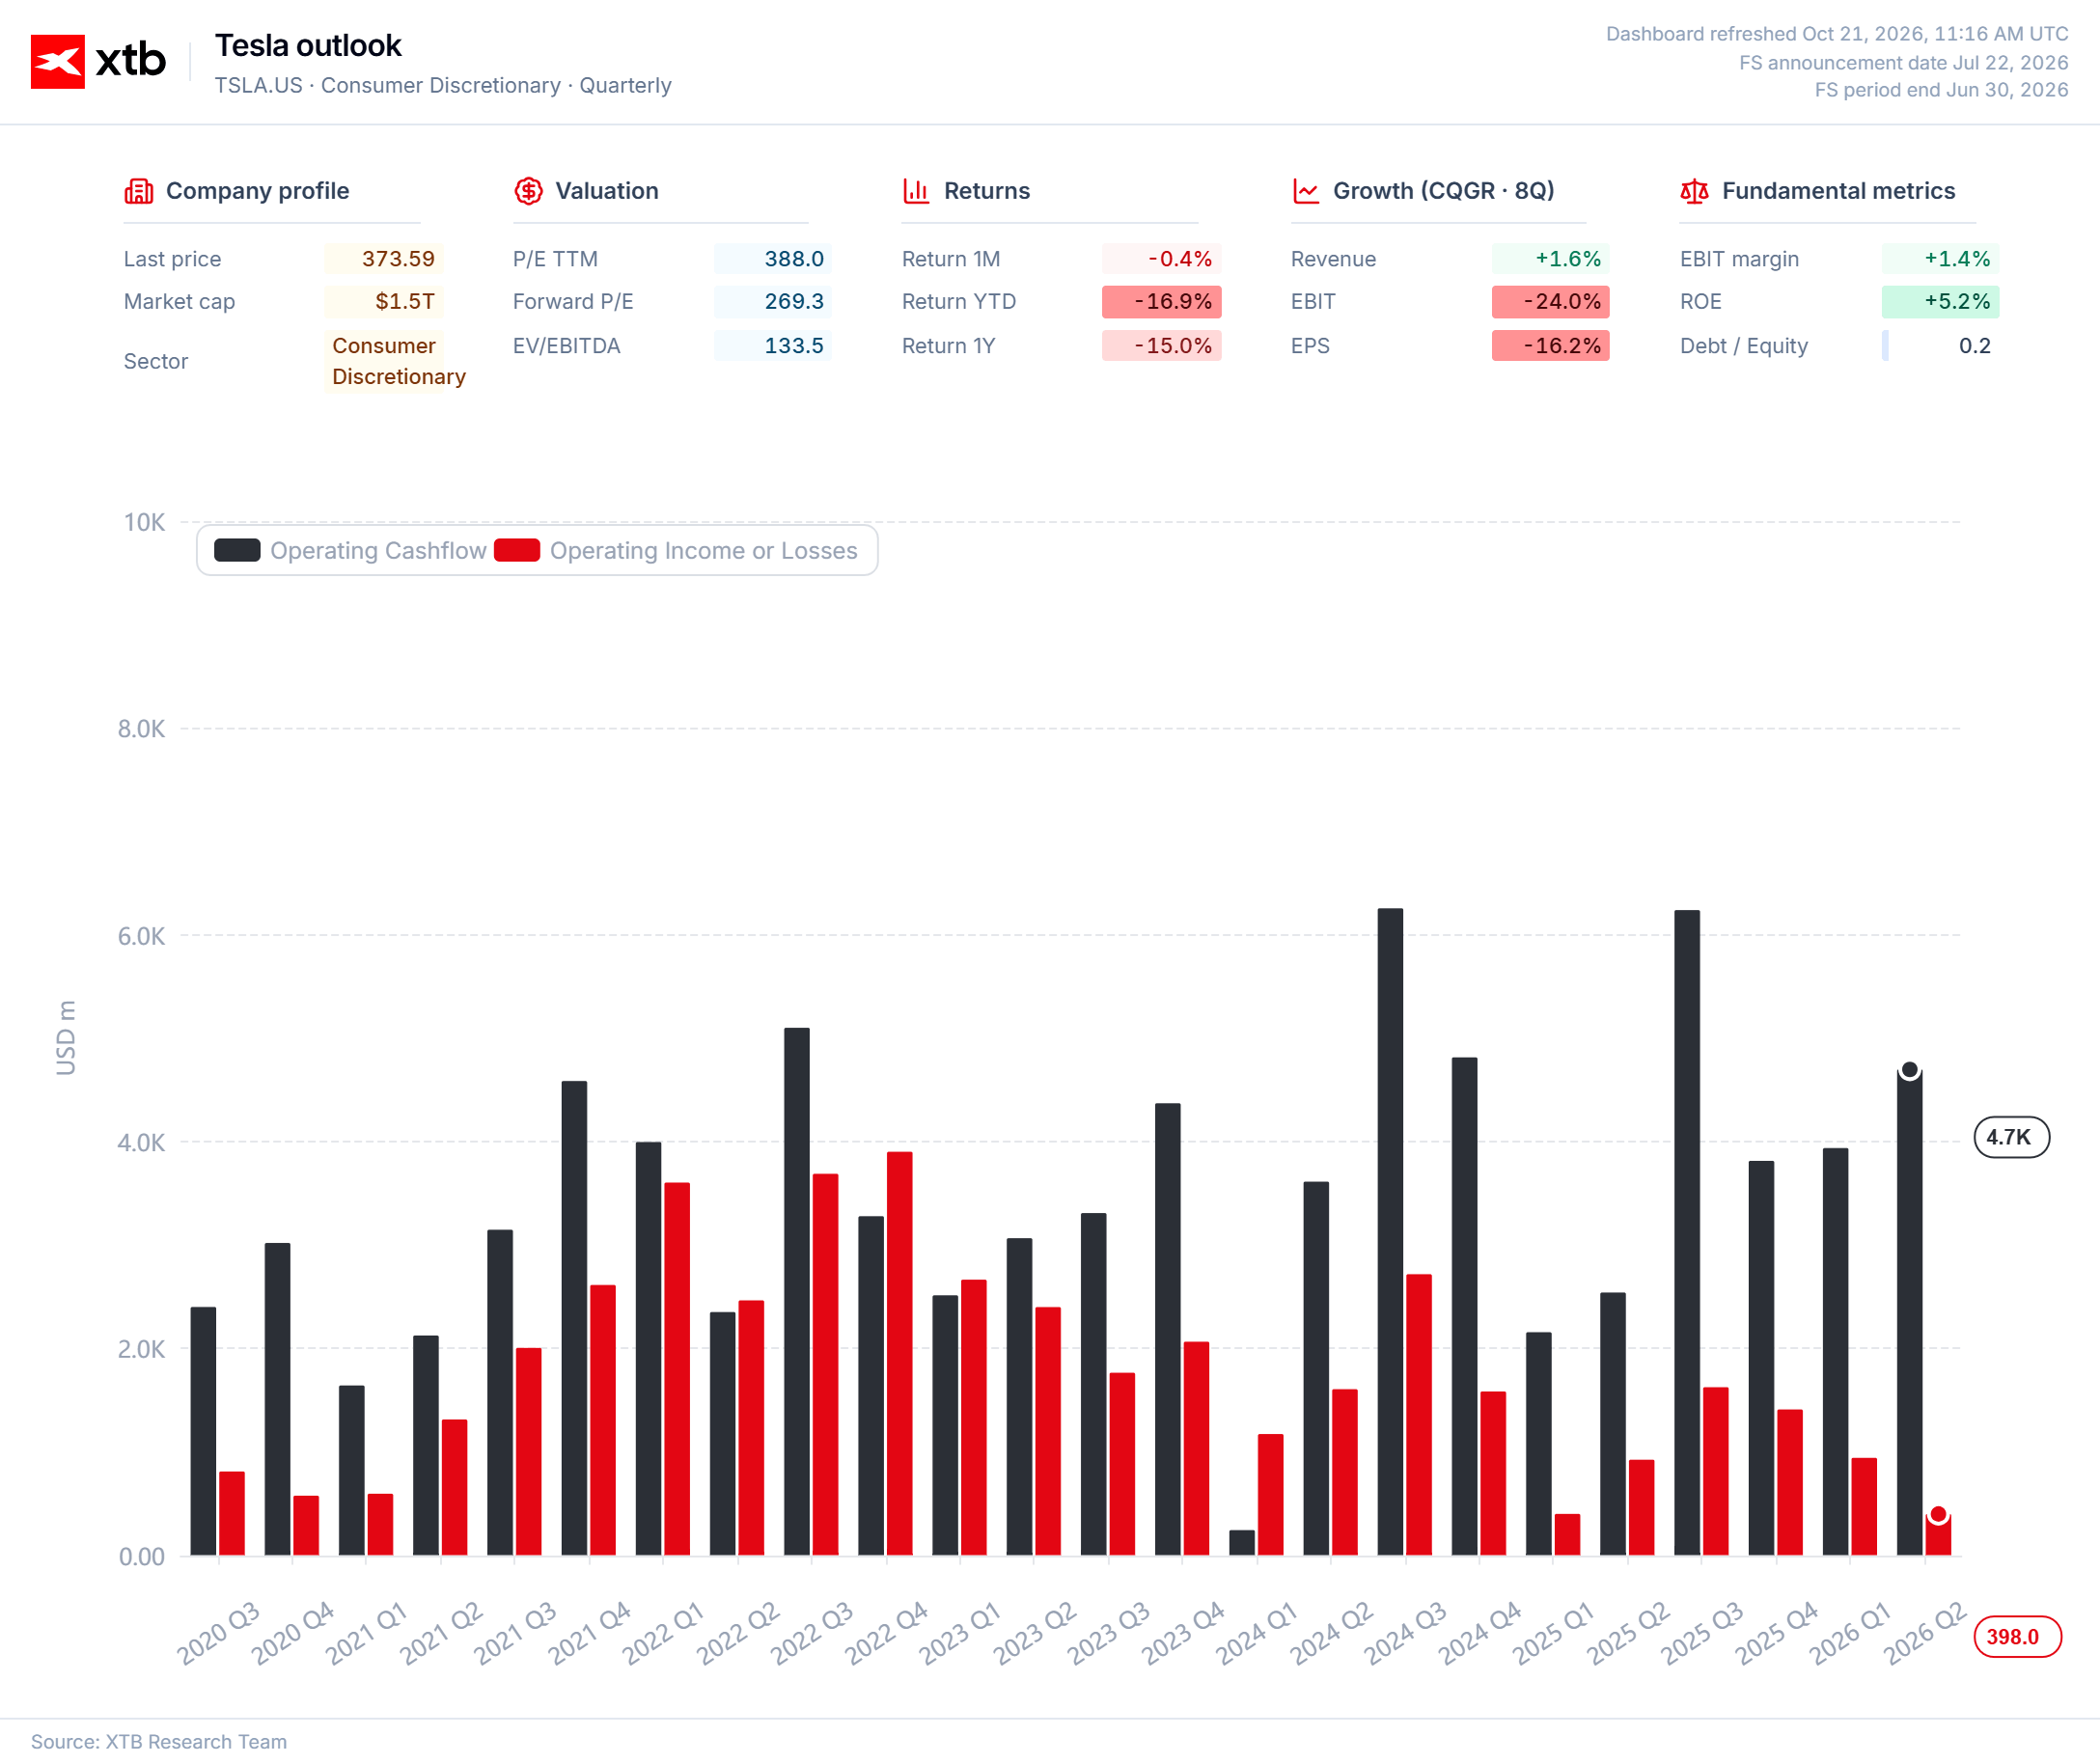
To keep investor sentiment at current levels, Tesla needs to show an Auto margin (excluding credits) of no less than 16%. An optimistic scenario would be an Auto margin in this segment at or above 17%.
A merger?
For several months, speculation about a potential merger between Tesla and SpaceX has been growing louder. During a SpaceX investor conference, Elon Musk revealed that the prospect of a transaction is currently in the early stages of review by a special committee formed for this purpose.
The CEO’s response was evasive and emphasized uncertainty about next steps. However, given Musk’s history of managerial decisions, a merger would be more routine than unprecedented.
It is hard to expect that within 24 hours the companies’ situation and the views of the alleged committee would change enough for Musk to provide more details on a merger or the lack of one. Still, investors may closely watch for any information related to such a transaction.
Robots and taxis
Shareholders place huge, mostly long-term hopes on Tesla’s FSD, Robotaxi and “Optimus” androids, and from a product perspective they will be a key part of the conference. These segments can be described as having a degree of business-case justification that is inversely proportional to public sentiment.
- FSD: Despite difficulties and challenges, both technical and regulatory, FSD is delivering tangible improvements operationally and in user experience. Confirmation of strong momentum in this segment would be subscriber growth above trend and improved retention over 3 to 12 month intervals.
- Robotaxi: Tesla’s autonomous car project is gaining momentum despite local regulatory pushback. Recently, the NHTSA confirmed the commercial deployment of unmanned Cybercabs in Austin, but at the same time launched an investigation to verify whether a design without traditional controls complies with federal safety standards. According to the latest MarketWatch summary, nearly 350 Cybercabs have been registered in Austin, of which 187 were active. The scale effects and operating leverage of this business are enormous in theory and could more than justify current valuations with P/E multiples above 300 and 150, on trailing and forward bases. However, the regulatory wall still has to be overcome for profits to materialize.
- Optimus: Despite ambitious declarations, Tesla’s “Optimus” androids remain an advanced demonstration product with low consumer usefulness and questionable margins. An investigation by "The Information" indicates production is still limited to hundreds rather than thousands per week, with defect rates as high as 50%. Despite declared purchase commitments of up to 10,000 machines, Tesla has not yet provided any data on delivery timelines or margins for the new product line. The product remains a capital-intensive demonstration until the company provides more information.

SpaceX Results: Can Starlink Carry the AI Revolution?

CoreWeave: Record Demand Collides with Crushing Costs


Chart of the Day: US100 (Nasdaq 100). Rebound in AI trade vs. weakening technical picture



Macro Calendar - UK Labor Market, ZEW Sentiment, and Wall Street Giants' Reports
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.