


Wall Street is set to open lower on Thursday. The Nasdaq is down around 1.3%, the S&P 500 is losing 0.3%, and the Dow Jones is falling 0.2%. Strong US economic data has failed to lift market sentiment. Investors are focused on earnings from major technology companies, particularly Alphabet, whose shares are plunging following its quarterly report.
US GDP grew at an annualized rate of 3.4% in the third quarter, beating forecasts of 3.2%. PCE inflation came in broadly in line with expectations but offered little reason for the Federal Reserve to become more optimistic. Annual inflation accelerated to 3.6% from 3.4% the previous month. The economy continues to expand at a solid pace, but price pressures remain persistent. This combination makes it harder for the Fed to resume cutting interest rates.
Yesterday’s decision to leave interest rates unchanged was widely expected. However, the split among FOMC members proved more significant than the decision itself, with two officials favoring a rate hike. With economic growth remaining strong and inflation elevated, a swift shift toward monetary easing is becoming increasingly difficult to justify. For Wall Street, this means borrowing costs could remain high for longer than some market participants had anticipated.
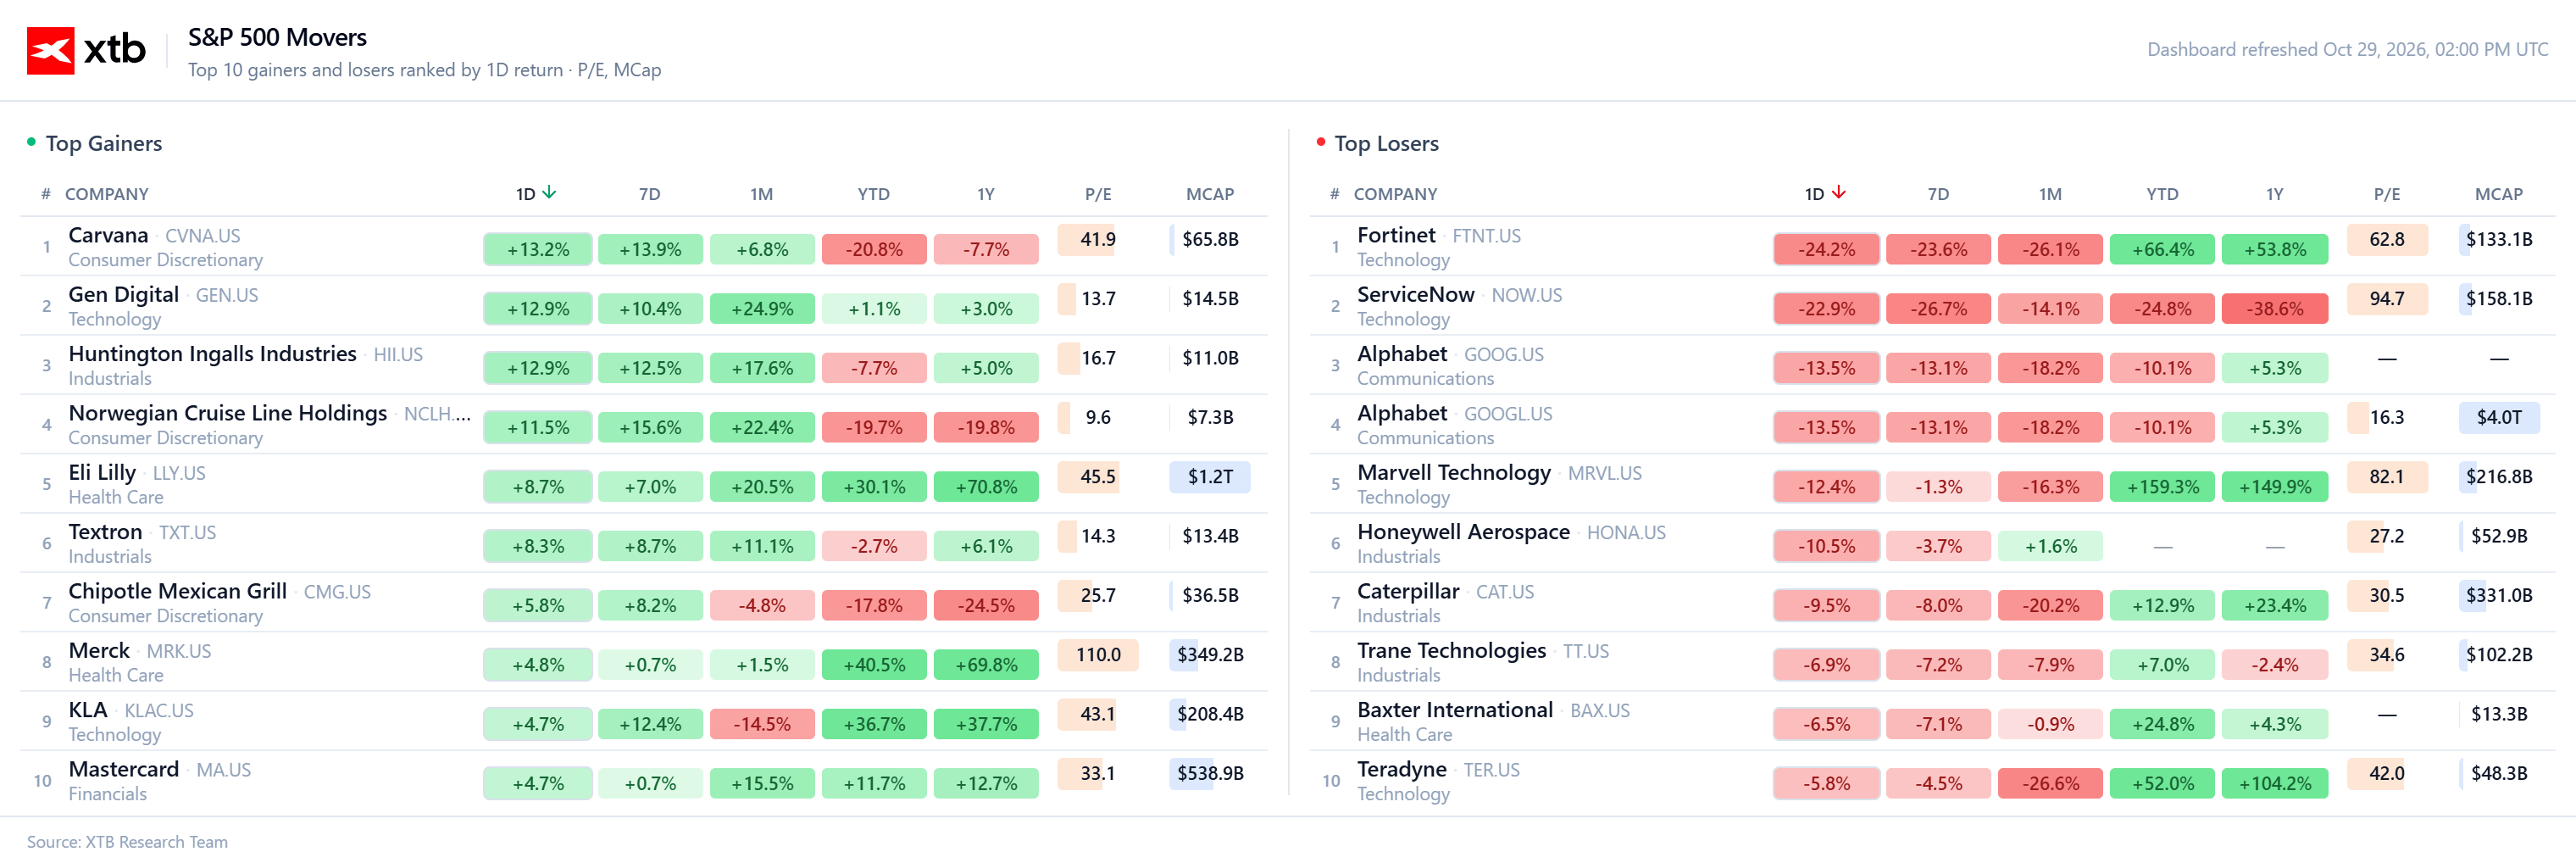
Alphabet is putting the greatest pressure on technology stocks. Its results disappointed investors, while heavy spending on AI development has once again raised questions about when massive investments will translate into higher profits and stronger cash flows. Rising expenditure alone is no longer enough to convince investors that the business is moving in the right direction. With valuations stretched, expectations for the largest technology companies remain high, leaving little room for disappointment.
Microsoft delivered a much stronger performance, supported by robust growth in its Azure cloud business. The contrasting market reactions to the two companies’ results highlight how selective investors have become toward businesses developing AI. Capital is no longer treating the sector as a single growth story. What matters now is actual performance, revenue growth and clear evidence that spending on infrastructure is generating adequate returns.
Today’s Nasdaq sell-off is therefore about more than one disappointing earnings report. High expectations for Big Tech are colliding with the rising costs of AI development, while strong macroeconomic data reinforces the prospect of restrictive Fed policy. Amazon will report its results after the market close. Its earnings will provide another test of whether investors are still willing to pay a premium for AI growth or are beginning to demand clearer evidence of profitability.
Source: XTB Research
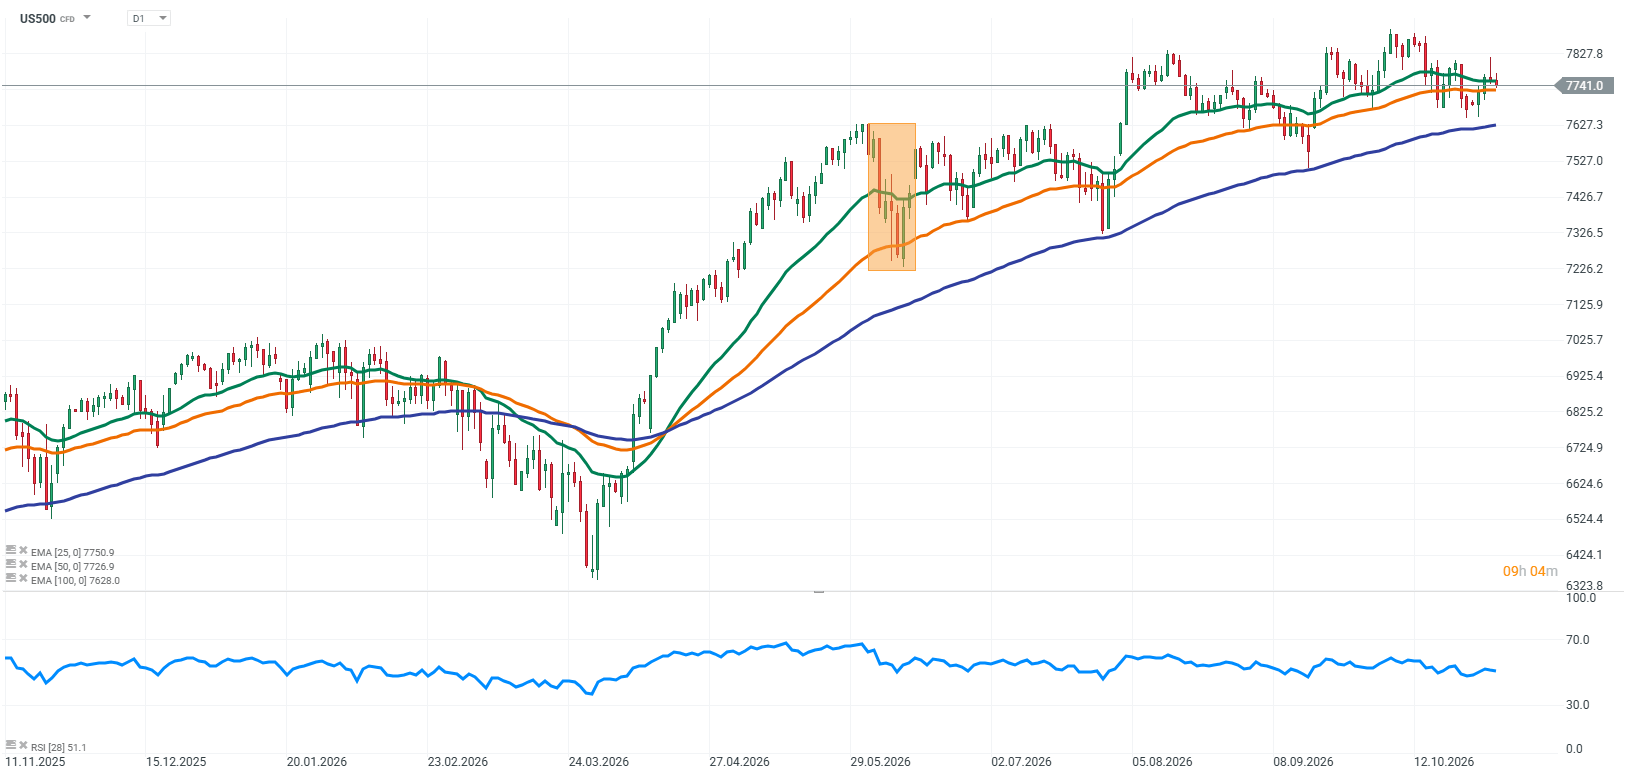
S&P 500 futures (US500) are edging lower, with sentiment weighed down primarily by Alphabet’s disappointing results and concerns over the returns on AI investments. Microsoft’s strong performance has not been enough to offset the pressure, as investors scrutinize rising spending by technology giants. Persistent US inflation remains another headwind, limiting the Federal Reserve’s room to cut interest rates.
Source: XTB Research
Company News
Microsoft delivered strong results, confirming that demand for artificial intelligence and cloud services continues to drive growth. Revenue and earnings per share exceeded analysts’ expectations, while Azure’s sustained growth remained a key highlight. The results are significant for investors as Microsoft commits substantial resources to data centers and AI infrastructure, and the market is increasingly focused on whether these investments are translating into higher revenue and profits.
Key results:
-
Revenue: $92.28 billion, compared with $77.6 billion a year earlier, up 19%
-
Net income: $36.63 billion, compared with $27.75 billion a year earlier, up 32%
-
EPS: $4.92 on a GAAP basis
-
Market consensus: approximately $90.63 billion in revenue and EPS of $4.73
-
Microsoft Cloud revenue: $63.9 billion, up 30% year over year
-
Azure growth: 48% year over year
-
Operating margin: approximately 50%
Azure remains the main growth driver, demonstrating that businesses continue to increase spending on cloud services and AI solutions. Microsoft benefits from its broad enterprise services ecosystem, which helps it commercialize new technologies. In the coming quarters, investors will be watching whether further AI revenue growth can sustain high profitability as capital expenditure continues to rise.
Alphabet disappointed investors despite strong revenue growth and very solid Google Cloud results. Its shares are down around 12%, as the market focuses on weaker earnings and rising capital expenditure. The company is committing substantial resources to AI development and data centers, but investors are increasingly questioning when this spending will translate into higher profits and more stable cash flows.
Key results:
-
Revenue: $127.58 billion, compared with $102.35 billion a year earlier, up 25%
-
Net income: $26.17 billion, compared with $34.98 billion a year earlier, down 25%
-
EPS: $2.12 on a GAAP basis
-
Google Cloud revenue: $30.71 billion, up 103% year over year
-
Advertising revenue: $82.01 billion, below analysts’ expectations
-
Capital expenditure: $51.36 billion
-
Free cash flow: -$9.07 billion
Google Cloud remains Alphabet’s key strength, benefiting from growing demand for AI infrastructure. The challenge lies in the scale of investment, which is weighing on cash flow, and uncertainty surrounding the future of its advertising business. AI-powered search could reshape the company’s established revenue model, making effective monetization of new solutions increasingly important. Investors are now focused not only on revenue growth but also on Alphabet’s ability to maintain profitability and generate cash.
Amazon will be in the spotlight today ahead of its third-quarter earnings release. Investors will focus primarily on AWS, its cloud computing division, and any updates on further spending on AI infrastructure. Amazon is benefiting from rising demand for computing capacity, but the scale of its investments means the market is scrutinizing their returns more closely. Following the recent sell-off in technology stocks, investors are looking for more than solid results: they want concrete signs that AI spending will generate adequate returns.
Earnings expectations:
-
Revenue: approximately $202.26 billion, up 12.2% year over year
-
EPS: approximately $1.96
AWS growth will be a key metric, as the division accounts for a significant share of Amazon’s operating profit and remains one of the main beneficiaries of AI development. Investors will also assess capital expenditure guidance and its impact on free cash flow. If Amazon demonstrates that higher spending is translating into faster cloud growth and improved profitability, the market could react positively. However, if investment continues to rise without clear evidence of improved efficiency, even strong headline results may not be enough to drive the stock higher.


Daily Summary: Bloody Thursday on Wall Street: Nasdaq Leads the Sell-Off

Silver falls, testing the $52 Level


Amazon Preview: After Microsoft and Alphabet, the Market Won’t Forgive a Disappointment

Intel Preview: Server CPU Boom Creates Opportunity for Improved Results
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.