

- Alphabet posted third-quarter revenue of 127.6 billion USD, up 25% year-on-year.
- Net income declined by 25% to 26.2 billion USD due to equity investment losses.
- Earnings per share reached 2.12 USD, falling short of analyst expectations.
- Google Cloud revenue surged 103% to 30.7 billion USD with a higher operating margin.
- Capital expenditures rose to 51.4 billion USD, driving negative free cash flow.
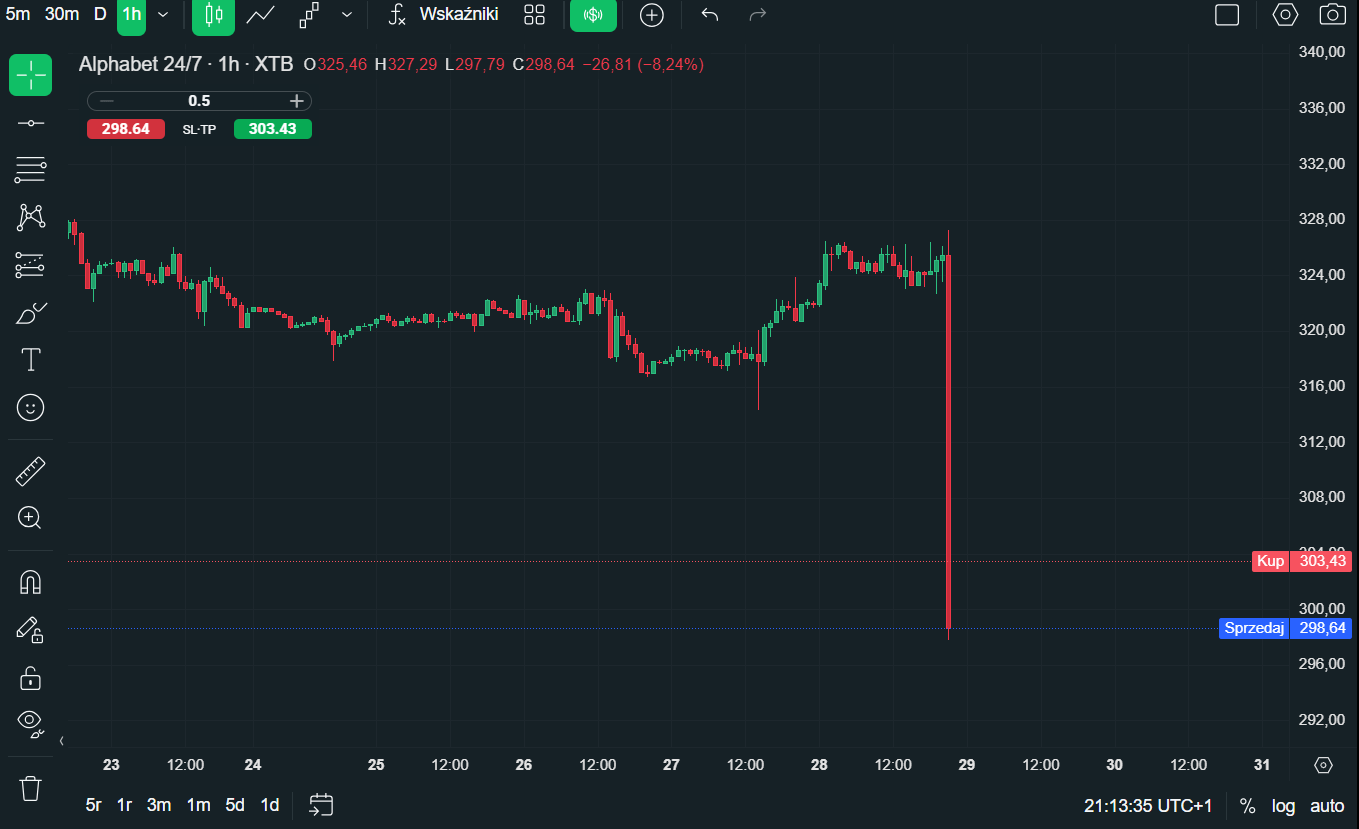
- Alphabet shares fell 8.25% in after-hours trading following the earnings release.
Alphabet ended the third quarter of 2026 with revenue of $127.6 billion, up 25% year-over-year, marking its thirteenth consecutive quarter of double-digit revenue growth. However, the figure came in slightly below analysts’ expectations of approximately $128 billion. Operating income increased by 30% to $40.6 billion, while the operating margin improved from 30.5% to 31.8%. That, however, is where the good news ends, as net income painted a much weaker picture, declining by 25% to $26.2 billion. Earnings per share came in at just $2.12, compared with expectations of nearly $3.00. The decline in net income was partly attributable to an $8.7 billion loss on equity investments, resulting from changes in the valuation of financial assets held by the company. This loss reduced earnings per share by $0.55, although Alphabet did not disclose which specific investments were responsible for the negative result.
Despite solid operating growth, investors have reacted decisively negatively, with Alphabet shares falling 8.25% in after-hours trading and testing the psychological $300 level. The market is also placing increasing emphasis on the cost of financing the company's expansion into artificial intelligence.
Key Q3 2026 Results:
-
Revenue: $127.6 billion (+25% YoY).
-
Google Cloud: $30.7 billion (+103% YoY).
-
Google Search: $63.4 billion (+12% YoY).
-
YouTube Ads: $11.2 billion (+9% YoY).
-
-
Operating income: $40.6 billion (+30% YoY).
-
EPS: $2.12, versus expectations of approximately $3.00.
-
CapEx: $51.4 billion (+114% YoY).
-
Free cash flow: −$9.1 billion.
The biggest positive surprise was Google Cloud, which is increasingly emerging as the second major pillar of Alphabet's business. Segment revenue surged by 103%, compared with 82% in the previous quarter, significantly exceeding analysts’ expectations. More importantly, Cloud operating income jumped from $3.6 billion to $11.1 billion, while its operating margin climbed from 23.7% to an impressive 36.2%. This provides compelling evidence that the AI boom is beginning to translate not only into higher sales but also into stronger profitability. Google is also benefiting from its proprietary TPU chips, which it is increasingly offering to external customers, putting it in direct competition with other AI infrastructure providers.
Interestingly, despite growing competition from chatbots, Google recorded its fastest growth in search queries in five years, while the Gemini app surpassed one billion monthly active users. For now, AI therefore appears to be strengthening Google's ecosystem, although the risk of competing AI assistants capturing a share of search queries has not disappeared.
Massive AI Investments
Maintaining its position at the forefront of the new technology boom requires equally massive investment from Alphabet's enormous business operation. The company spent $51.4 billion on capital expenditures in the third quarter, more than double the amount invested a year earlier. This marked another quarter in which capital spending exceeded operating cash flow, resulting in negative free cash flow of $9.1 billion. At the same time, the company raised approximately $28.7 billion through bond issuance and $12.4 billion through equity issuance. The key reference point remains Alphabet's July CapEx guidance of $195–205 billion for the full year 2026. Meeting this target would imply spending of approximately $63–73 billion in the fourth quarter alone.
The sharp sell-off in Alphabet shares demonstrates that Wall Street is no longer willing to reward technology giants solely for impressive AI growth rates and massive investment commitments. Alphabet shares are down 8.25% following the earnings release, with the stock testing the $300 area, which now represents an important technical level. The decline is particularly striking given that Google Cloud revenue more than doubled and the group's overall profitability improved. Investors appear to be focusing instead on weaker-than-expected EPS, deteriorating cash flow, and the risk of further increases in capital expenditure.


Microsoft earnings: Cloud growth overshadows CAPEX & FCF questions



Daily Summary: Oracle drives the market higher, dollar weakens following Fed meeting (28.10.2026)


📊Hyperscaler Results: Alphabet and Microsoft. Will results justify giant investments?


US OPEN: The market awaits the Fed and Google’s earnings.
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.