


The main driver of volatility. The day was dominated by a rotation of capital out of the technology sector and artificial intelligence-related companies, which pushed the main indices down and marred the week’s performance. Investors are increasingly concerned that technology firms are taking on excessive debt to fund the expansion of AI infrastructure, and CoreWeave has become a symbol of these tensions, with its bonds suffering a sharp sell-off. Furthermore, the market was weighed down by concerns over growing competition from China in the memory sector and persistent inflationary pressure. As a result, capital flowed out of expensive growth stocks towards cheaper shares with stable cash flows.
Geopolitics. Tension in the markets was fuelled by the escalation in the Strait of Hormuz, where Iran stepped up attacks on ships and sank the container ship GFS Pride, in a bid to curb oil exports. At the same time, the energy truce between Russia and Ukraine announced by President Trump collapsed, and President Zelenskyy announced the resumption of attacks on Russian refineries. Despite the declared ceasefire, the Kremlin continued to strike at Ukrainian infrastructure, whilst a Russian refinery in Ryazan suspended operations at one of its units following a drone attack. Tensions in US-Iran relations remained the main driver of risk premiums in commodity prices.
Macroeconomic data. This week’s inflation figures came in higher than expected, whilst producer price inflation recorded its sharpest rise since 2022, confirming that price pressures are spreading beyond the energy sector itself. Consumer inflation remained well above the Fed’s 2 per cent target. Fed Governor Kevin Warsh highlighted the wave of spending fuelling inflation, but emphasised the resilience of the US economy, underpinned by an investment boom centred on AI. Markets are currently pricing in around an 85 per cent chance of rates remaining unchanged at the meeting on 27 and 28 October, although some analysts expect rate rises in December and January.
Indices. On Wall Street, the S&P 500 fell by around 1 per cent and the Nasdaq dropped by nearly 1.9 per cent, whilst the Dow Jones fared better thanks to banks and energy companies. The SOX semiconductor index recorded its worst week since April 2025, whilst the SMH chip ETF fell by around 8 per cent over the week. In Europe, the broad-based STOXX 600 gained 0.7 per cent and closed its best week since the end of June, buoyed by strong corporate earnings. In the CFD markets, technology and Asian indices suffered the heaviest losses, with the JP225 down 2.04 per cent and the US100 falling by 1.93 per cent, whilst the Polish W20 stood out with a gain of 1.02 per cent.
Shares. Companies linked to artificial intelligence came under the greatest pressure, with CoreWeave falling by around 10 per cent, with debt exceeding $51 billion and a bond yield above 15 per cent. Chipmakers, including Micron, AMD and SanDisk, as well as tech giants Meta and Microsoft, also fell. Bucking the market trend were energy companies, led by Chevron, and the banks Goldman Sachs and JPMorgan, which limited the Dow Jones’s losses. Tesla failed to hold onto its morning gains despite the launch of the new Roadster, whilst Netflix fell following the appointment of a new head of content.
Currencies. The foreign exchange market remained relatively calm, with the dollar holding close to its multi-year highs, although its index edged down slightly. The euro held steady around 1.122, supported by the stabilisation of eurozone bond yields, with the final reading for September inflation at 3.8 per cent – still well above the ECB’s target. The pound gained around 0.35 per cent against the dollar. The zloty market showed signs of stabilisation, with the USDPLN pair rising marginally by 0.03 per cent and the EURPLN pair by 0.19 per cent.
Commodities. It was a day dominated by oil, which continued its strong rally on the back of concerns over supplies from the Middle East and attacks on Russian refineries. US WTI crude oil surpassed $99 per barrel for the first time since September and gained over 8 per cent over the week, whilst Brent rose above $109. On the CFD markets, Brent crude rose by 3.35 per cent and WTI by 1.22 per cent, also supported by a fall in US stocks following disruptions caused by Hurricane Isaias. Gold edged down slightly to around $4,161 per ounce, whilst natural gas, down by 2.40 per cent, and silver also remained under pressure.
Cryptocurrencies. Weakness persisted in the digital assets market, following a deterioration in sentiment surrounding the technology sector and concerns about the funding of AI projects. Bitcoin fell by around 1.2 per cent, slipping to around $81,200. The sell-off was part of a broader risk aversion that has hit assets sensitive to the cost of capital and high valuations particularly hard this week.
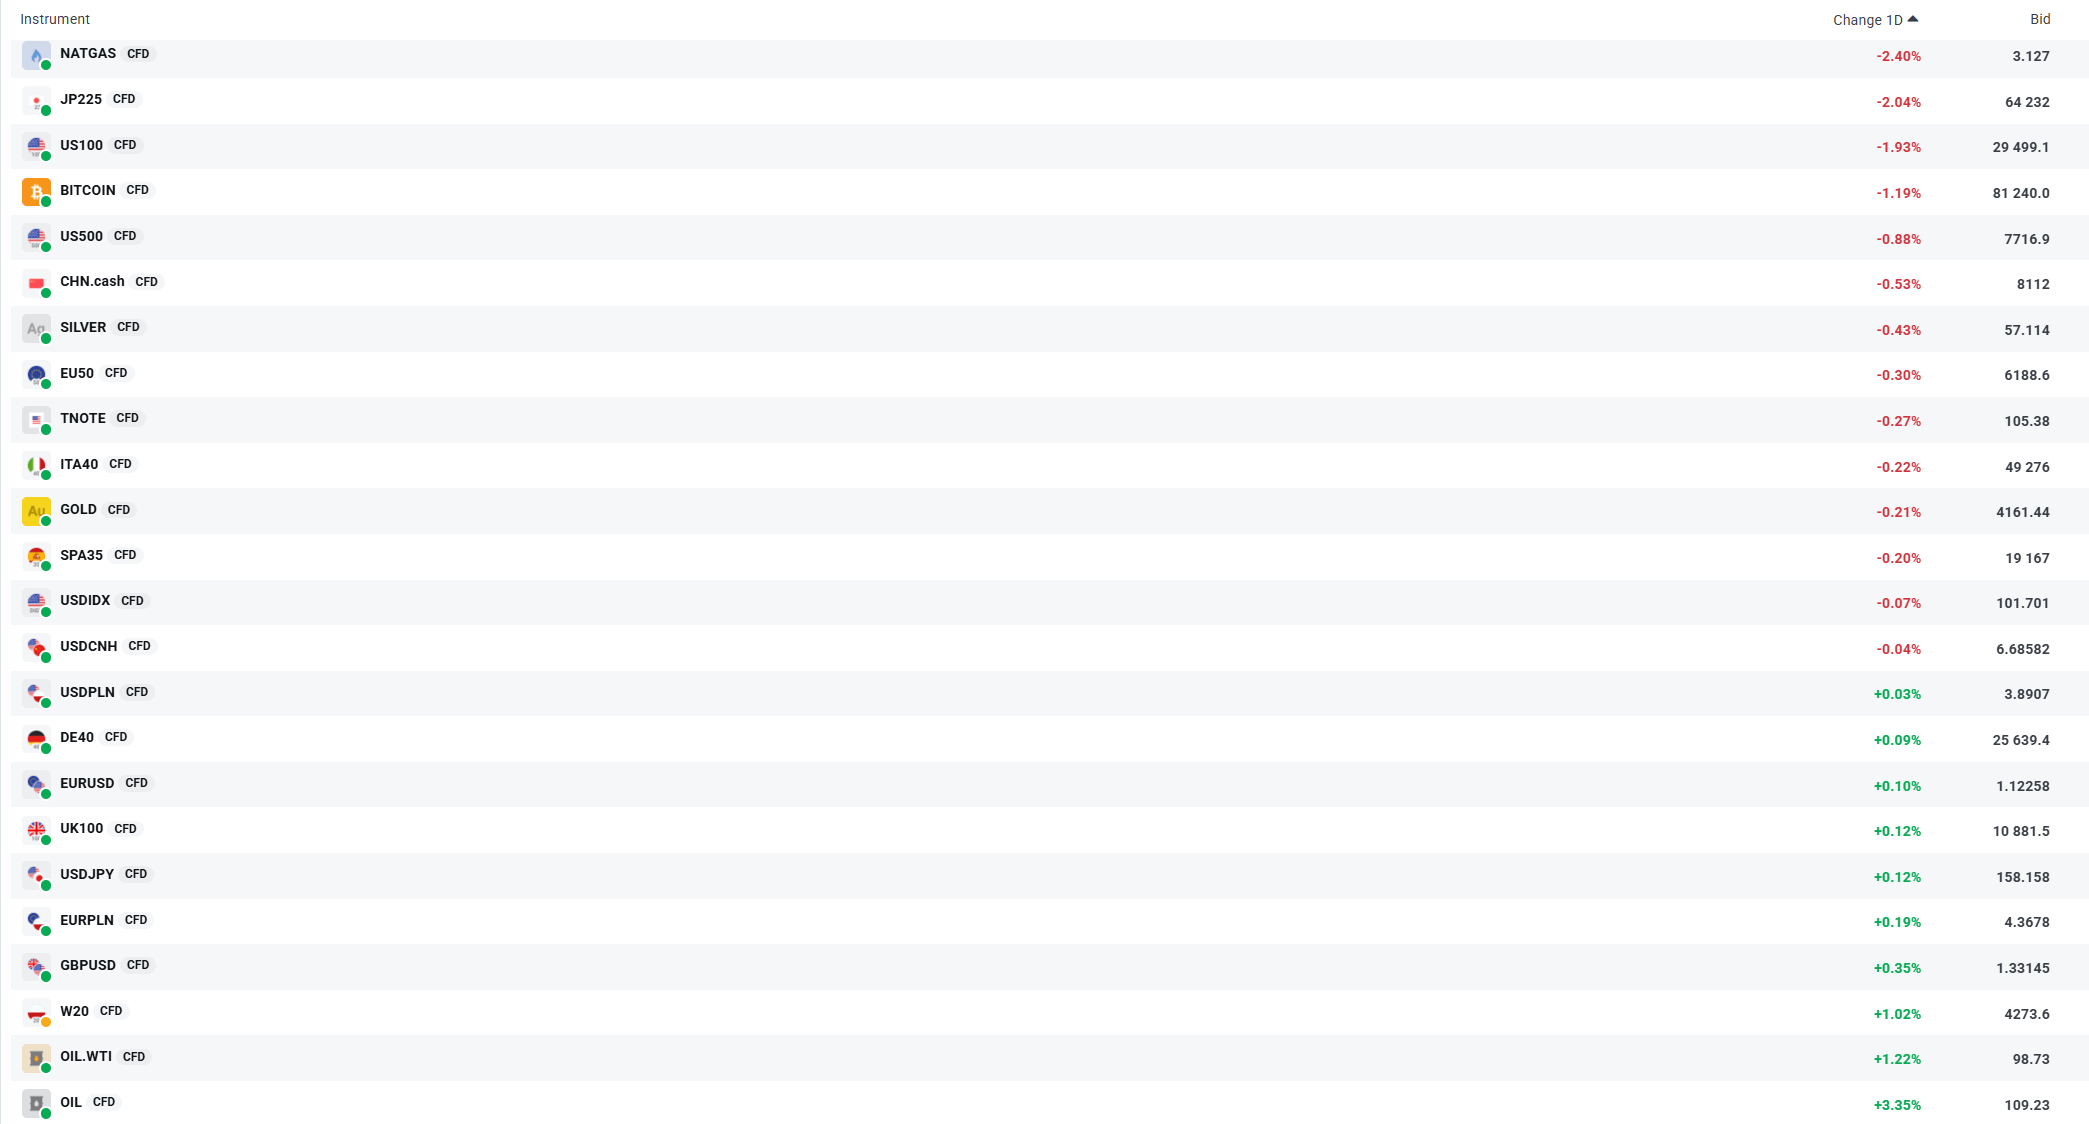
Volatility observed at the close of trading on selected key instruments. Source: XTB


Three Markets to Watch Next Week (October 16, 2026)


Market wrap: European indices rebound 🔼 Defence stocks on the rise


🔼 EURUSD continues to rebound


Chart of the Day: NATGAS - Are there chances for a seasonal rebound amid warm weather?
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.