


The beginning of the week brings moderate volatility to the markets, overshadowed by geopolitical tensions in the Middle East and Eastern Europe, where the Russian Ministry of Defense reported attacks on Ukrainian ports and logistics centers.
The geopolitical situation remains tense following Iran's announcements regarding changing the geography of the war in response to potential new strikes.
In Asia, attention was drawn to positive trade data from South Korea, where the trade surplus rose in September and imports recorded a strong double-digit year-on-year growth. In Japan, financial markets remain closed due to a public holiday.
The calendar for the rest of the day lacks key hard macroeconomic data releases, but investors will focus on speeches by central bank representatives, including European Central Bank President Christine Lagarde and Bank of Canada Governor Tiff Macklem.
Key publications from the Asian session
- United Kingdom — Rightmove HPI m/m: result 0.7% versus previous reading of -2.0%, indicating a seasonal recovery in the housing market after previous declines.
- New Zealand — Credit card consumer spending y/y: result 3.5% versus previous reading of 5.3%, signaling a slight slowdown in household spending momentum.
Macroeconomic calendar
- All day Japan - Public holiday.
- 12:00 Eurozone - Bundesbank monthly report.
- 12:30 USA - FOMC member Goolsbee speech.
- 17:00 Eurozone - ECB President Lagarde speech.
- 17:05 Canada - BOC Governor Macklem speech.
- 21:00 Australia - RBA Deputy Governor Hunter speech.
Markets to watch
- EURUSD — Quotations of the common currency may come under the influence of the afternoon speech by ECB President Christine Lagarde, amidst the search for new signals regarding the future path of interest rates in the eurozone.
- Crude oil (WTI / Brent) — Commodity prices remain sensitive to the escalation of geopolitical rhetoric in the Middle East and reports of a decline in tanker traffic through the Strait of Hormuz.
EURUSD: Inverse H&S or just wishful thinking?
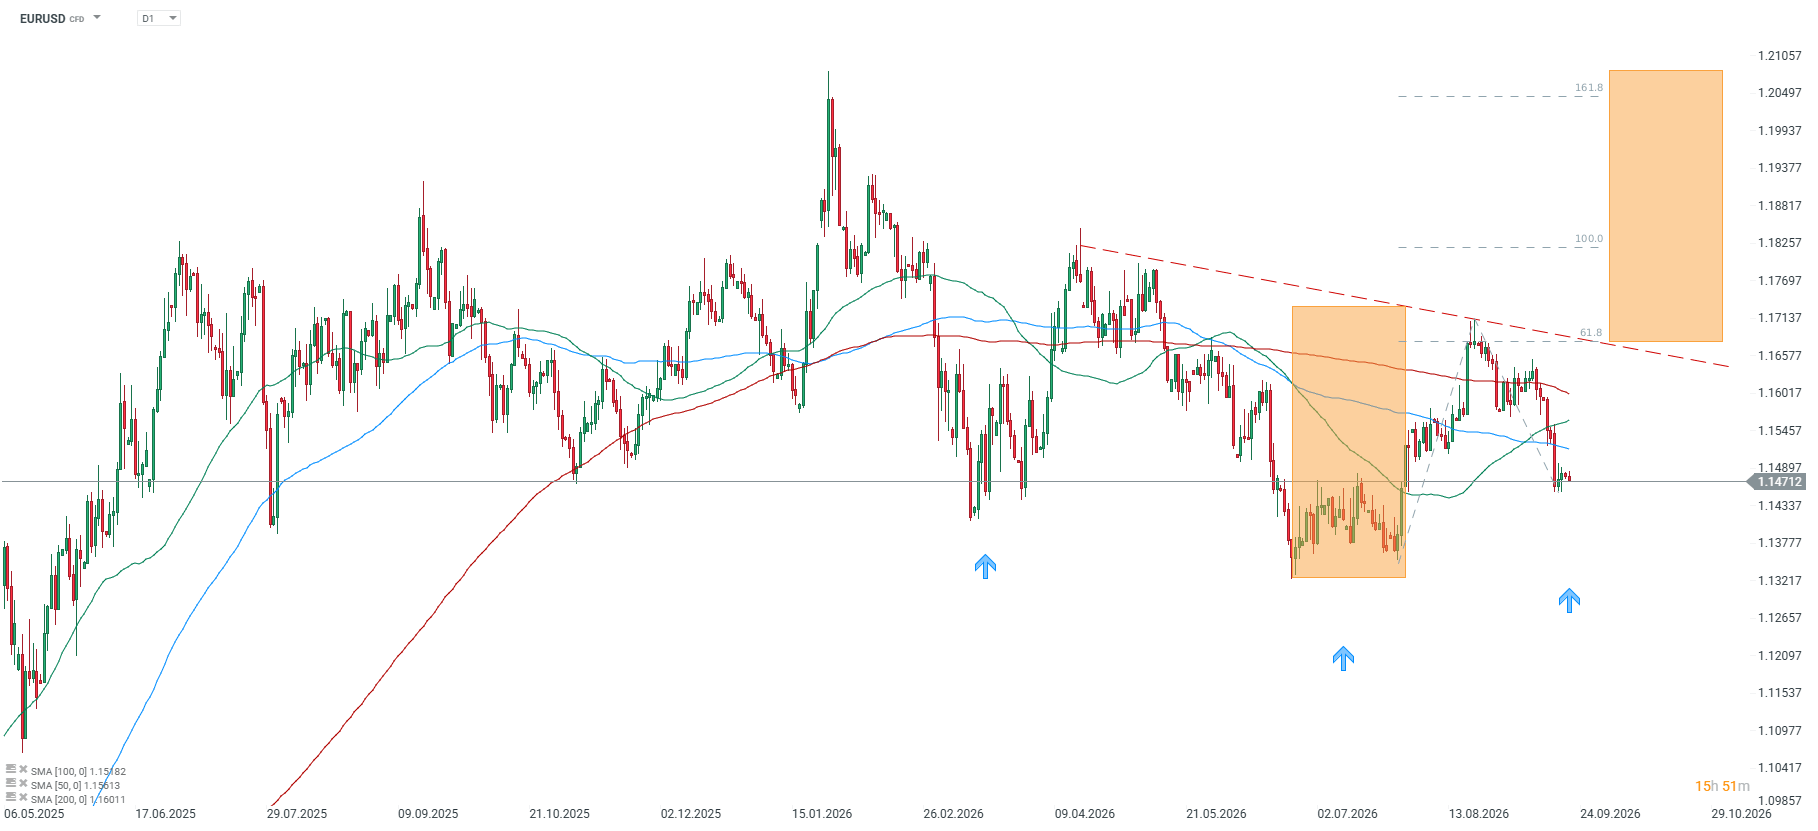
On the daily EURUSD chart, we can observe a potential inverse head and shoulders pattern, but upon closer inspection, this interpretation dissolves. To speak of a reliable inverse H&S, we need a distinct left shoulder, a lower head, and then a higher right shoulder and, most importantly, a breakout above the neckline. Meanwhile, the current structure is too chaotic, and the symmetry of the pattern leaves much to be desired. Instead of building a higher right shoulder and attacking resistance, the price has just turned back and is heading towards the lows again, which contradicts the logic of this pattern.
The key argument against the bullish narrative is provided by the moving averages. Quotations at 1.1471 are below all three main averages: SMA50 at 1.1561, SMA100 at 1.1518, and SMA200 at 1.1601. Furthermore, the averages are intertwined and pointing downwards, which forms a classic picture of a downtrend or at best a consolidation with a selling bias. Additionally, since the January peaks, quotations have been constrained by a descending trendline, which has successfully repelled every attempt at a rebound.
Although the dollar has been strengthening for some time and one could look for a potential recovery, we are currently talking more about distribution below the averages than a trend reversal. A serious discussion about an inverse H&S will only be possible when demand regains the moving average levels and overcomes the neckline in the 1.1560 to 1.1600 region, opening the way toward the 1.1670 zone and higher. Until that happens, testing the summer lows around 1.1320 remains more likely, and breaking them would deepen the declines. Nevertheless, if Lagarde were to trigger dollar strengthening today, the pattern could come into play, or at least the possibility of testing the descending trendline, potentially treated as the neckline.


Morning briefing: Trump-Xi in the shadow of geopolitical tensions (21.09.2026)


Yen loses ground after the BoJ decision
Hawkish remarks by BOJ Governor strengthen the yen – key takeaways
🏯Chart of the Day: Yen in a Trap. BoJ Hike That Weakened the Currency (18.09.2026)
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.