


President Xi’s first visit to the United States in over a decade ended without a major breakthrough. While both sides expressed a desire to maintain stable bilateral relations, persistent disputes over Taiwan, artificial intelligence, tariffs, and the war in Iran remained unresolved. Announcements were limited to an extension of the existing trade truce and the transfer of two giant pandas to Atlanta Zoo. These failed to move the market.
🌏 Key Macroeconomic Releases
Thursday
United States
- Initial jobless claims dropped by 1,000 to 197,000 in the week ending 19 September - coming in below consensus expectations (201,000) and near 57-year lows. The labour market remains resilient despite the Federal Reserve’s interest rate hikes and ongoing Middle East geopolitical tensions.
Figure 1: Weekly Initial Jobless Claims (2022 - 2026)
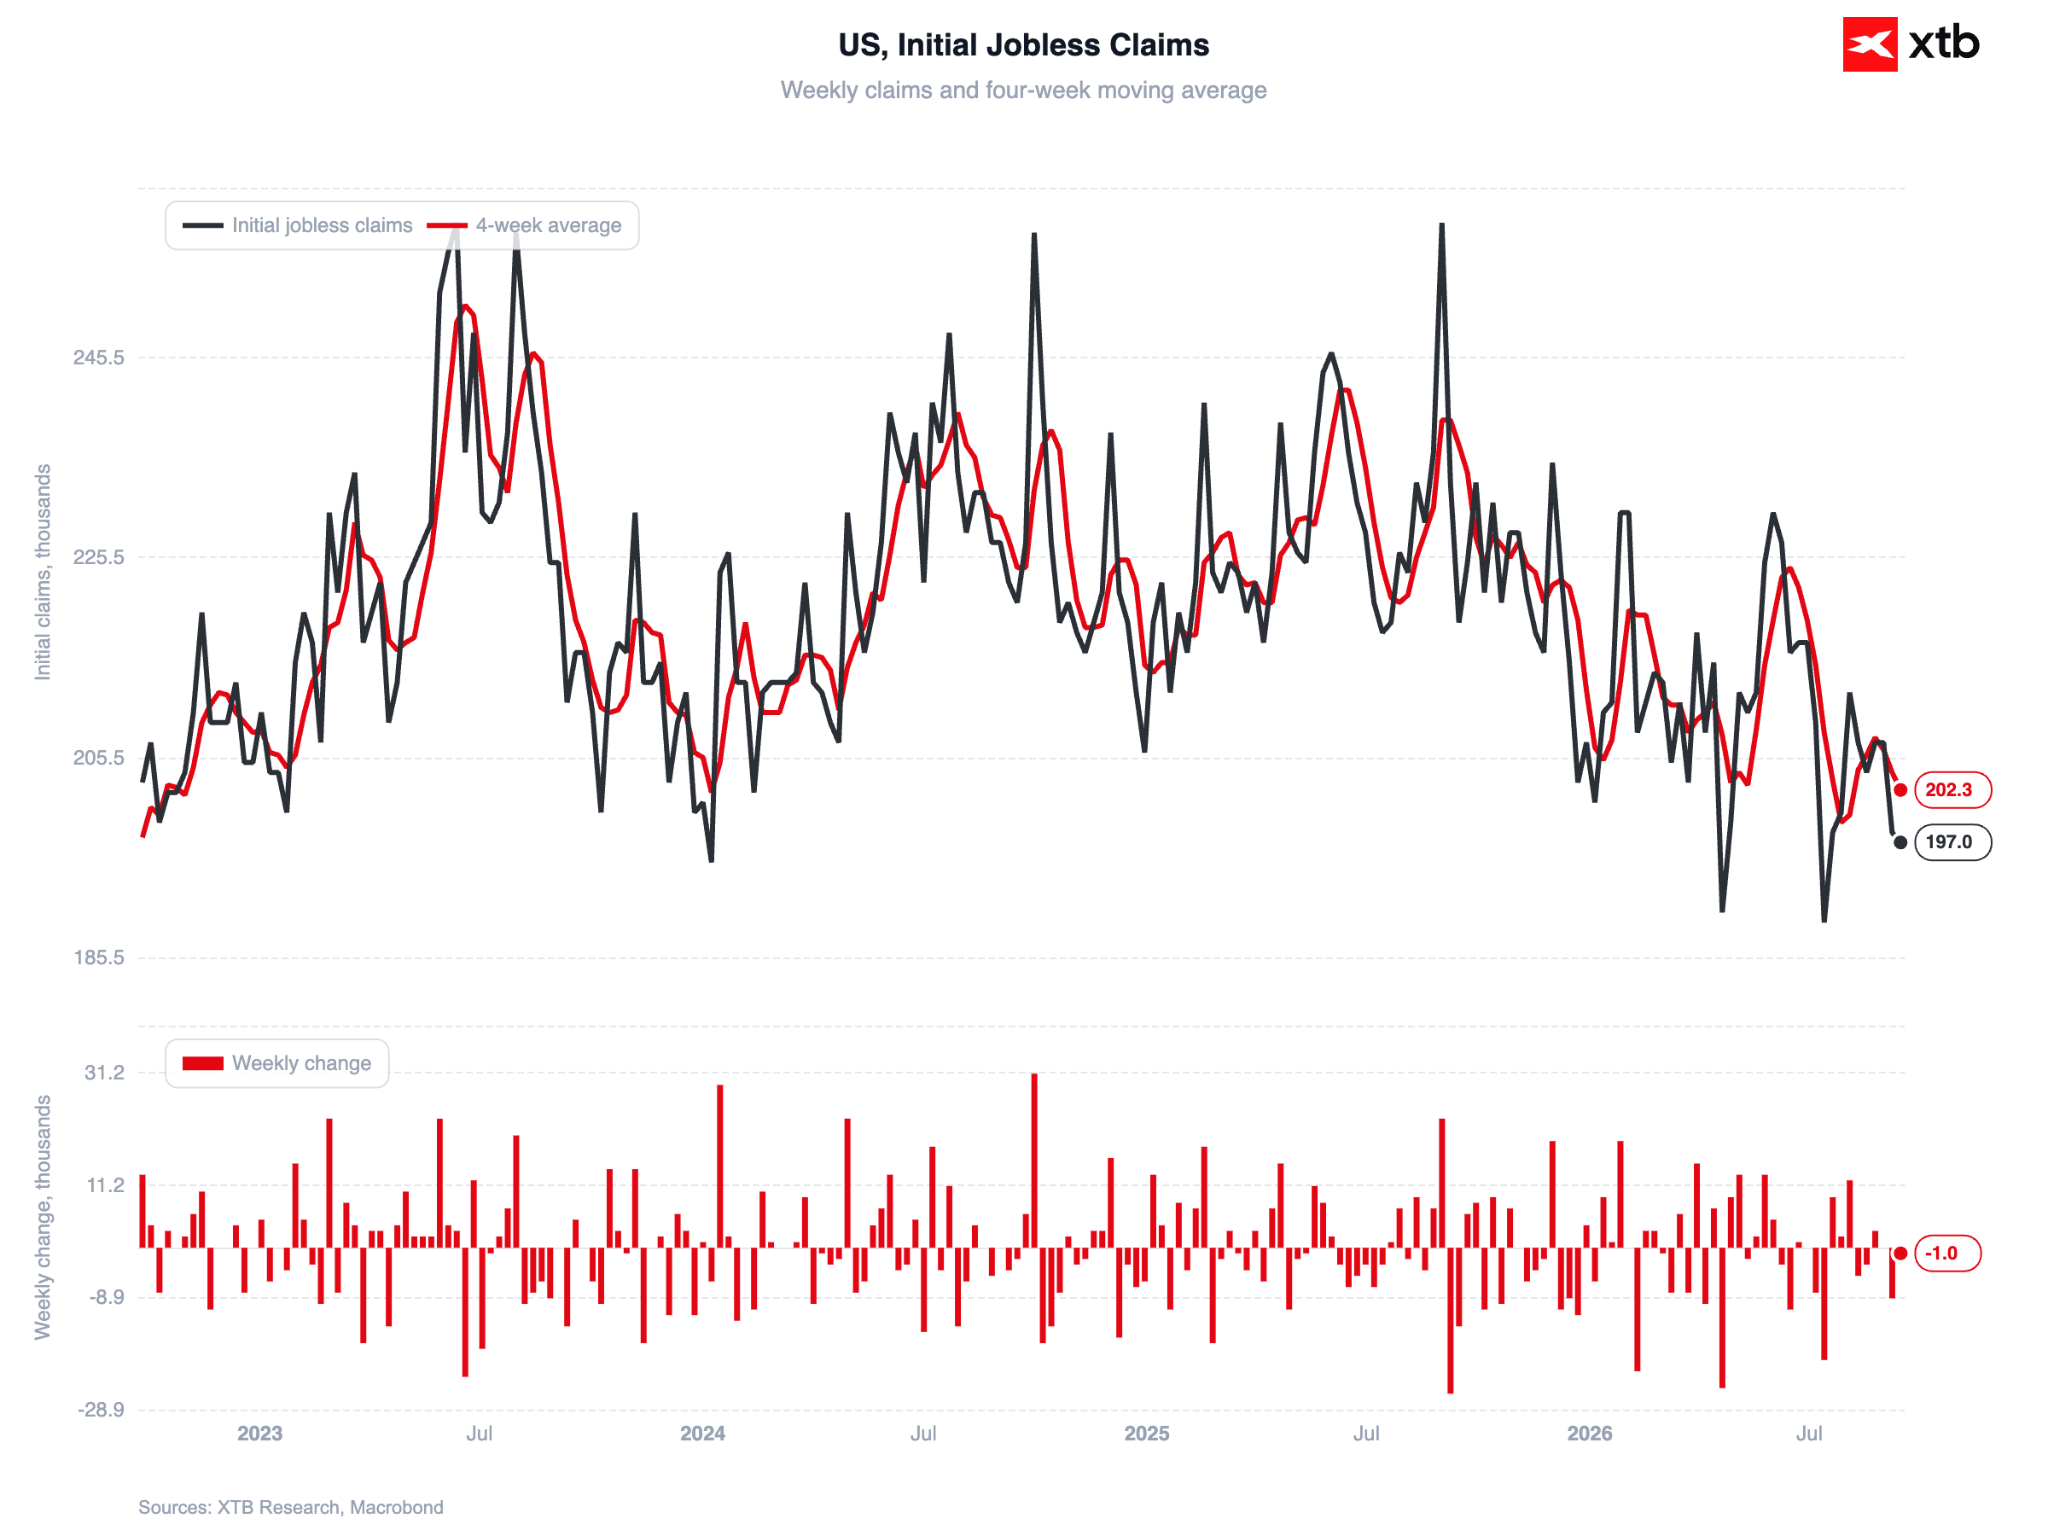 Source: XTB Research, 25.09.2026
Friday
Germany
- Consumer sentiment deteriorated sharply, with the October index falling to -30.6 points from -26.8 in September, well below consensus (-27.4). Rising energy prices weighed heavily on income expectations, causing the sub-index to plunge 16.7 points to -15.0 - its lowest level since April.
United Kingdom
- In a surprisingly positive reading, the index rose to -13 from -14 - hitting a two-year high (since August 2024) despite forecasts of a decline to -16. Both overall economic assessments and personal financial outlooks (an 8-month high) improved, though GfK cautioned that elevated inflation and higher energy costs could soon weigh on sentiment.
📆 Economic Calendar
Friday
Markets in China, Taiwan, and South Korea are closed today in observance of the Mid-Autumn Festival.
- United States: Durable Goods Orders for August
- Time: 1:30 PM
- Consensus: -0.3% MoM
- Previous reading: +1.1% MoM
- United States: Speech by Kansas City Fed President
- Time: 1:30 PM
- United States: Atlanta Fed GDPNow
- Time: 3:00 PM
- Consensus: 5.1%
- Previous reading: 5.1%
- United States: University of Michigan Consumer Inflation Expectations
- Time: 3:00 PM
- Consensus: 4.6% (1-year)
- Previous reading: 4.1% (1-year)
- CFTC Commitments of Traders (Speculative Positions)
- Time: 8:00 PM
🗂️ Corporate Earnings Releases
- Zena Tech ($ZENA.US) - BMO (Before Market Open)
- CBAK Energy ($CBAT.US) - BMO (Before Market Open)
3 Key Markets to Watch
OIL: The US and Iran are exploring a phased agreement regarding the reopening of the Strait of Hormuz. However, the physical market continues to price in elevated risk, with the spread between front-month Brent contracts widening to USD 6.80 (the widest level since April).
USDJPY: The yen strengthened to around 158.35 per USD after Japanese Finance Minister Katayama revealed that Donald Trump expressed concerns to Prime Minister Takaichi over yen weakness.
US10Y: The 10-year Treasury yield retreated to 5.19% following a surge of over 20 bps across two sessions (peaking at 5.24% on Thursday). 30-year yields reached nearly 5.5% - their highest level in over two decades. Swap markets continue to price in three additional 25 bps rate hikes from the Federal Reserve over the next 12 months.
—
Michał Jóźwiak, Financial Markets Analyst at XTB

Chart of the Day: Trump’s remarks strengthen the yen (25.09.2026)



Morning Wrap: Oil pulls back following reports of Washington-Tehran talks (25.09.2026)


Market Wrap: Further rise in oil prices weighs on European stocks (24.09.2026)


Bond yields highest since 2007
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.