


Intel will report its third-quarter results after Thursday’s market close. The market expects revenue of around $16.5 billion and adjusted earnings per share of $0.40. A year earlier, the company reported revenue of $13.65 billion and adjusted EPS of $0.23, respectively. Intel’s own guidance called for revenue of $15.8 billion to $16.8 billion, adjusted EPS of $0.38, and a gross margin of approximately 42%.
The outlook for server CPU sales is likely to attract the most attention. Data center expansion is driving demand for CPUs, while limited availability of certain chips could support price increases. Intel has an opportunity to improve its results through higher order volumes and more favorable selling prices. However, the extent of these gains will depend on the company’s production capacity, the competitiveness of its processors, and manufacturing costs.
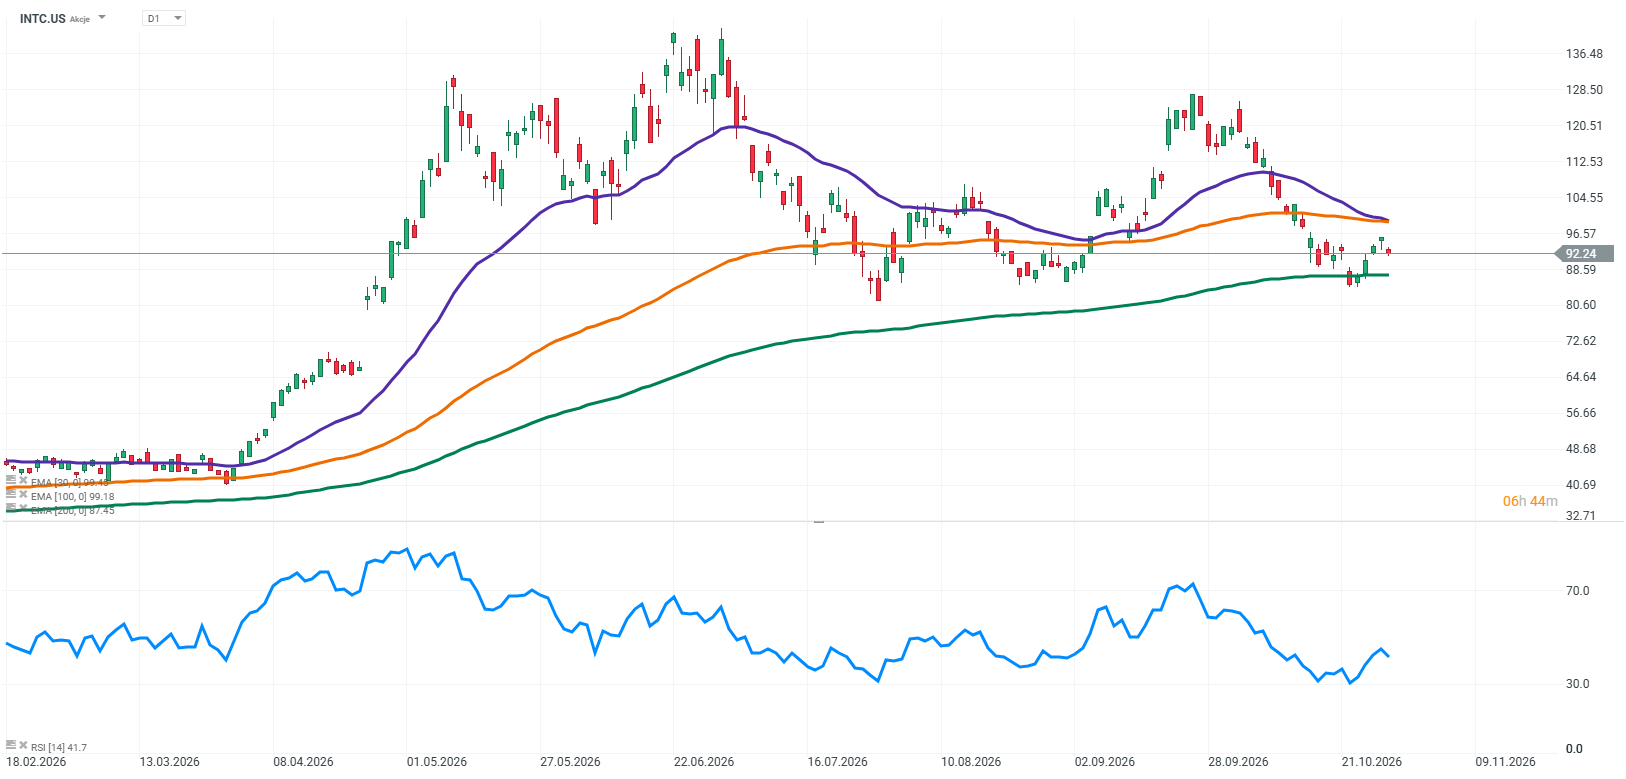
Intel shares currently trade at around $90–95, down from a June peak near $140. The pullback followed a sharp rally driven by expectations of a business recovery and the growing importance of CPUs in AI infrastructure. Thursday’s report will offer an opportunity to assess whether improving operating conditions justify the optimism that previously fueled the stock. The outlook for the coming quarters and concrete details on further restructuring could be particularly important for the share price.
Key Market Expectations
-
Third-quarter revenue: Around $16.5 billion, according to consensus estimates.
-
Adjusted EPS: Around $0.40.
-
Expected adjusted gross margin: Approximately 42%.
-
Key areas to watch: Server CPUs, selling prices, margins, capital expenditure, and restructuring.
-
Outlook for 2027: Order volumes and the ability to increase shipments.
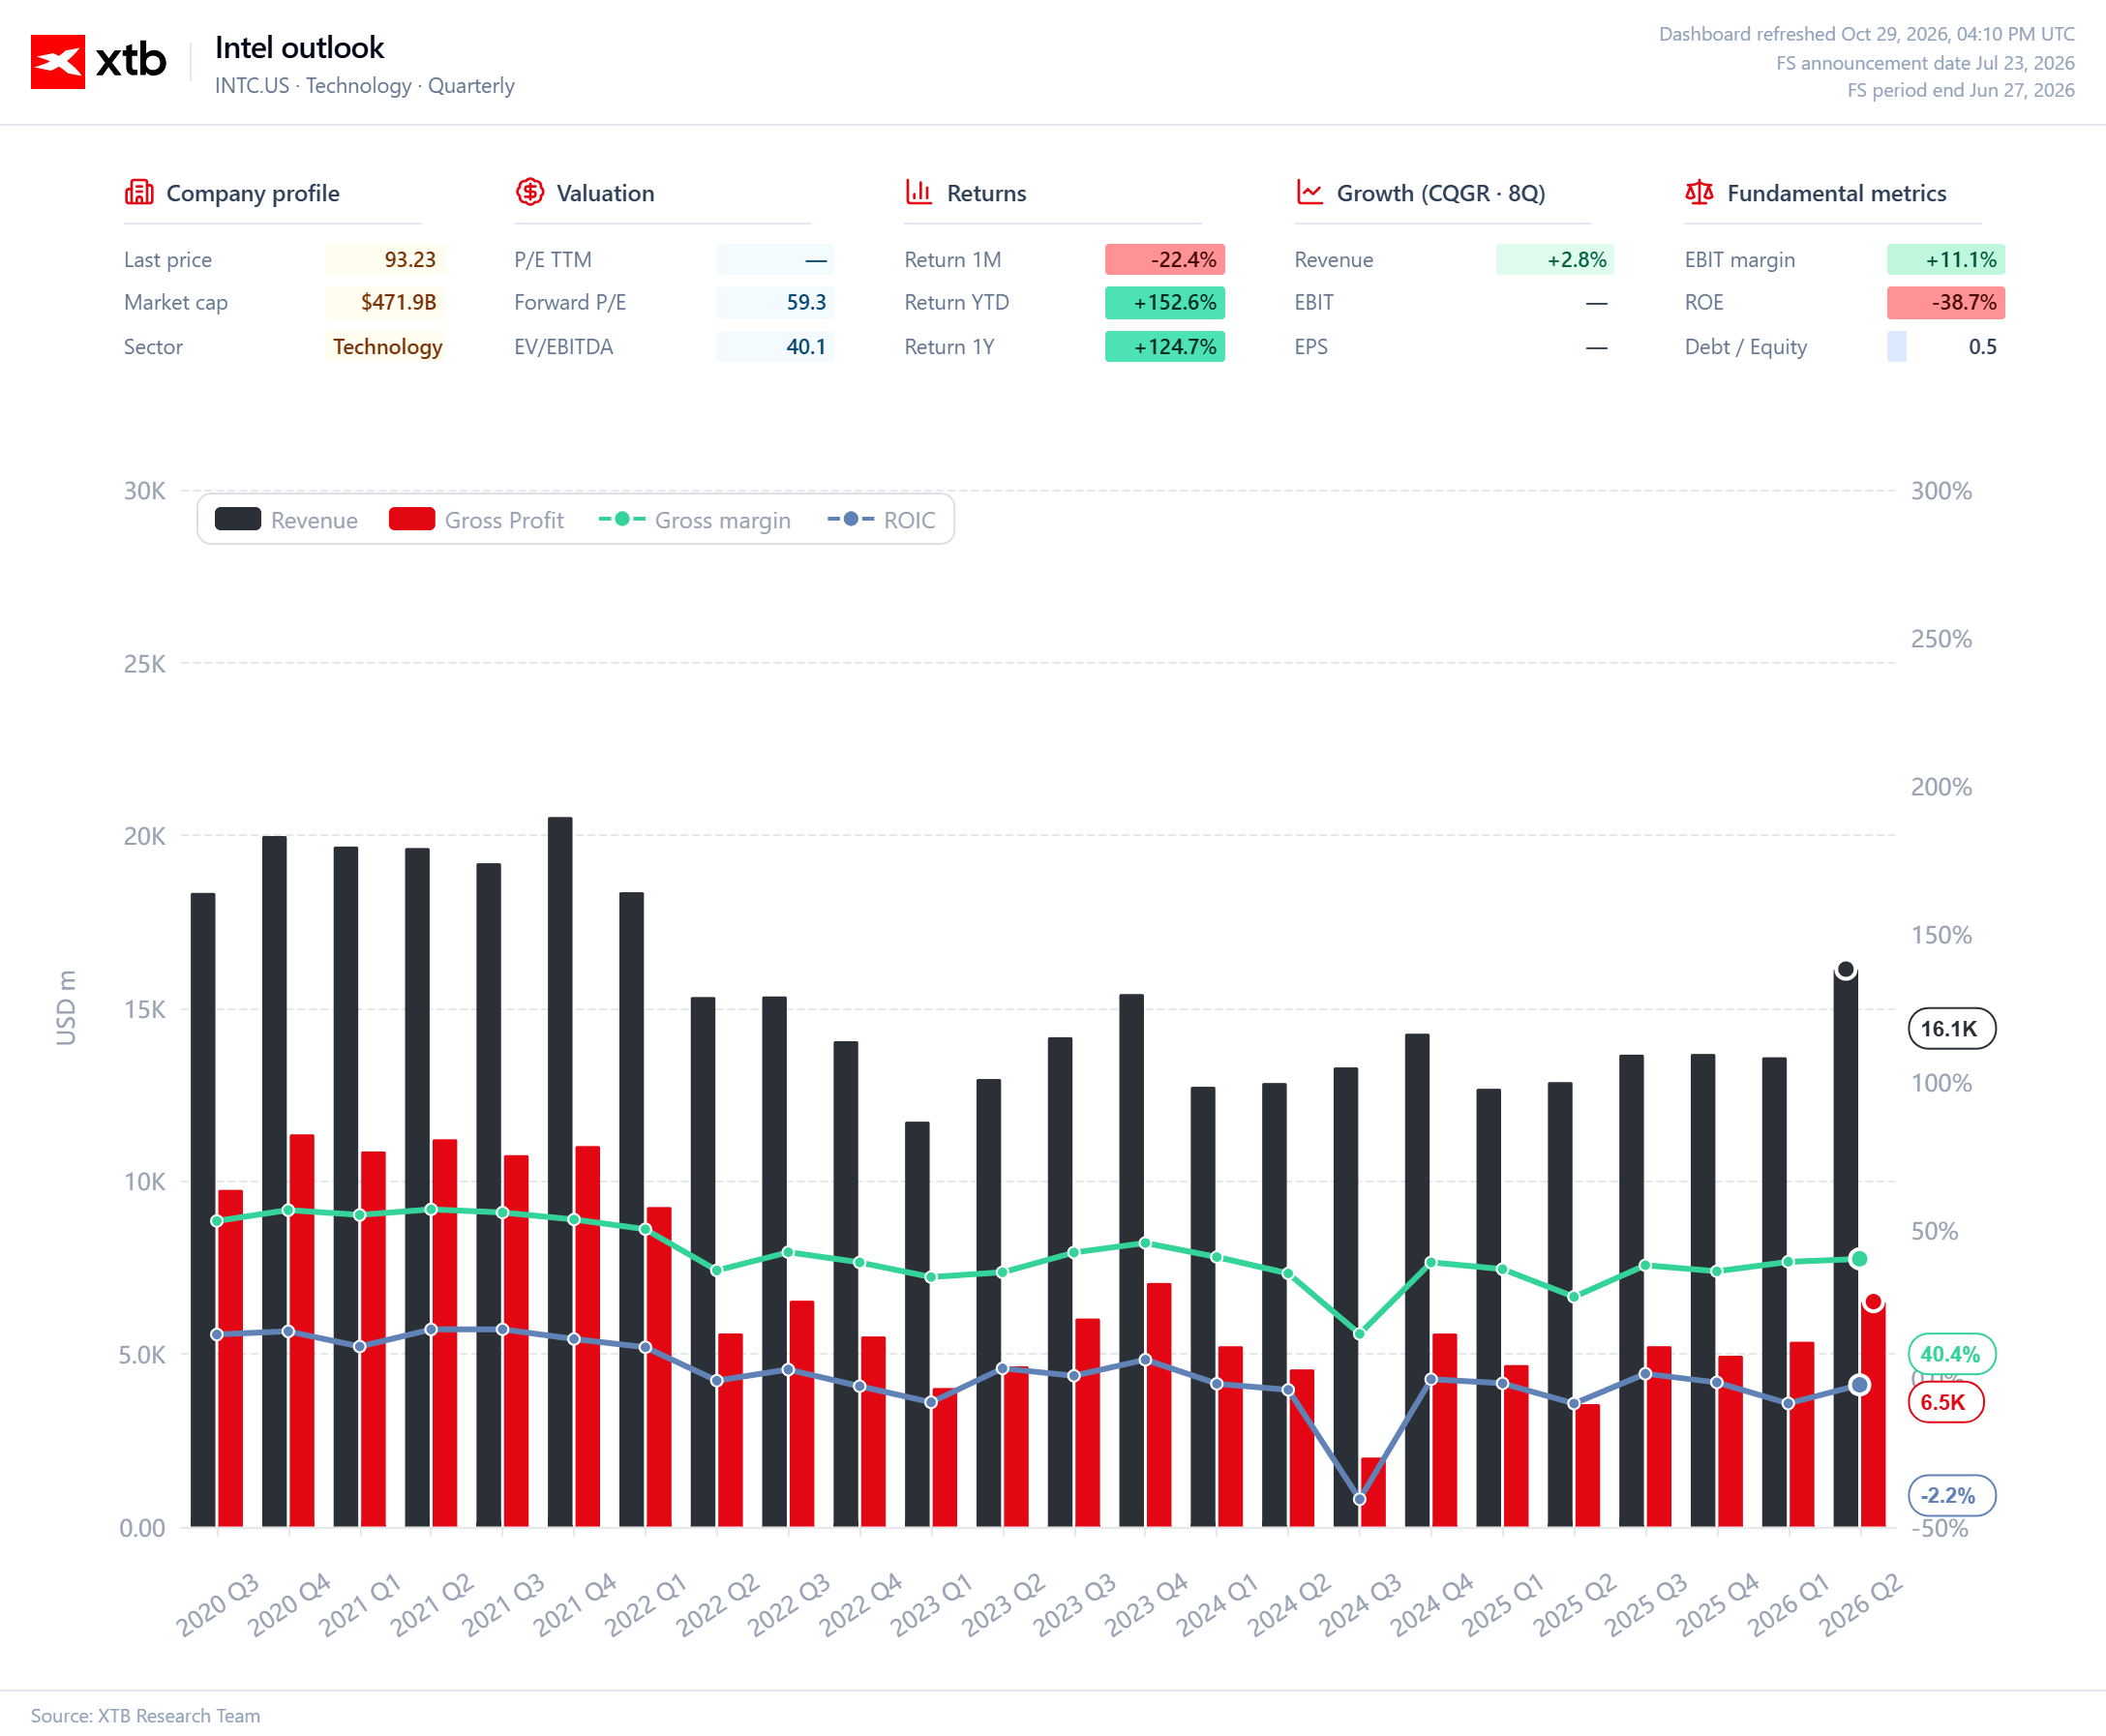
In the second quarter, Intel generated approximately $16.1 billion in revenue and adjusted EPS of $0.42. Consensus estimates for the third quarter therefore point to further year-over-year revenue growth, although earnings may not exceed the previous quarter’s level. Management’s assessment of conditions over the coming months and its confidence in further margin improvement will be important.
Server CPUs Are Becoming More Important
The growing use of AI tools, including agentic AI systems, is increasing demand for computing power on the server side. For Intel, this could translate into stronger demand for its Xeon processors and, amid constrained supply, more favorable pricing.
The key question is how much of this demand will translate into actual orders and shipments. If Intel cannot ramp up production quickly enough, it may be unable to fully capitalize on favorable market conditions. Investors will therefore be looking for updates on processor availability, order fulfillment, and demand prospects for the coming quarters.
Restructuring Remains a Drag on Results
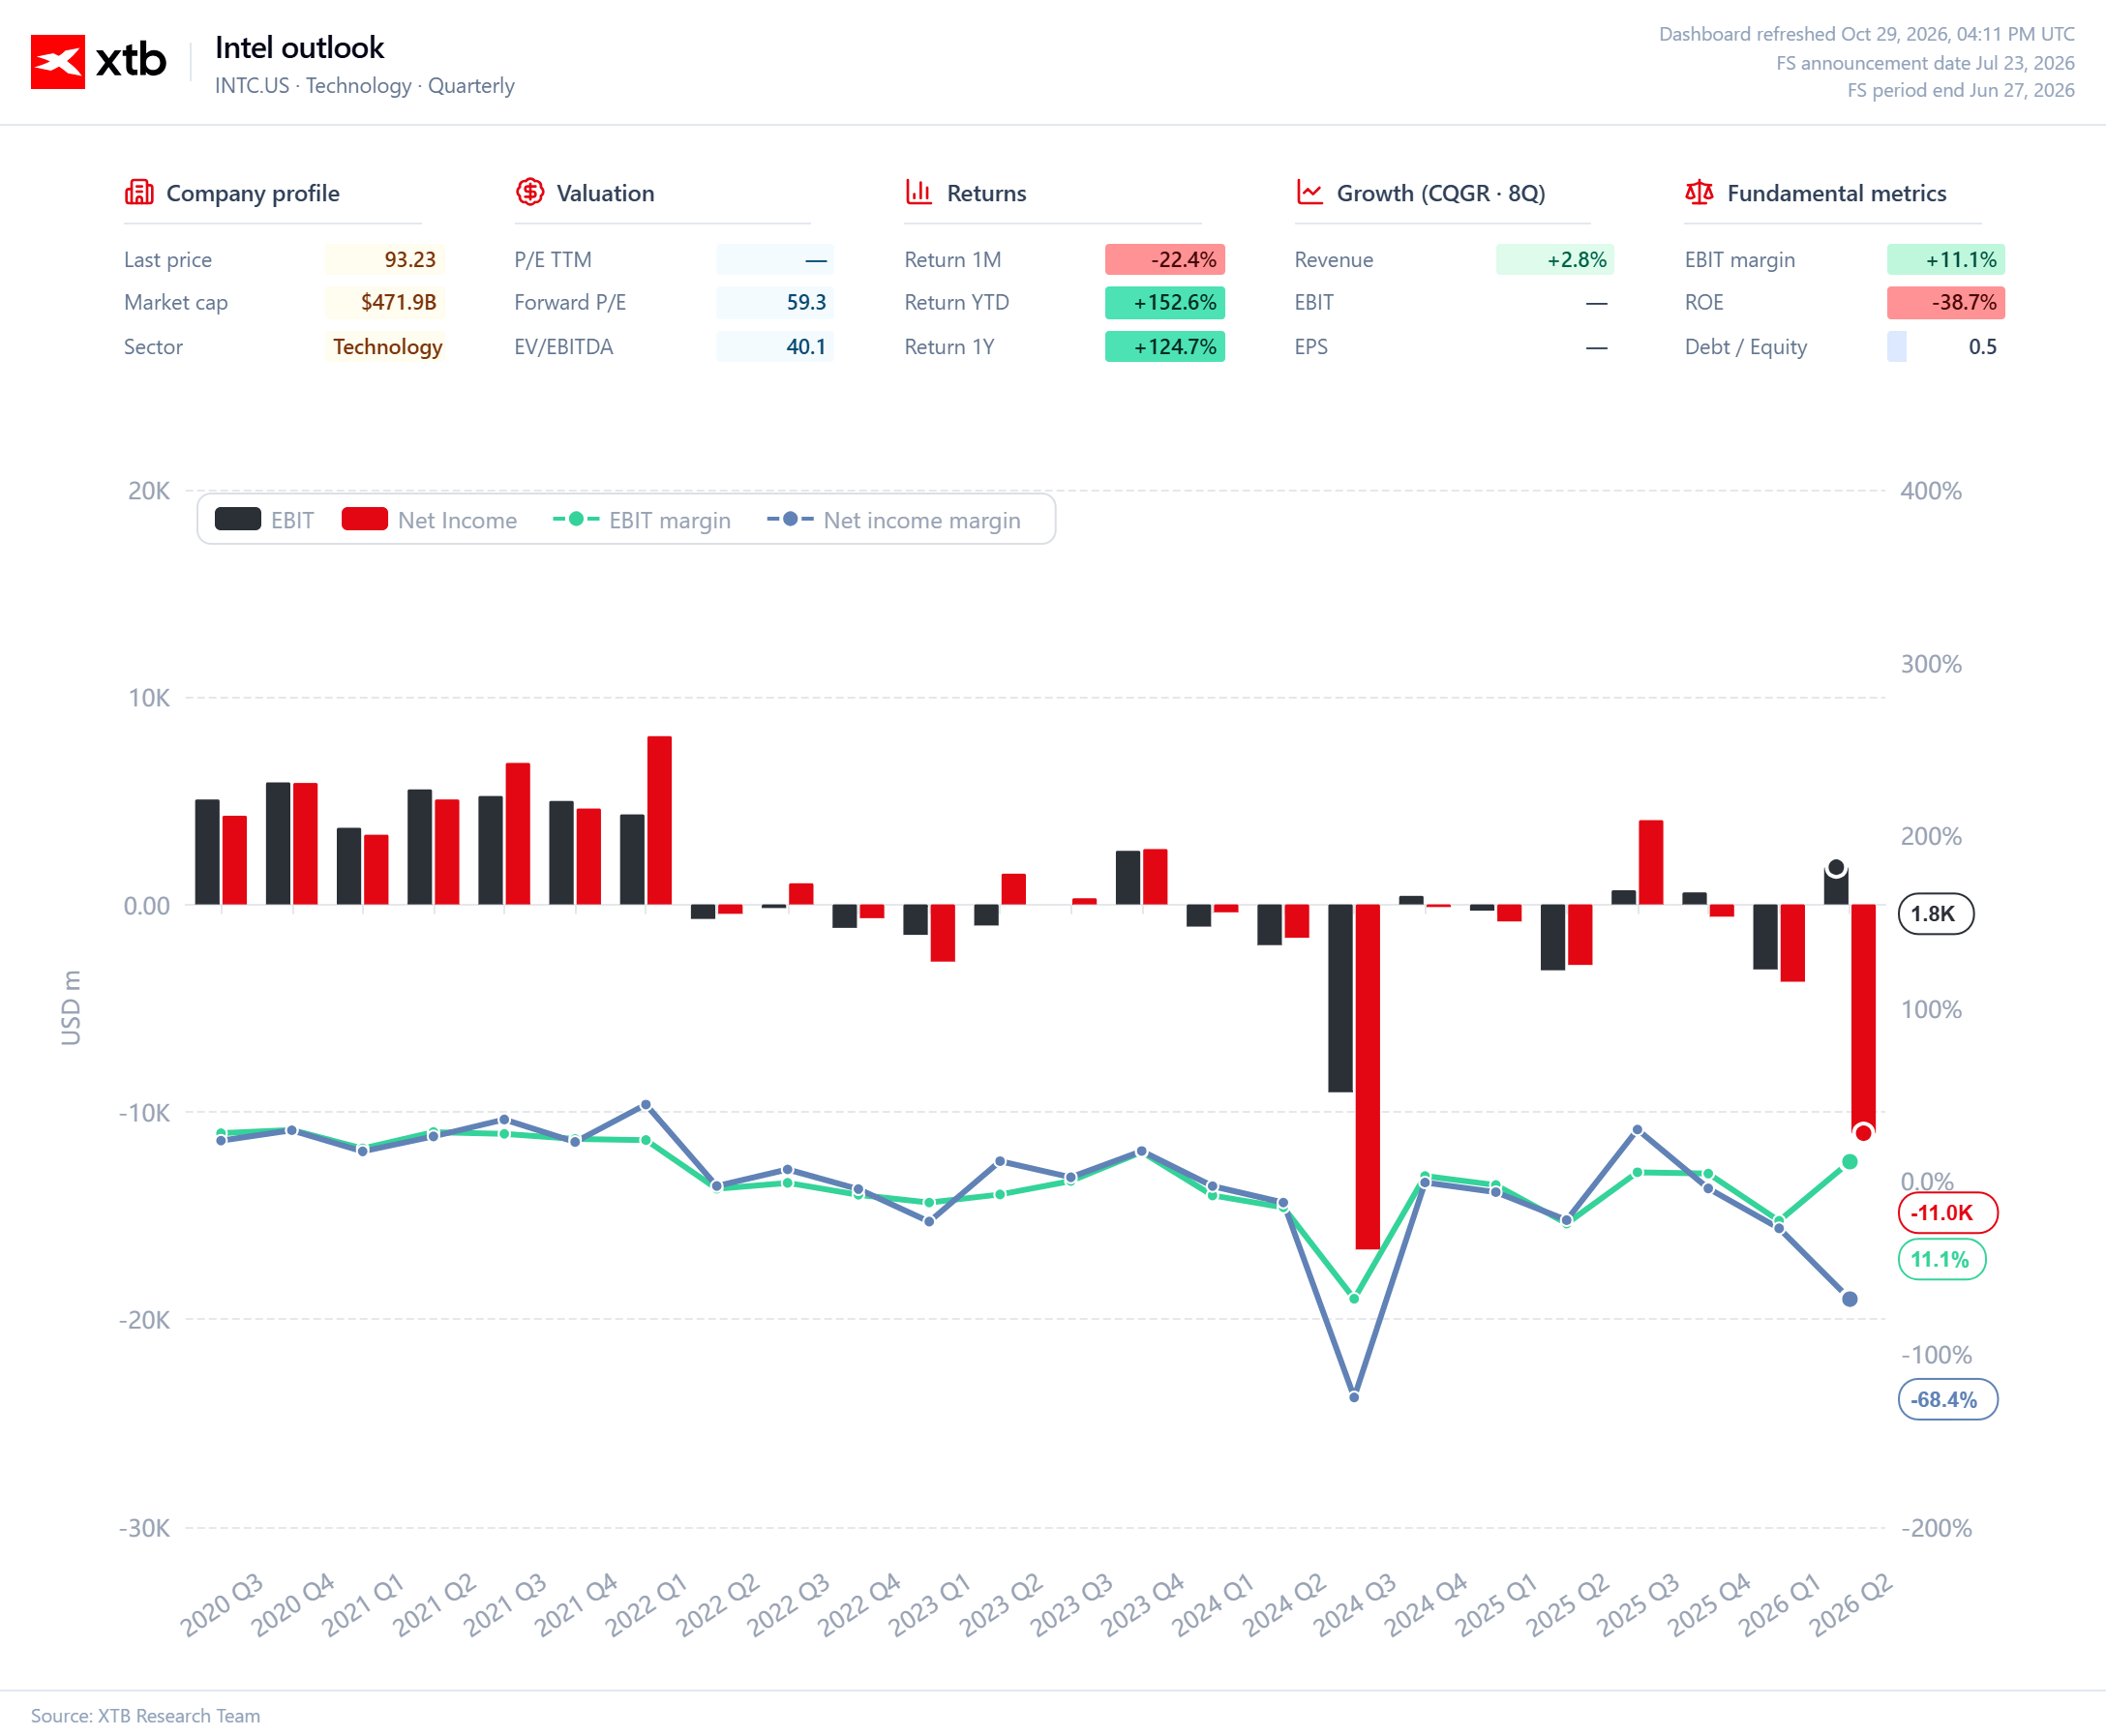
Another major issue is Intel’s ongoing business restructuring. The company is cutting costs and adjusting investment plans while continuing to develop its manufacturing operations and improve the competitiveness of its factories. The pace and scale of these changes will affect margins and cash flow.
The third-quarter results may show whether cost-cutting measures are beginning to pay off, but the plans for the coming months will be just as important. Investors need greater clarity on capital expenditure, restructuring costs, and the path toward sustainably higher profitability.
The PC Market Remains a Wild Card
Server processors could be a stronger part of Intel’s results, but the performance of its broader business still matters. PC demand, inventory levels, and pricing pressure could all affect revenue and margins. Investors will also assess whether strength in the server segment can offset potential weakness in the PC market.
Guidance Could Matter as Much as the Results
At the current share price, the market reaction may depend largely on the outlook for the fourth quarter and 2027. Strong historical results may not be enough if guidance disappoints or the company fails to provide convincing updates on processor availability and the pace of margin improvement.
Intel has an opportunity to benefit from rising demand for server CPUs, but the scale of those gains will depend on how many orders it can fulfill and at what margins. Cost reductions and disciplined capital spending remain equally important. These factors will help investors determine whether the current business recovery can develop into a more sustained improvement in performance.
Source: XTB Research


Amazon Preview: After Microsoft and Alphabet, the Market Won’t Forgive a Disappointment


ServiceNow Earnings: What Went Wrong?



US Open: Alphabet Sends Nasdaq Plunging. Strong US Data Fails to Rescue Wall Street

Microsoft earnings: Cloud growth overshadows CAPEX & FCF questions
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.