


European indices are continuing a cautious, choppy session today. This morning, the broad STOXX 600 gained around 0.3%, following three losing sessions and closing at three-week lows. However, by now it has completely given back those gains. Currently, Germany's DAX is posting a marginal gain (approx. 0.1%), the Euro Stoxx 50 is up around 0.3%, and Milan's FTSE MIB is rising by about 0.6%, supported by banks. France's CAC 40 is flat, while London's FTSE 100 (approx. -0.4%) and Spain's IBEX (approx. -0.3%) are in the red.
Today's rebound in tech markets is primarily driven by the debut of Anthropic. The company priced its offering at USD 83 per share, above the initial range of USD 70–78, and raised approximately USD 81 billion, making it the largest IPO in history. Its market valuation reaches around USD 1.5 trillion. The shares, trading under the ticker ANT, are set to debut on the Nasdaq after the US market open. According to grey market data, they could open more than 20% above the issue price.
Investors breathed a sigh of relief, as the Nasdaq had lost around 4% in November on concerns over returns from massive capital expenditures on AI infrastructure. Ahead of the open, US100 futures are up over 2%, S&P 500 futures are gaining nearly 1.2%, and Dow Jones futures are rising by about 0.7%. The success of the offering acts as a test of risk appetite in a sector that has faced the heaviest pressure in recent weeks.
The macro backdrop, however, remains challenging. The minutes from the October Fed meeting, released last night, confirmed a hawkish stance. Nearly all participants agreed that further rate hikes in the coming months would be appropriate, and several left the door open for a larger move in December. Nearly all also pointed to disappointing returns on AI investments as a risk to financial stability. This is why today's IPO is also significant for the Fed.
The rhetoric from individual members is even sharper. Waller stated that the Fed will have to "shock" the market with a 50 bps hike, with the alternative being 25 bps accompanied by a signal of another move in January. The market is pricing in roughly a 90% probability of a 25 bps hike in December and around 10% for 50 bps. The consequences are clear. The dollar is at its strongest in 19 months (DXY around 104), 10-year yields remain above 5.1%, and more expensive capital is weighing on gold, industrial metals, and richly valued growth stocks.
Initial jobless claims came in at 203k (forecast 198k), still low, though slightly above expectations. Continuing claims rose by 70k to 1.763 million (forecast 1.703 million). This signals that layoffs remain low, but finding a new job is taking longer. Additionally, the Philadelphia Fed index fell to 6.3 pts (forecast 20.1 pts), while the prices paid sub-index jumped to 58.2 pts from 43.2 pts. Weaker activity paired with rising costs is an uncomfortable mix for the Fed.
FX Market
Chart 1 present moves of major currencies against USD today
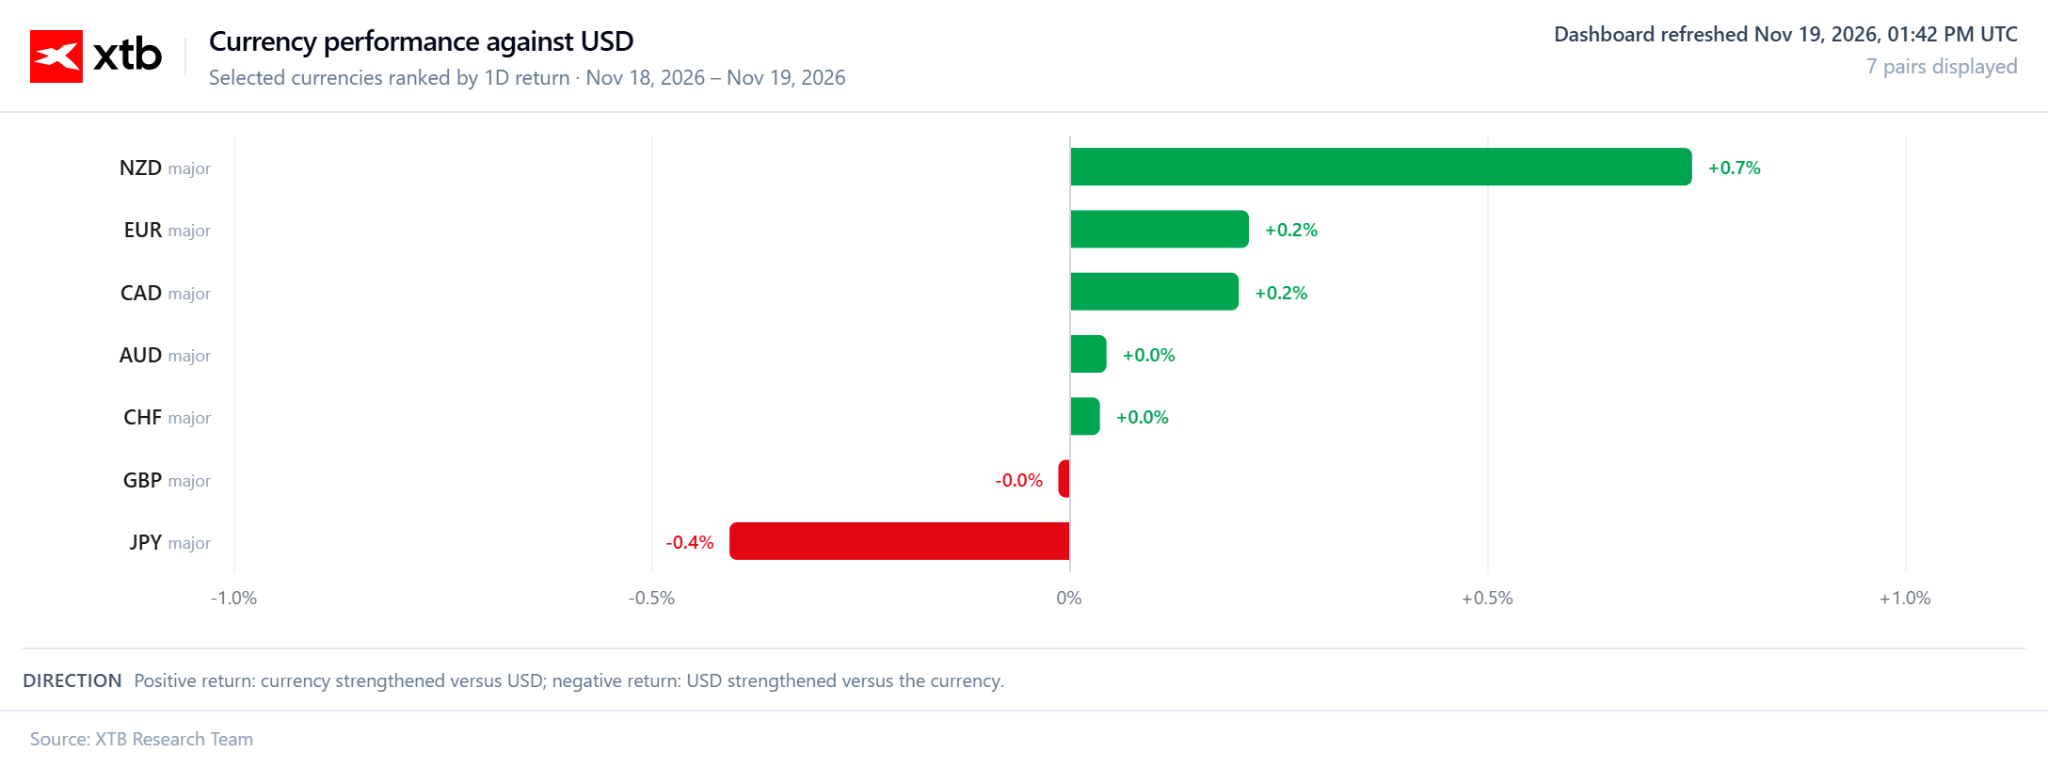
- NZDUSD: The New Zealand dollar is gaining around 0.7% against the US dollar and is today's clear leader. However, this is a bounce within a downtrend rather than a change in direction. The pair had fallen for six consecutive sessions, reaching its lowest levels since March 2020.
- EURUSD: The euro remains near its lowest levels since April 2025 (around 1.099) as the dollar gains on December rate hike expectations. Today, the pair is rebounding by 0.2%.
- USDJPY: The dollar is gaining against the yen (approx. 0.4%), with the rate approaching 160. For the market, this is a level that could trigger another intervention by Japan.
Commodity Market
- Gold: Following yesterday's sell-off of around 3%, which pushed the metal to 14-month lows, gold is edging slightly lower today (approx. 0.2%, to around USD 3,720 per ounce). A strong dollar and rate hike expectations are outweighing geopolitical risks, and even tensions around Iran are failing to support bullion prices this time. Silver is down around 0.3%.
- Copper: Losing another ~0.6% after yesterday's sharp sell-off. The metal remains under pressure from a strong dollar, expectations of higher interest rates, and doubts regarding AI data center spending.
- Oil: Brent is gaining nearly 2%, and WTI is up around 1%. Reports by "The New York Times" that Donald Trump is considering further strikes on Iran halted the declines, though the scale of the rebound is limited. The market is weighed down by IEA supply surplus forecasts, a build in US inventories of over 3 million barrels, and the return of flows through the Strait of Hormuz to pre-war levels. Brent is already nearly 20% lower than at the beginning of November.
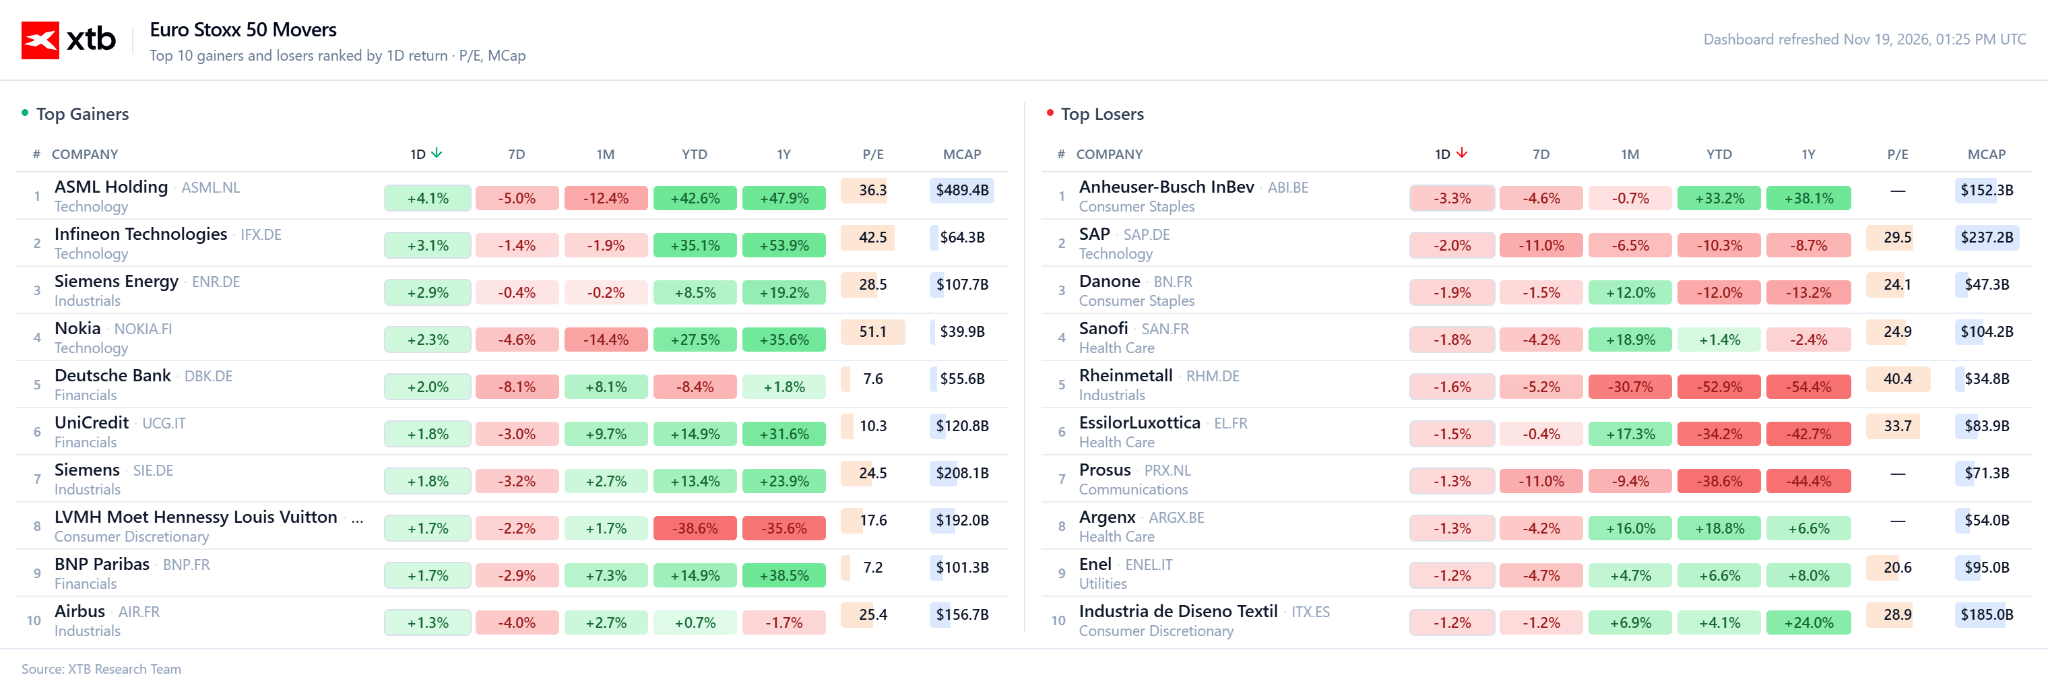
Chart 2 presents the biggest price changes among companies included in the Euro Stoxx 50 index.
Company News
Top Gainers:
- ASML (ASML.NL), Infineon (IFX.DE), Siemens Energy (ENR.DE), Nokia (NOKIA.FI): Companies linked to AI infrastructure are gaining following the successful Anthropic IPO pricing, which eased concerns about the profitability of investments in the sector (ASML up approx. 4.6%, Infineon approx. 3.7%, Siemens Energy approx. 3%, Nokia approx. 2.2%).
- UniCredit (UCG.IT): The bank is rising on reports of an agreement with the German government regarding the takeover of Commerzbank. The combined institution is set to keep its headquarters in Frankfurt and remain publicly listed, while Berlin dropped its demand for two seats on the supervisory board (up approx. 2.2%).
Top Losers:
- AB InBev (ABI.BR): The share price is mechanically weighed down by going ex-dividend (EUR 0.40 per share), and the company is also losing ground amid a broader sell-off in defensive consumer staples stocks (down around 3%).
- SAP (SAP.DE): The stock remains under pressure for the third consecutive day, following a sell-off in the software sector, profit-taking, and higher bond yields. The company has not released any new negative news (down approx. 2.7%).
- Rheinmetall (RHM.DE): Shares of the defense manufacturer remain under pressure following November's downward revision of sales forecasts (down approx. 1.7%).


Palo Alto Earnings: Another Record Riding the Cybersecurity Crisis Wave



Morning Wrap: Time for the largest stock market debut in history (19.11.2026)



🔴US500 decrease ahead of FOMC minutes

US OPEN: Nvidia Isn’t Enough as Wall Street Slips Back Into the Red
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.