


We enter the week on most global stock exchanges with modest gains, despite further escalation in the Middle East. Investors did not overreact to the attacks on Saudi Arabia, focusing instead on the "energy truce" between Russia and Ukraine announced by Donald Trump, as well as subsequent reports of increased transport volumes through the strait.
S&P 500 futures are up 0.3%, as are Nasdaq 100 futures. Sentiment in Asia is slightly more mixed, with South Korea's KOSPI falling by over 3%. Attention is also drawn to the Indian rupee, which gained the most in six months following an intervention by the Reserve Bank of India. In focus this week will be Wednesday's US September CPI inflation reading, a speech by Fed Chair Kevin Warsh, and the start of the third-quarter earnings season.
🛢️ Energy Commodities and Geopolitics
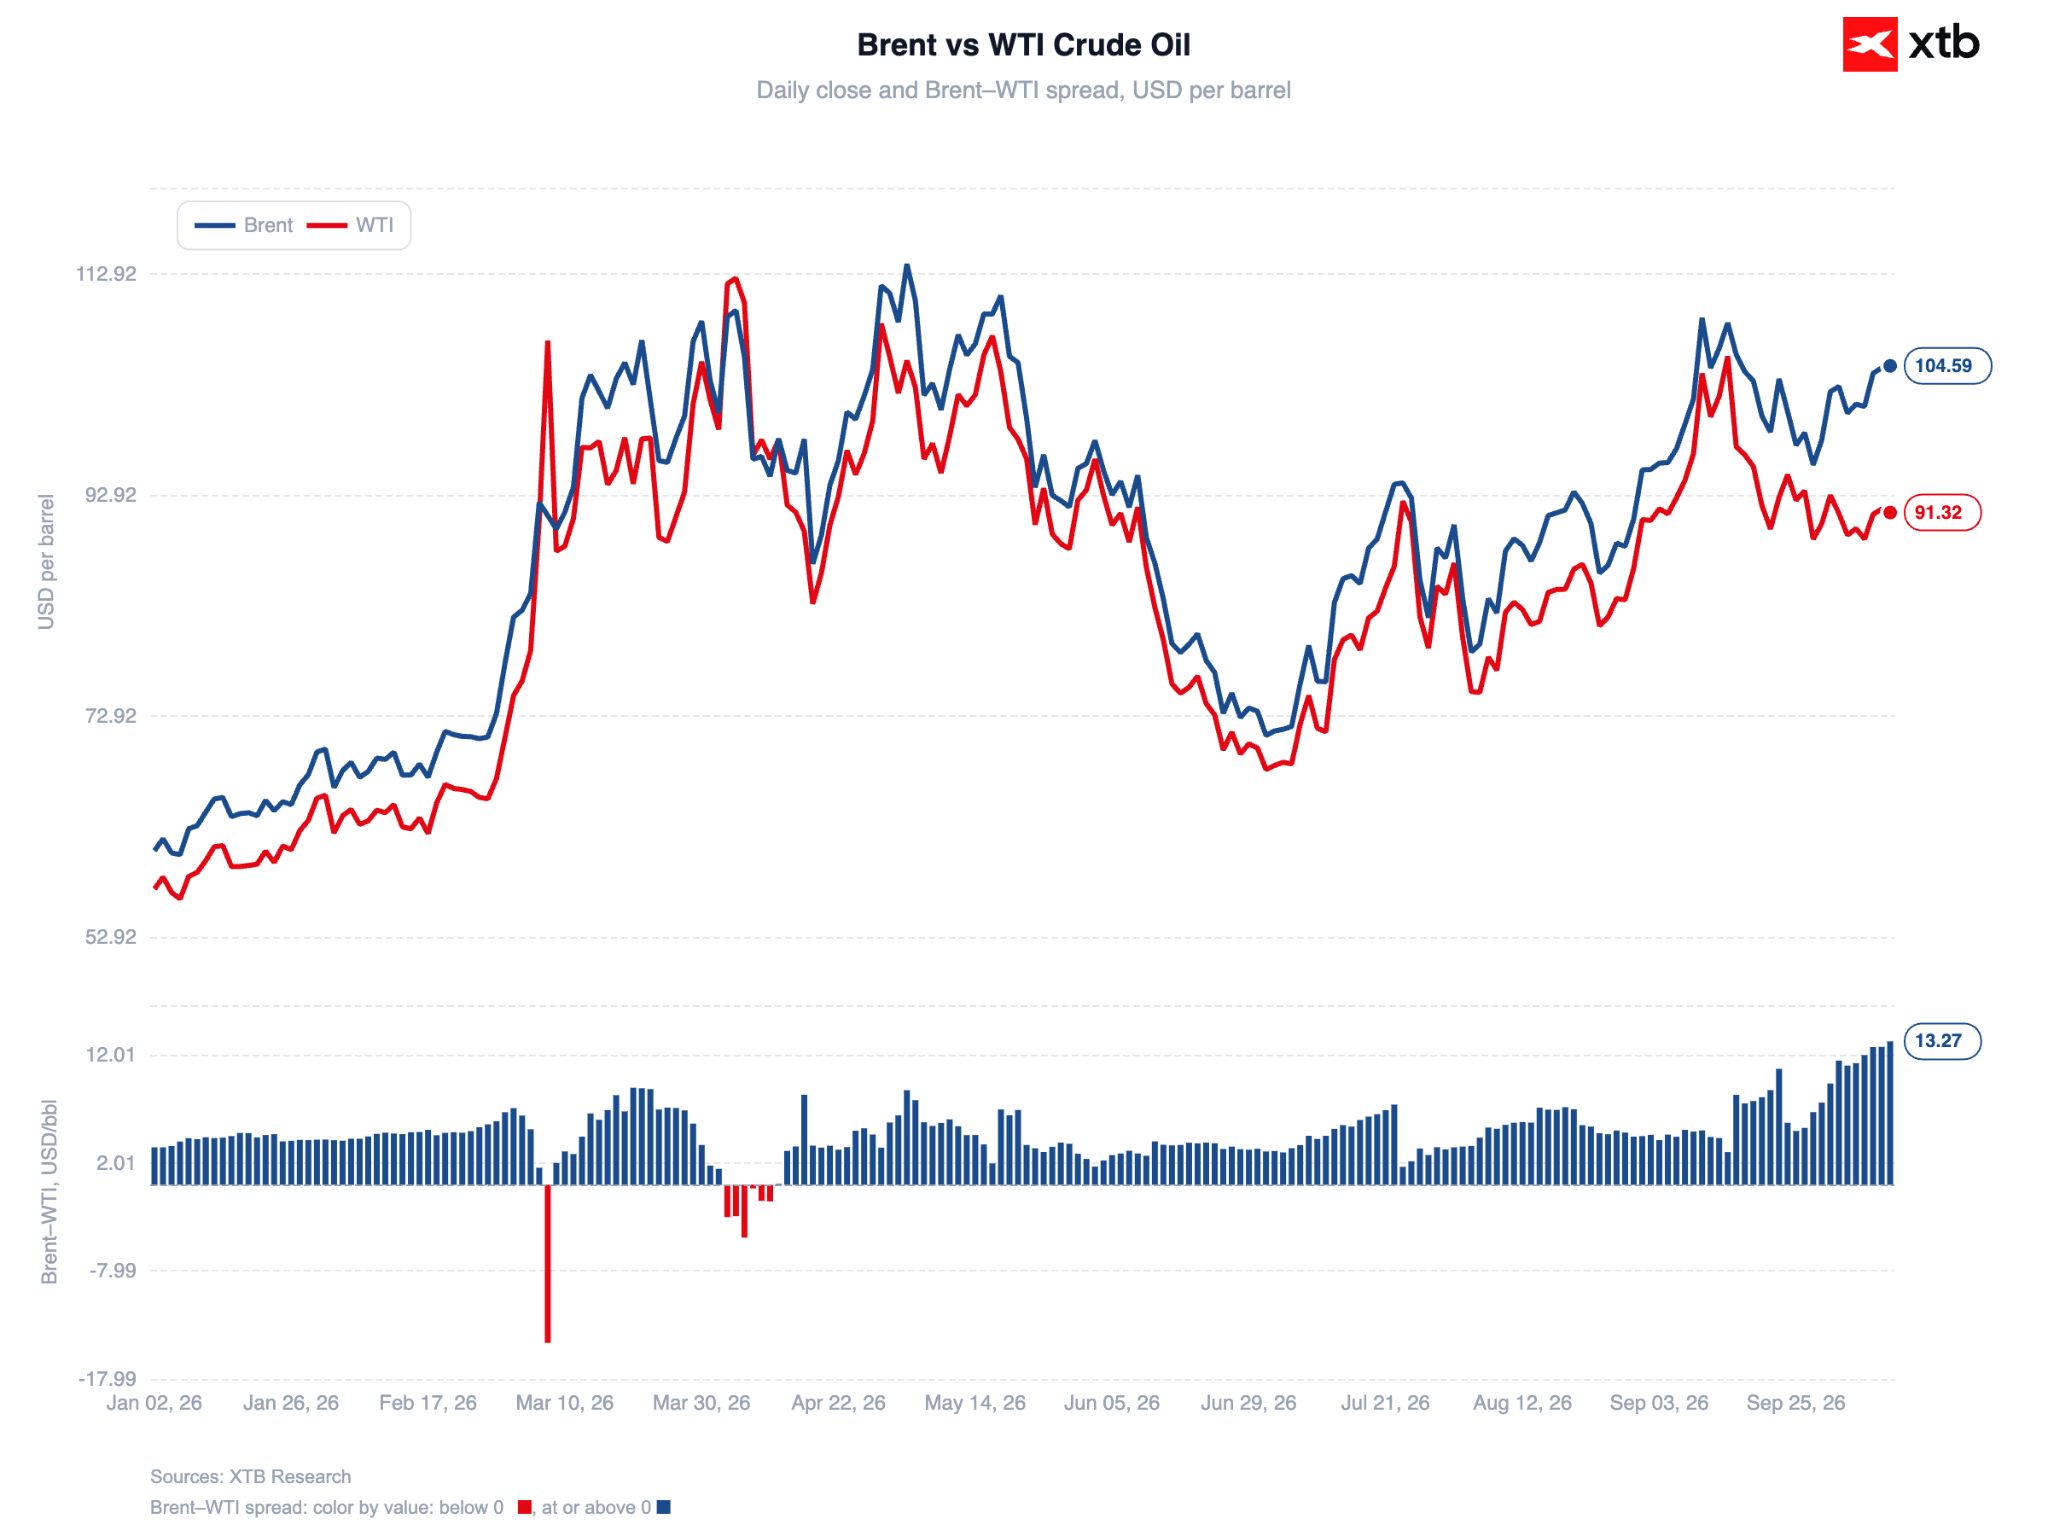
Brent crude is down 0.78%, hovering around 104 dollars per barrel. WTI is declining 1.2% to approximately 91 USD.
Figure 1: Brent and WTI Crude Oil (2026)
 Source: XTB Research, 12.10.2026
Overnight from Saturday to Sunday, Yemeni Houthis once again targeted the main airport in Riyadh, a day after an earlier strike on the same facility killed 12 people. Another tanker was also attacked in the Strait of Hormuz. Despite the escalation, crude exports from the Persian Gulf remain close to pre-war levels; according to JPMorgan, they reach 17.5 million barrels per day, representing 98% of the pre-conflict volume. It is worth noting that recent attacks have not targeted energy infrastructure.
The market is also cautiously pricing in Sunday's announcement by Trump, who wrote on the social media platform Truth Social that Russia and Ukraine agreed an "energy truce" with immediate effect, adding: "Do not break it!". This marks Trump's second such statement in a month, with the previous one described by Volodymyr Zelenskyy as unfinalised. This time, the Ukrainian side is awaiting details.
In the background remains Trump's plan, criticised across party lines in the US, to release Russian diesel onto the market in cooperation with Vladimir Putin. Moscow announced the shipment of 500,000 tonnes following the partial lifting of an export ban, representing a fraction of the 28.6 million tonnes exported during the whole of last year (Kpler data).
📈 Equities
In Asia, the session is proceeding without a clear direction. South Korea's Kospi is losing the most (-3.3%, to around 6,400 pts), reflecting a delayed reaction by local tech companies to the earlier global semiconductor sell-off upon returning from a long weekend. The Shanghai Composite is down 0.26%, the Hang Seng is up 0.1%, and Australia's S&P/ASX 200 is gaining 0.8%. The Japanese market is closed for Sports Day.
Futures in Europe and the US point to muted optimism: S&P 500 futures gain 0.3%, and the DAX is up as much as 0.5%. Sentiment is supported by cheaper crude oil, as lower energy costs ease margin pressure and inflation fears.
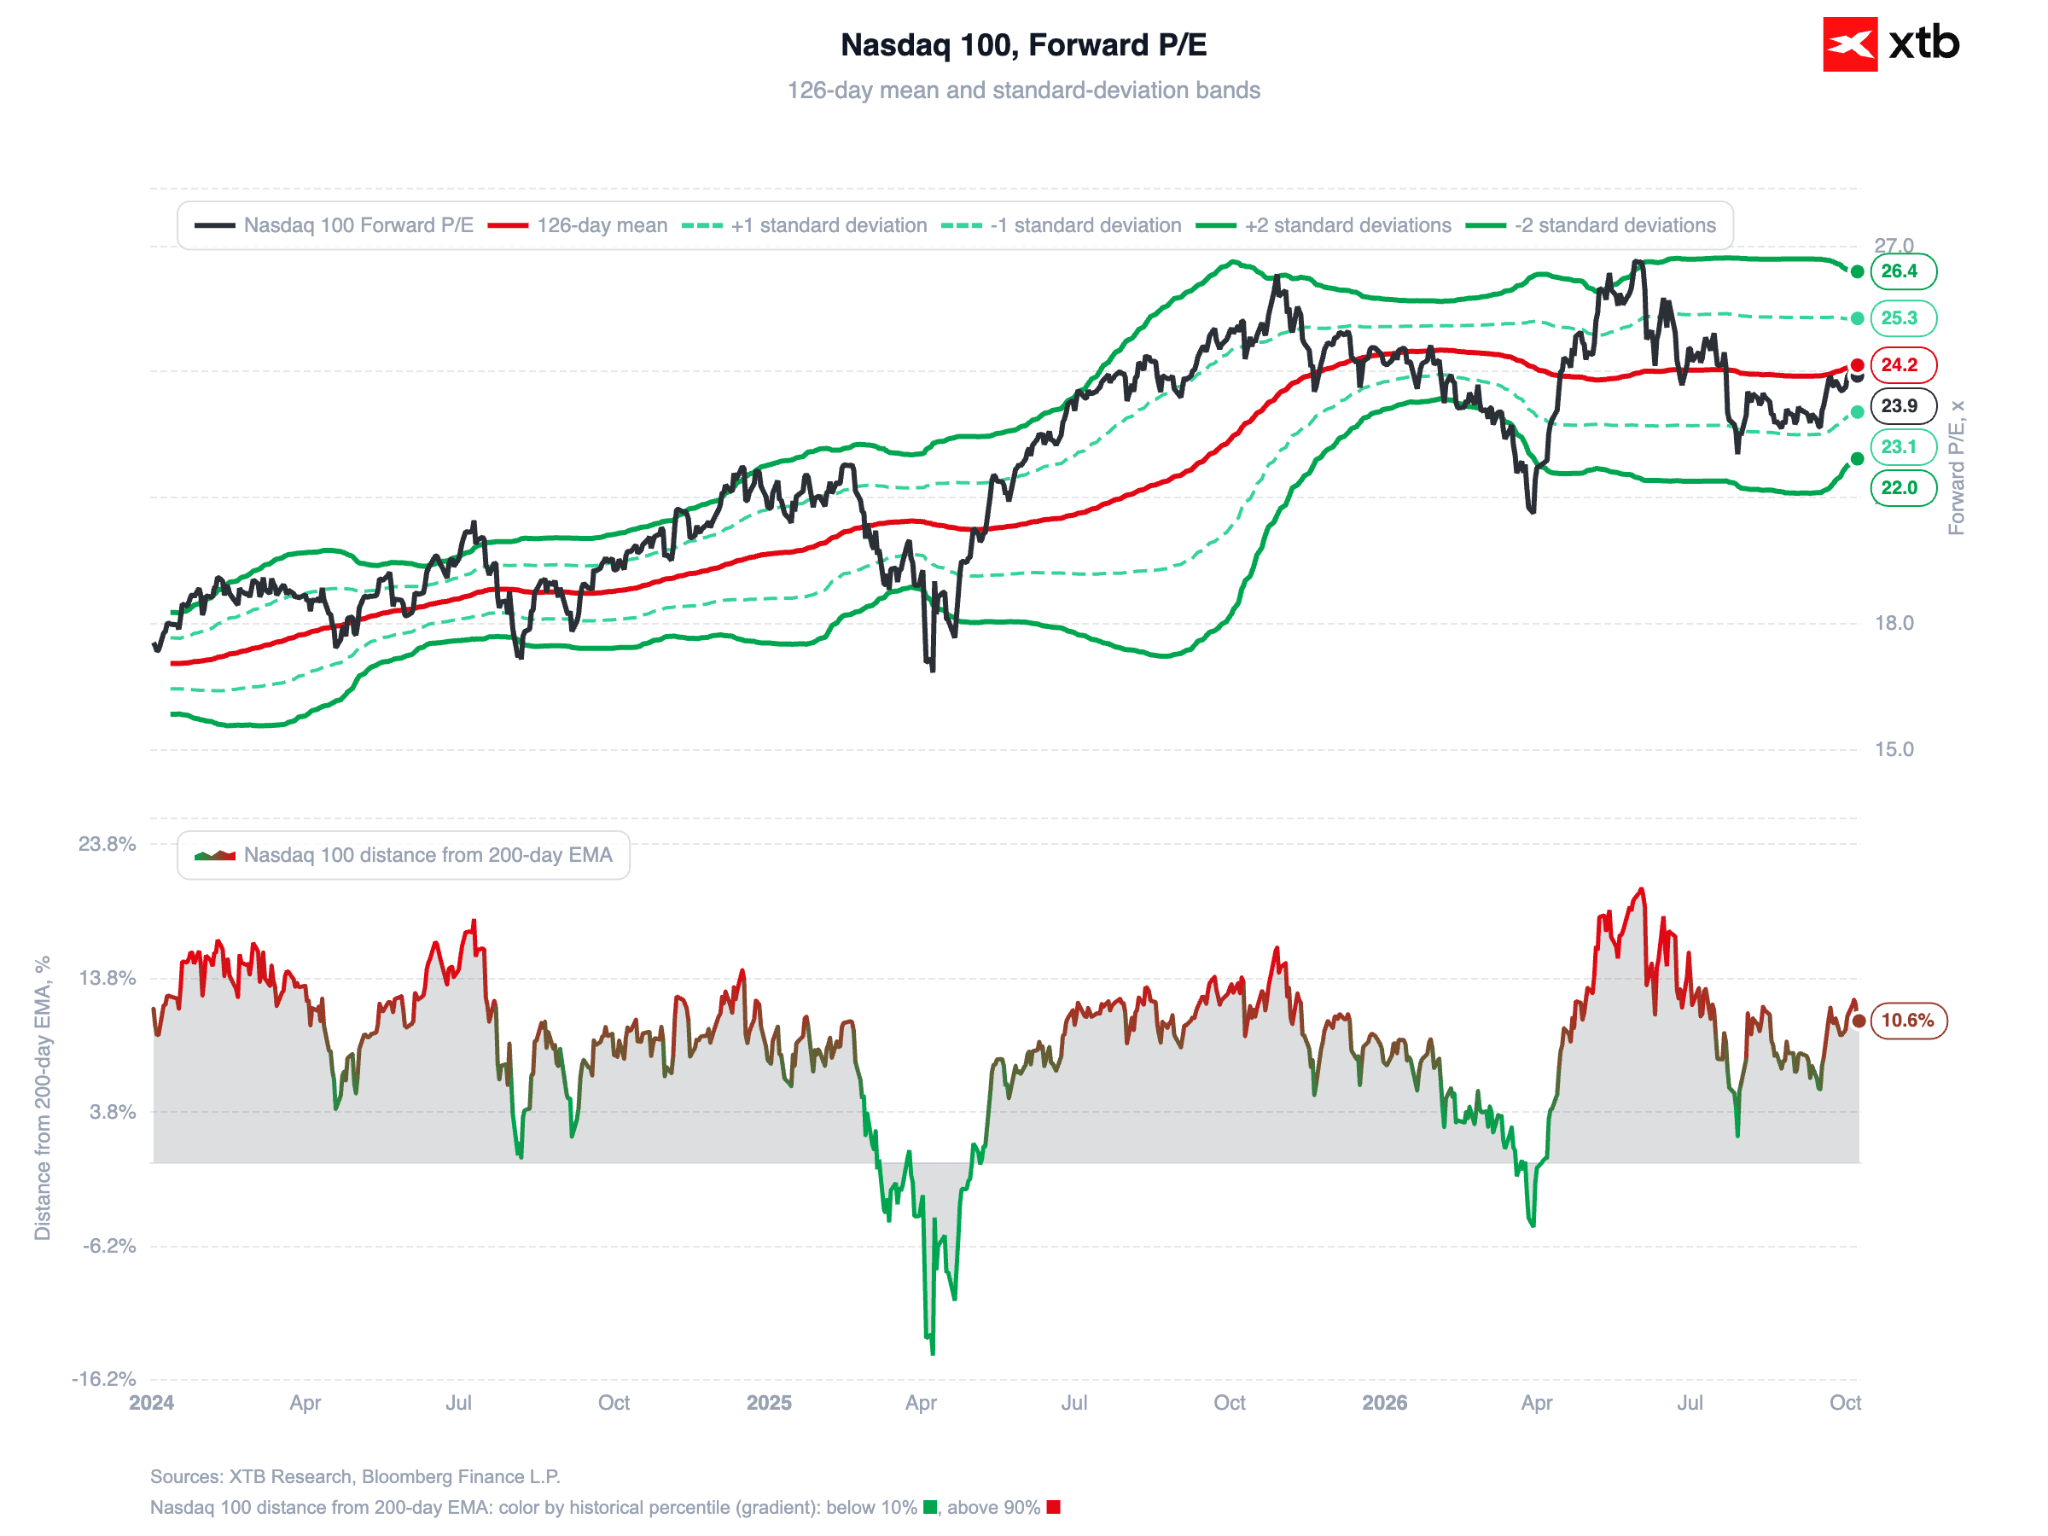
It is worth remembering that earnings season kicks off in earnest this week. Investors will closely monitor the growing divergence between large-cap technology companies and the rest of the market. The Russell 2000 ended last week lower and stands nearly 10% below its August highs. The S&P 500 and Nasdaq 100 remain close to all-time highs. Attention is focused on both the AI revolution and rising energy prices, which are leaving a particularly heavy mark on the industrial sector.
Figure 2: Nasdaq 100 Forward P/E (2024 - 2026)
 Source: XTB Research, 12.10.2026
Regarding corporate news: Amazon is negotiating the acquisition of startup Decart AI for approximately 7 billion dollars, while Nvidia is in talks to increase its investment in Reflection AI or provide it with computing power.
💱 Currencies
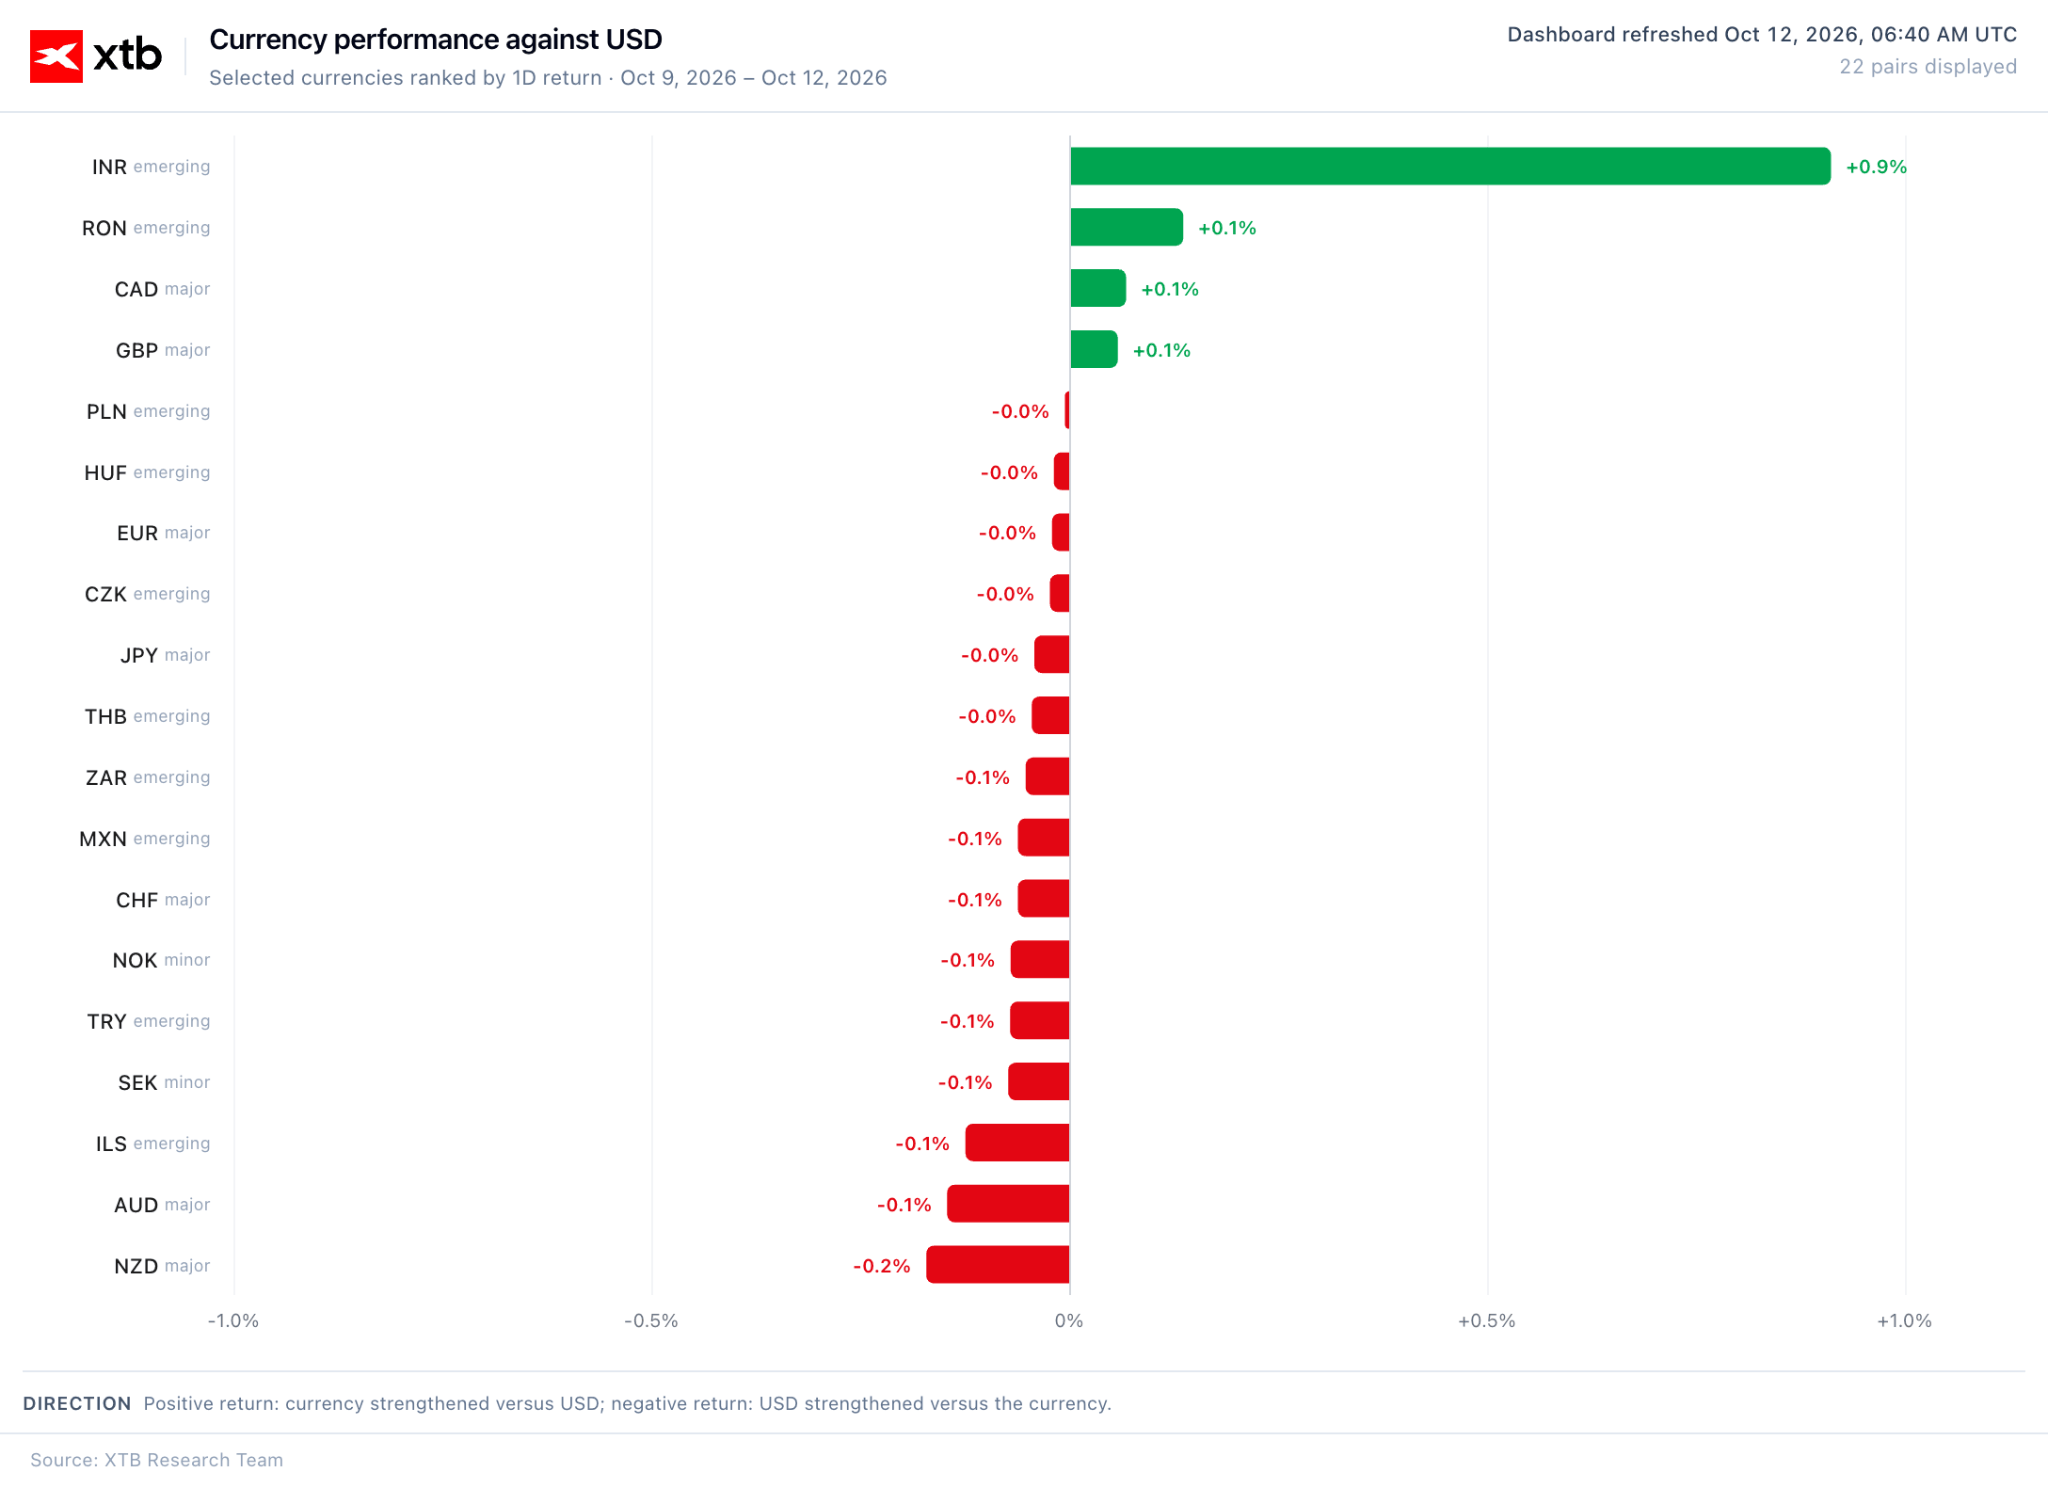
The Indian rupee is performing best among major currencies today, gaining around 1% against the dollar (its strongest single-day appreciation since April). The USD/INR pair fell below 95.8.
What lies behind this movement?
The Reserve Bank of India announced on Saturday the introduction of a special dollar window for state-run oil companies and a new reserve requirement for certain FX derivative transactions. It also intervened directly in the spot market. Yields on 10-year Indian government bonds rose by 9 bps to 7.39%, the highest since October 2023.
However, pressure on the rupee continues to be maintained by high oil prices and a widening trade deficit.
Movements across G10 currencies are far more muted. EUR/USD is trading around 1.12, GBP/USD is slightly above 1.32, and USD/JPY is hovering just above 158. The Polish zloty remains stable, with EUR/PLN staying below 4.39.
Figure 3: G10 and EM Currency Performance vs. USD (12.10.2026)
 Source: XTB Research, 12.10.2026
📈 Macroeconomic Data and Monetary Policy
The bond market has been doing part of central banks' work for weeks. Global yields have climbed to multi-year highs, which in itself tightens financial conditions and limits the need for further rate hikes. Market expectations for interest rate increases have fallen dynamically, most notably in Australia and the eurozone (the latter driven by concerns over the French debt crisis).
In focus this week will be Wednesday's US September CPI reading and a speech on Thursday by Fed Chair Kevin Warsh at the IMF annual meeting in Bangkok, where Governor Christopher Waller and Cleveland Fed President Beth Hammack are also scheduled to speak. A stronger-than-expected inflation reading could trigger another sell-off in the debt market, increasing pressure on the Fed to tighten monetary policy more aggressively.
🪙 Precious Metals
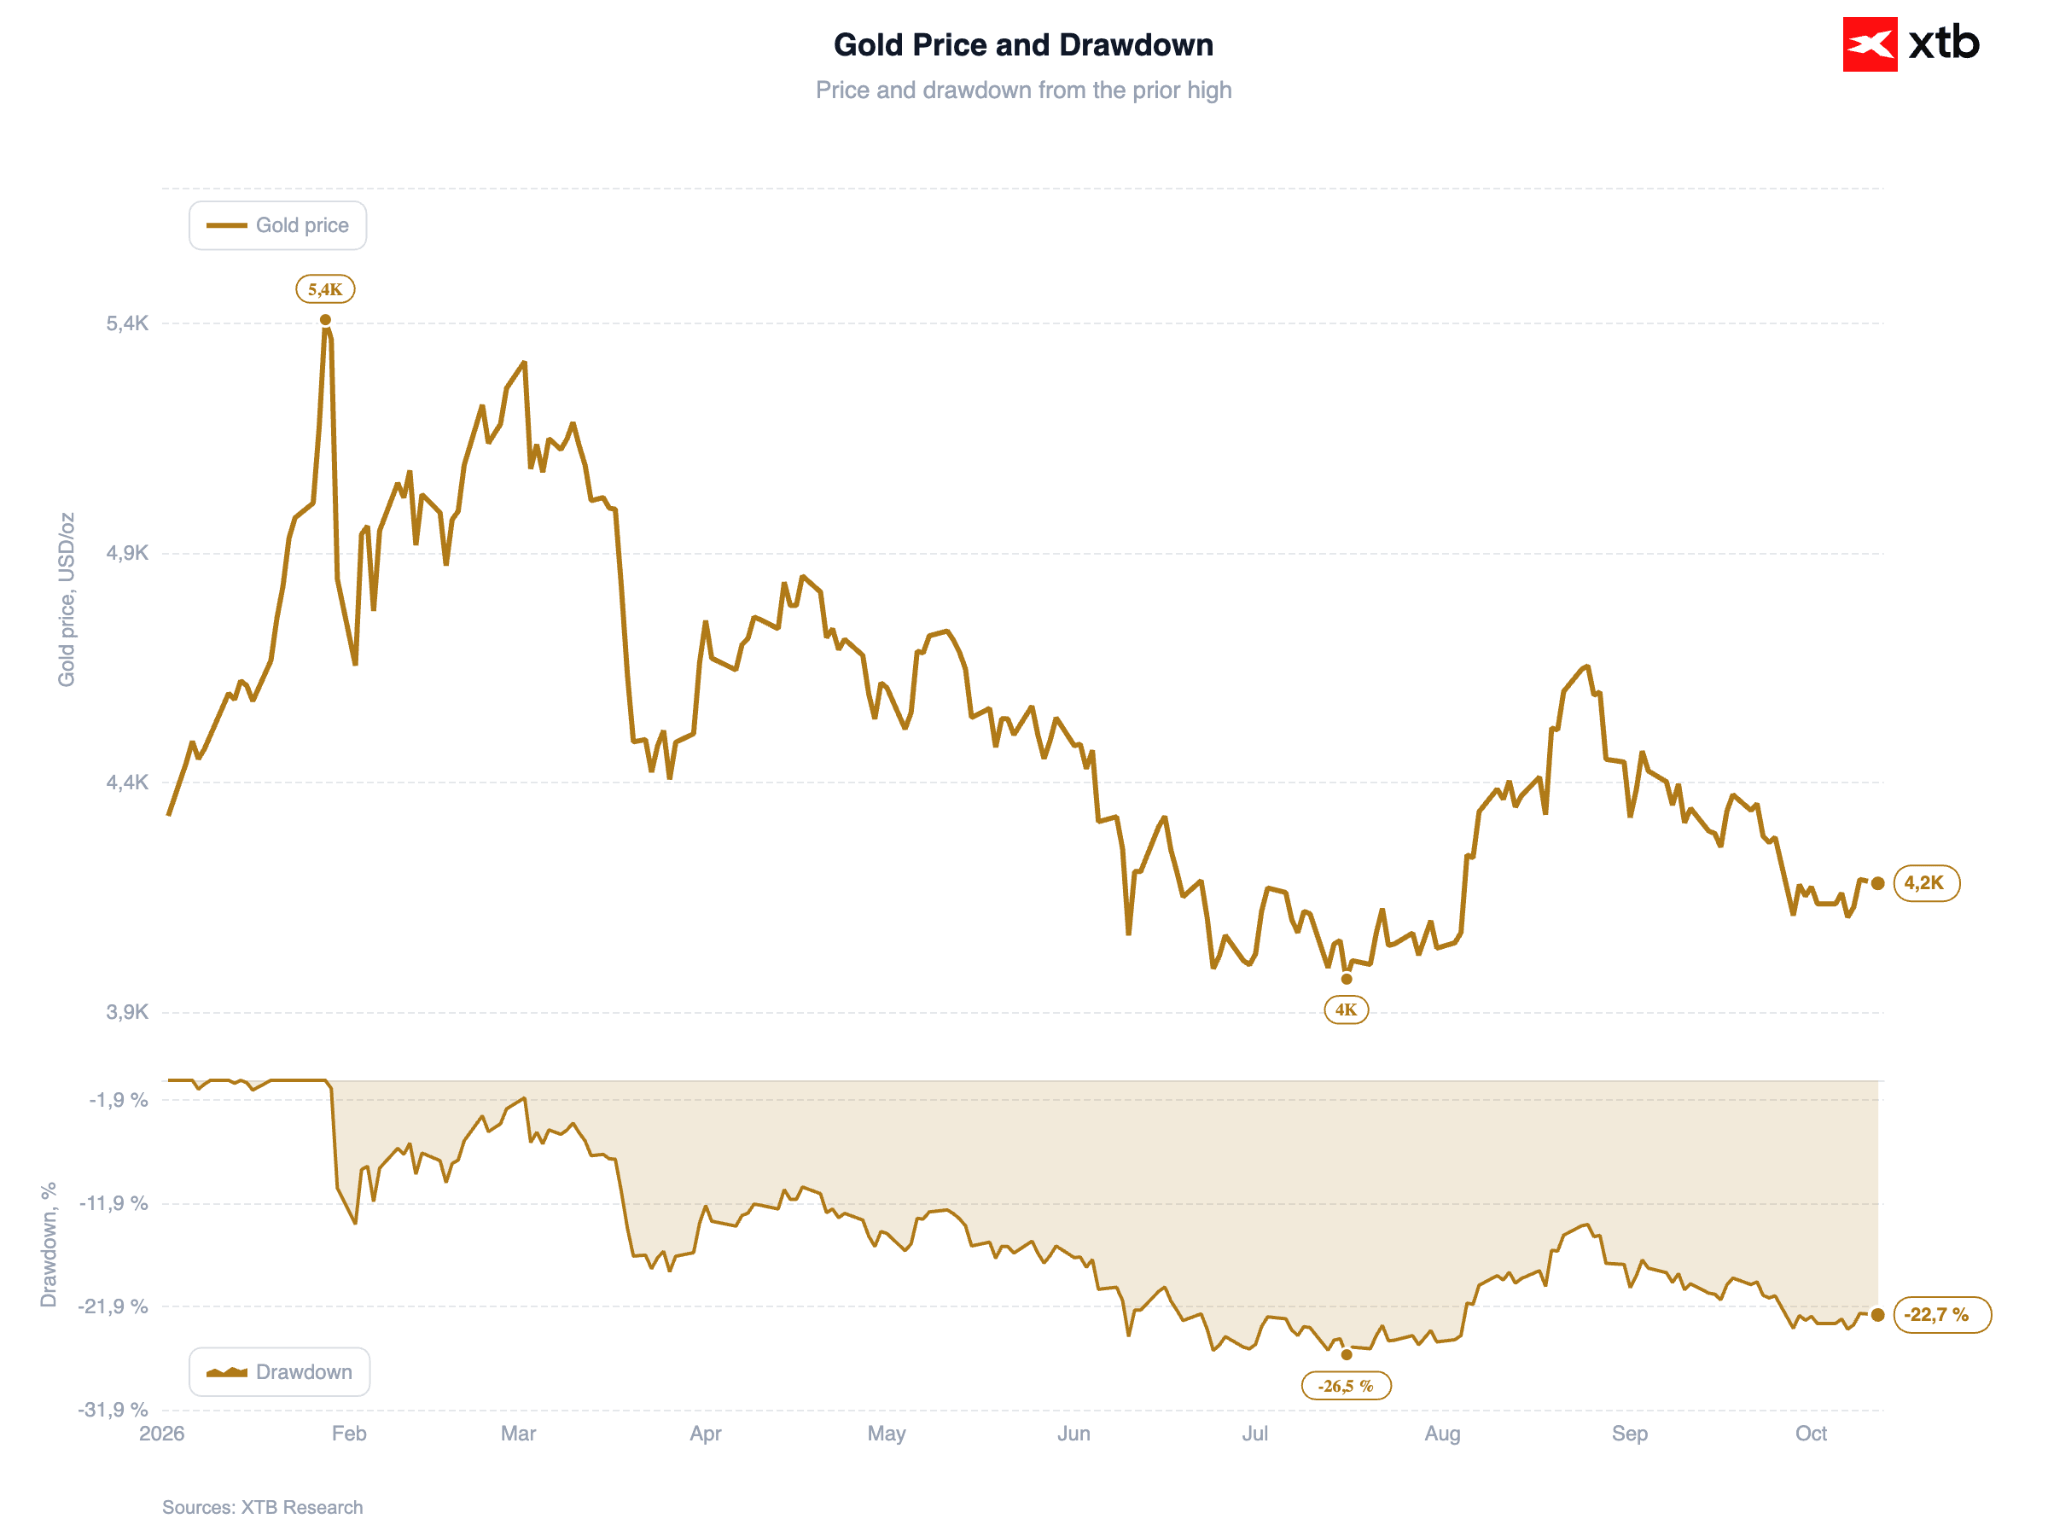
Gold is gaining slightly, supported by falling oil prices that ease inflation fears and offer investors hope that the Fed will pause further rate hikes (around 4,185 USD per troy ounce). Additional support comes from a decline in 30-year US Treasury yields and sustained investment demand; gold ETFs expanded their holdings last week, while the People's Bank of China accelerated its bullion purchases.
Figure 4: Gold (2026)
 Source: XTB Research, 12.10.2026
₿ Cryptocurrencies
Bitcoin is up 0.4%, climbing towards 83.9k USD, while Ethereum rises 1% to 2,560 USD, both benefiting from a modest improvement in risk sentiment at the start of the week.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



📊Market Wrap: Europe Rebouns Despite Higher Oil and Dollar (12.10.2026)


Chart of the Day: Will the RBI's bold regulatory package rescue the rupee? (12.10.2026)


Economic Calendar: Where will stock exchanges remain closed today? (12.10.2026)


Daily Summary: A Shallow Rebound Ahead of Earnings Season
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.