


At the outset: the FOMC decision will be released at 6:00 PM, rather than the customary 7:00 PM.
The reason?
In the United States, the daylight saving time transition occurs on the first Sunday of November, whereas in Europe it takes place on the last full weekend of October.
What to know beforehand
This meeting will not be accompanied by the publication of the Summary of Economic Projections (SEP), which is expected in December. The SEP includes the Dot Plot, illustrating interest rate expectations for the end of coming years, alongside projections for economic growth, unemployment, headline PCE, and core PCE inflation.
The rate decision arrives just days before the official start of the US midterm elections (3 November). However, early voting is already underway across many states, enabling registered voters to cast their ballots in person ahead of election day.
Opinion polls currently point to a Democratic victory in both houses of Congress, with a more pronounced lead in the House of Representatives.
Expectations
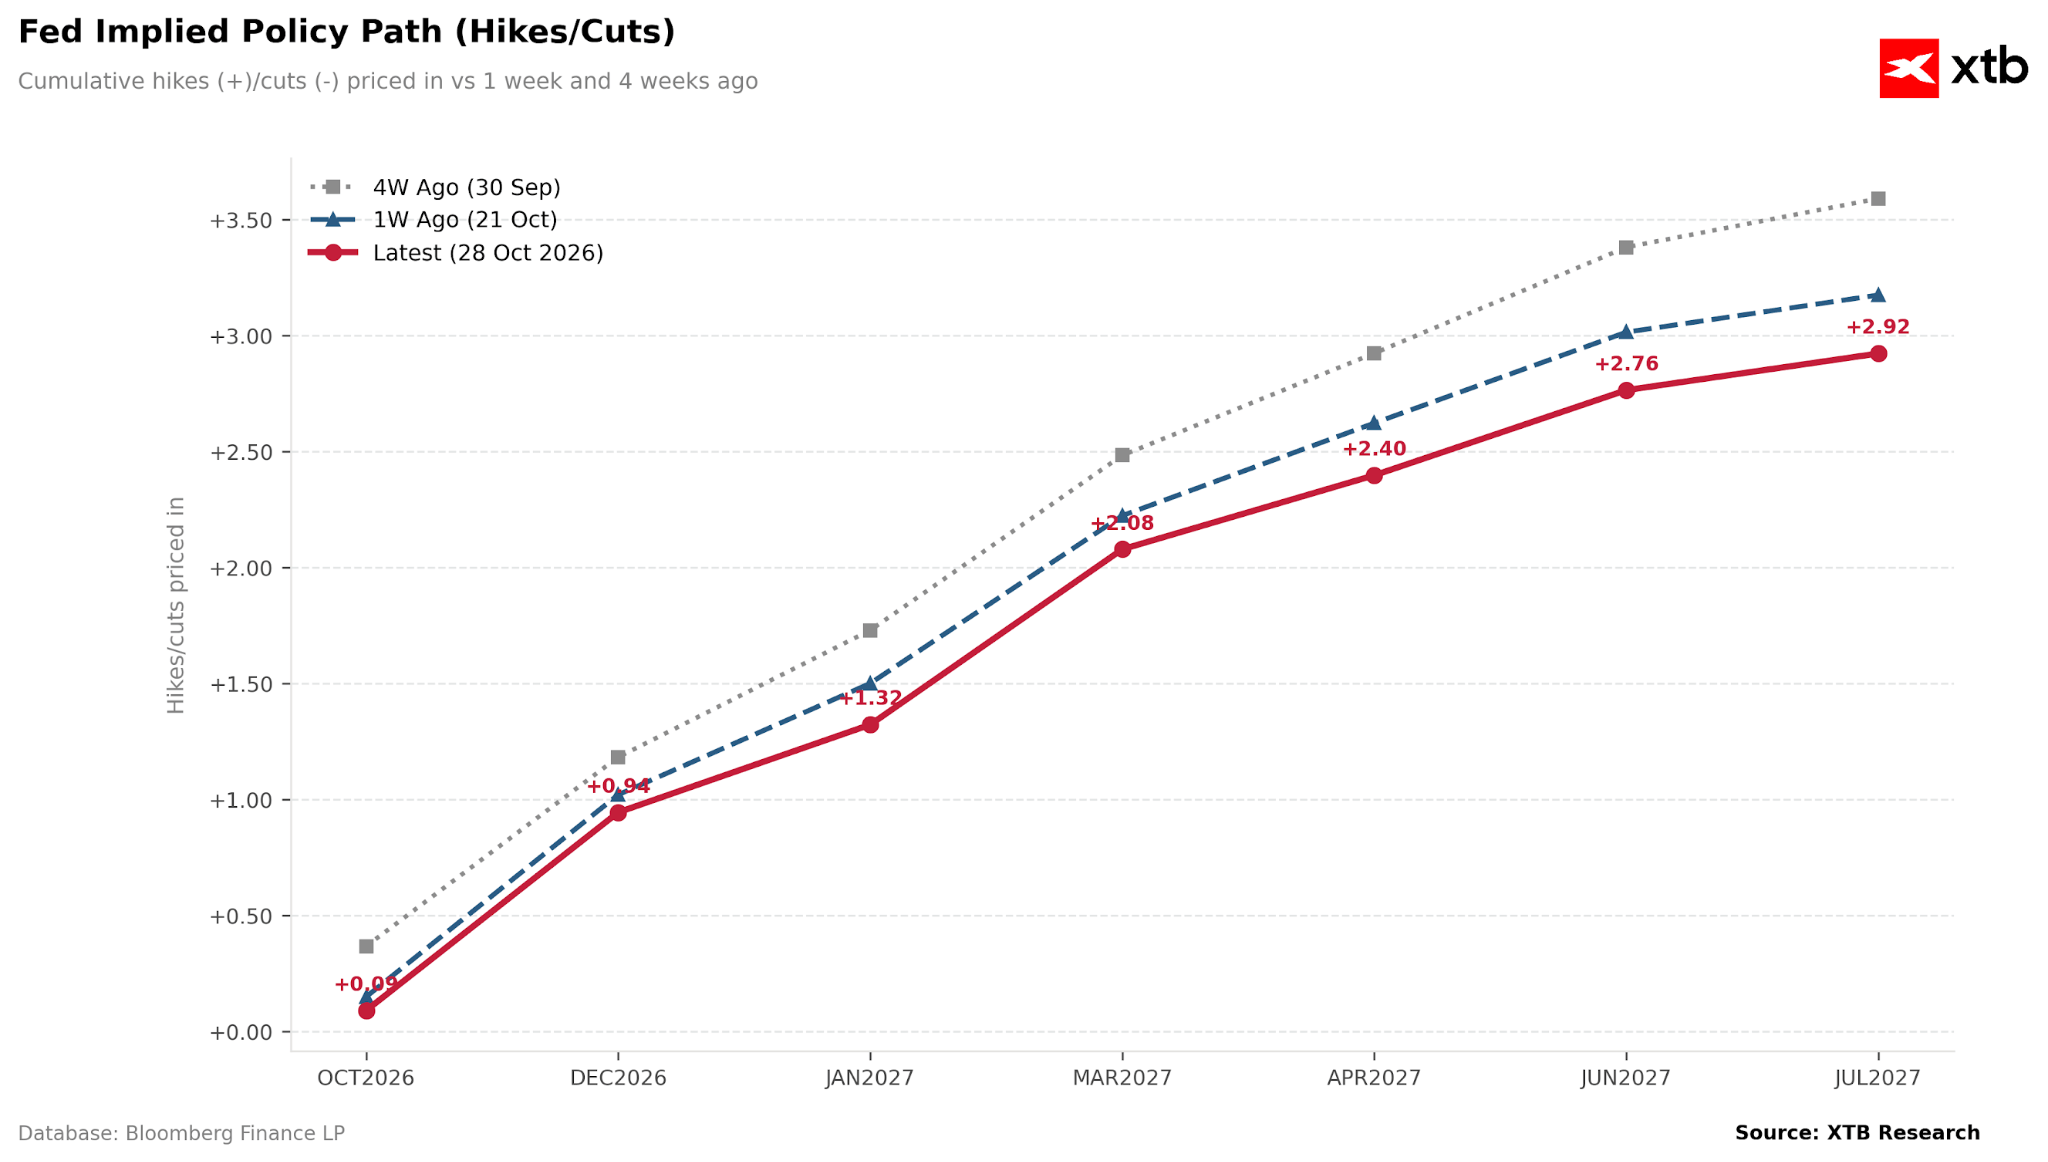
Markets assign less than a 10% probability to a rate hike at today's meeting, whilst fully pricing in a rate increase in December followed by two further hikes before mid-2027.
Figure 1: Market-Implied Path of Fed Interest Rates (2026 - 2027)
 Source: XTB Research, 28.10.2026
The decision is not expected to be unanimous. Three hawkish members could dissent in favour of a hike: Beth Hammack (Cleveland), Lorie Logan (Dallas), and Neel Kashkari (Minneapolis). This would result in a 9-3 vote to hold rates, which can currently be viewed as a neutral to slightly hawkish stance from a market perspective.
Should more members vote for a rate hike, the dollar could find additional support. However, recent remarks from other officials, including Kevin Warsh, John Williams, and Philip Jefferson, gave no indication that they would back an increase today.
Investor attention will primarily focus on the post-meeting press conference. The tone of Kevin Warsh's communication and any guidance regarding future policy steps will drive the dollar, given that a hold at today's meeting is already fully priced in.
Macroeconomic data
Inflation
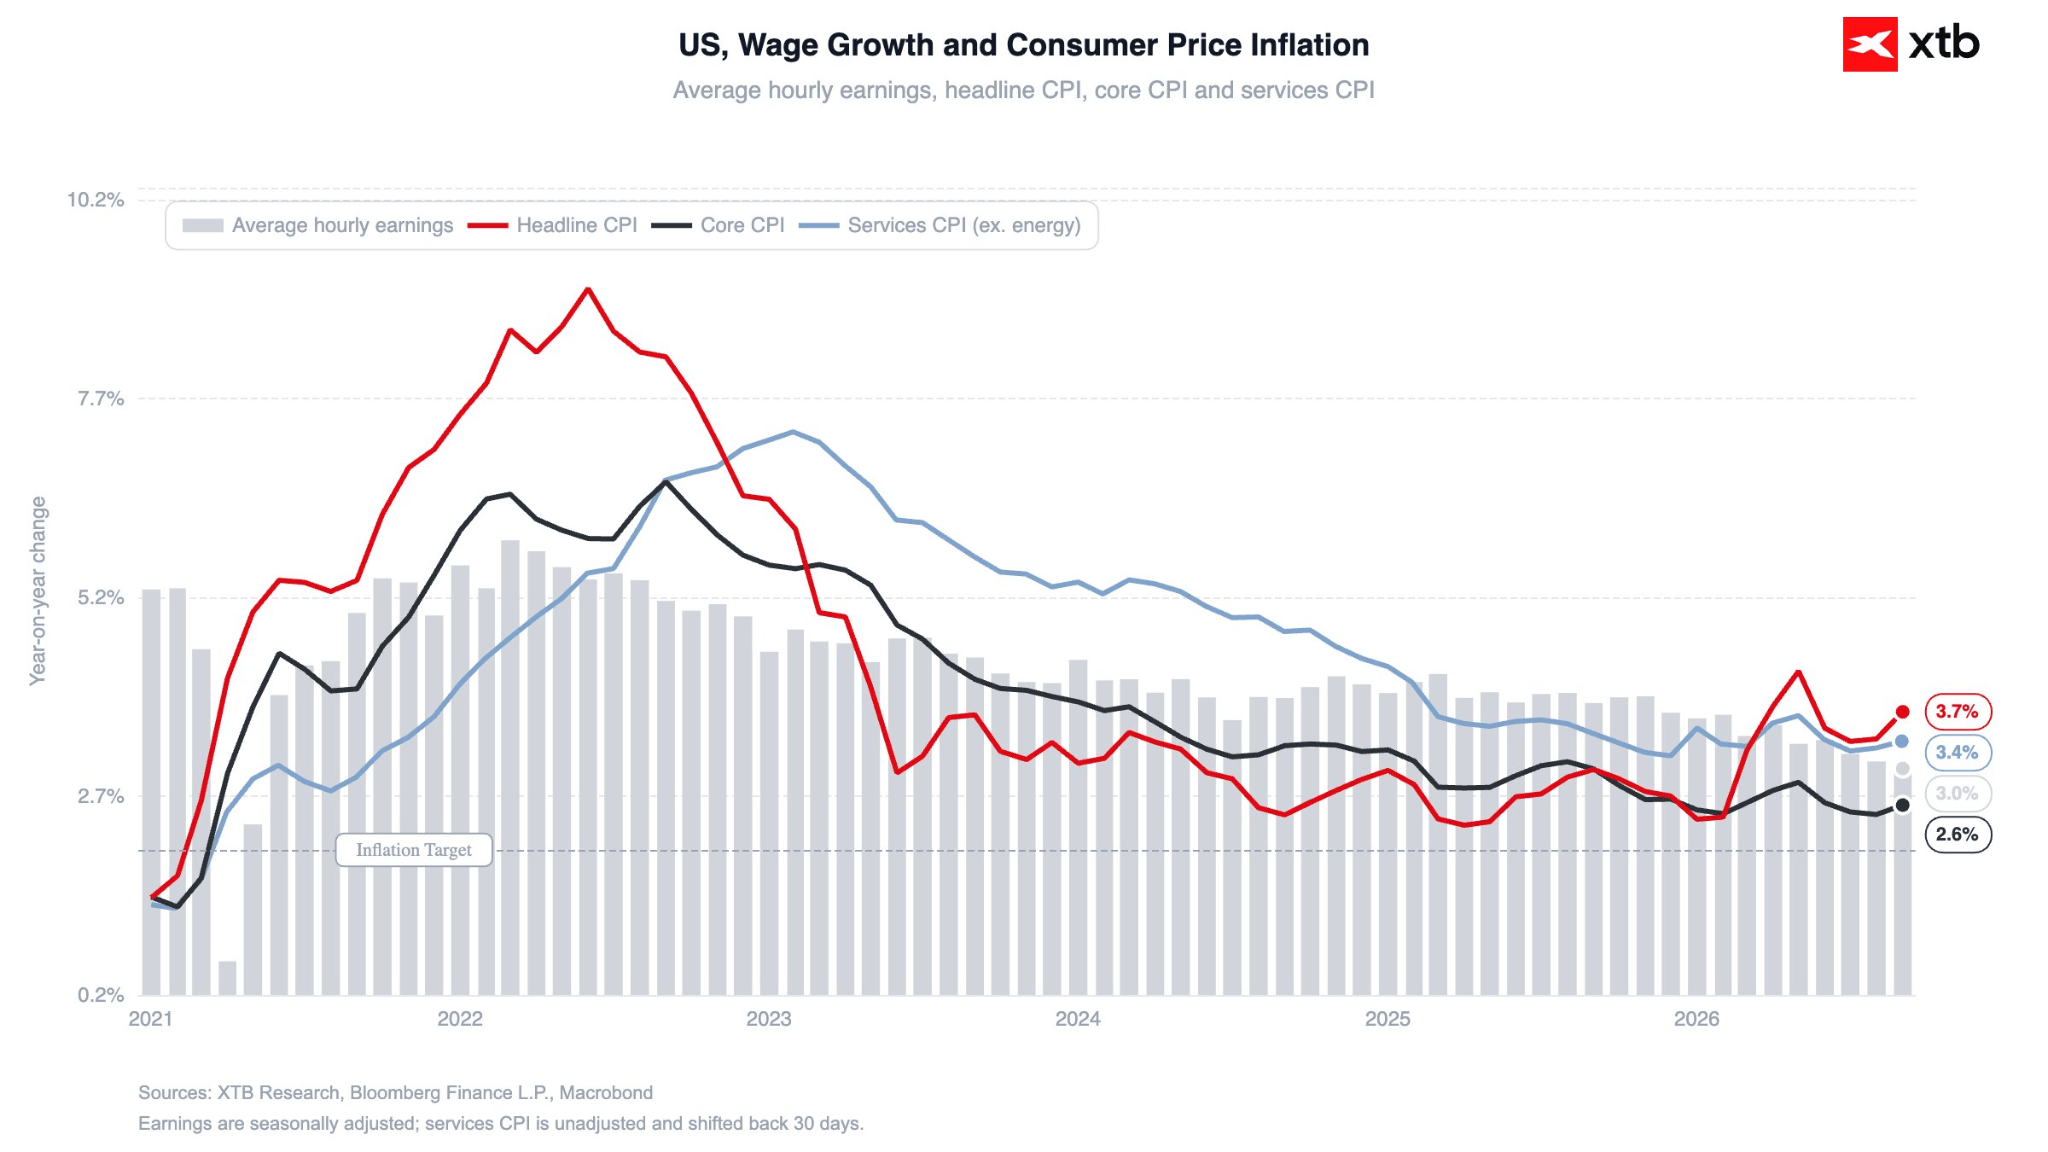
Both CPI measures came in 0.1 percentage points above expectations in September. Energy prices rose sharply, driven by fuel costs (+9.1% MoM and up 34% YoY). Price pressures were also evident across other categories, with computer hardware prices climbing 9.7% YoY.
Figure 2: US CPI Inflation and Wage Growth (2026 - 2027)
 Source: XTB Research, 28.10.2026
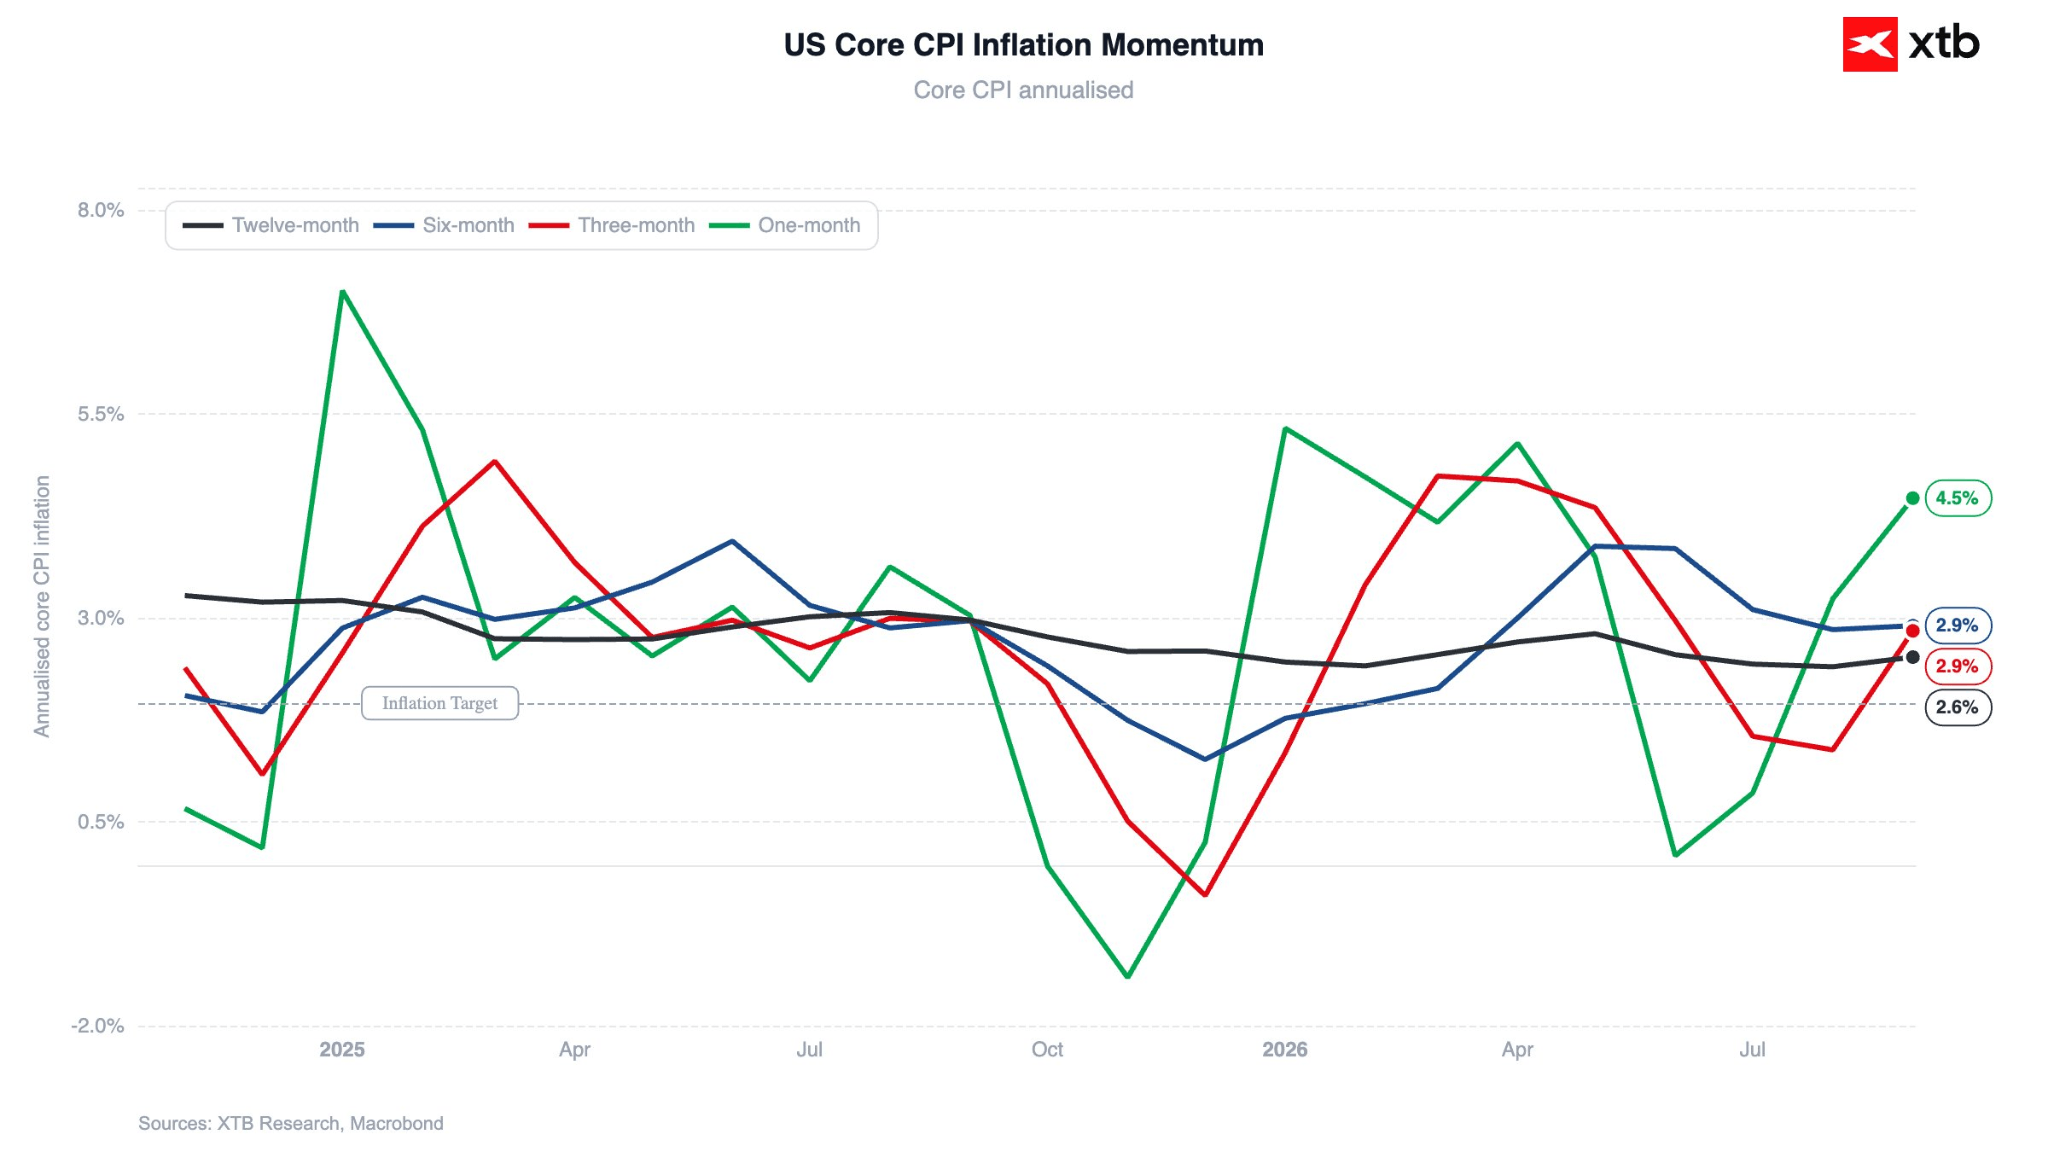
On a monthly basis, headline inflation accelerated to 0.6% (the fastest pace in five months), while core inflation rose 0.3%. Unsurprisingly, 3-month annualized core momentum moved back above the Fed's target.
Figure 3: US Core Inflation Momentum (2025 - 2026)
 Source: XTB Research, 28.10.2026
The surge in core inflation was largely driven by a single component: owner's equivalent rent (OER), raising questions over whether this spike might be a temporary anomaly.
Figure 4: US CPI Inflation Breakdown (2026)
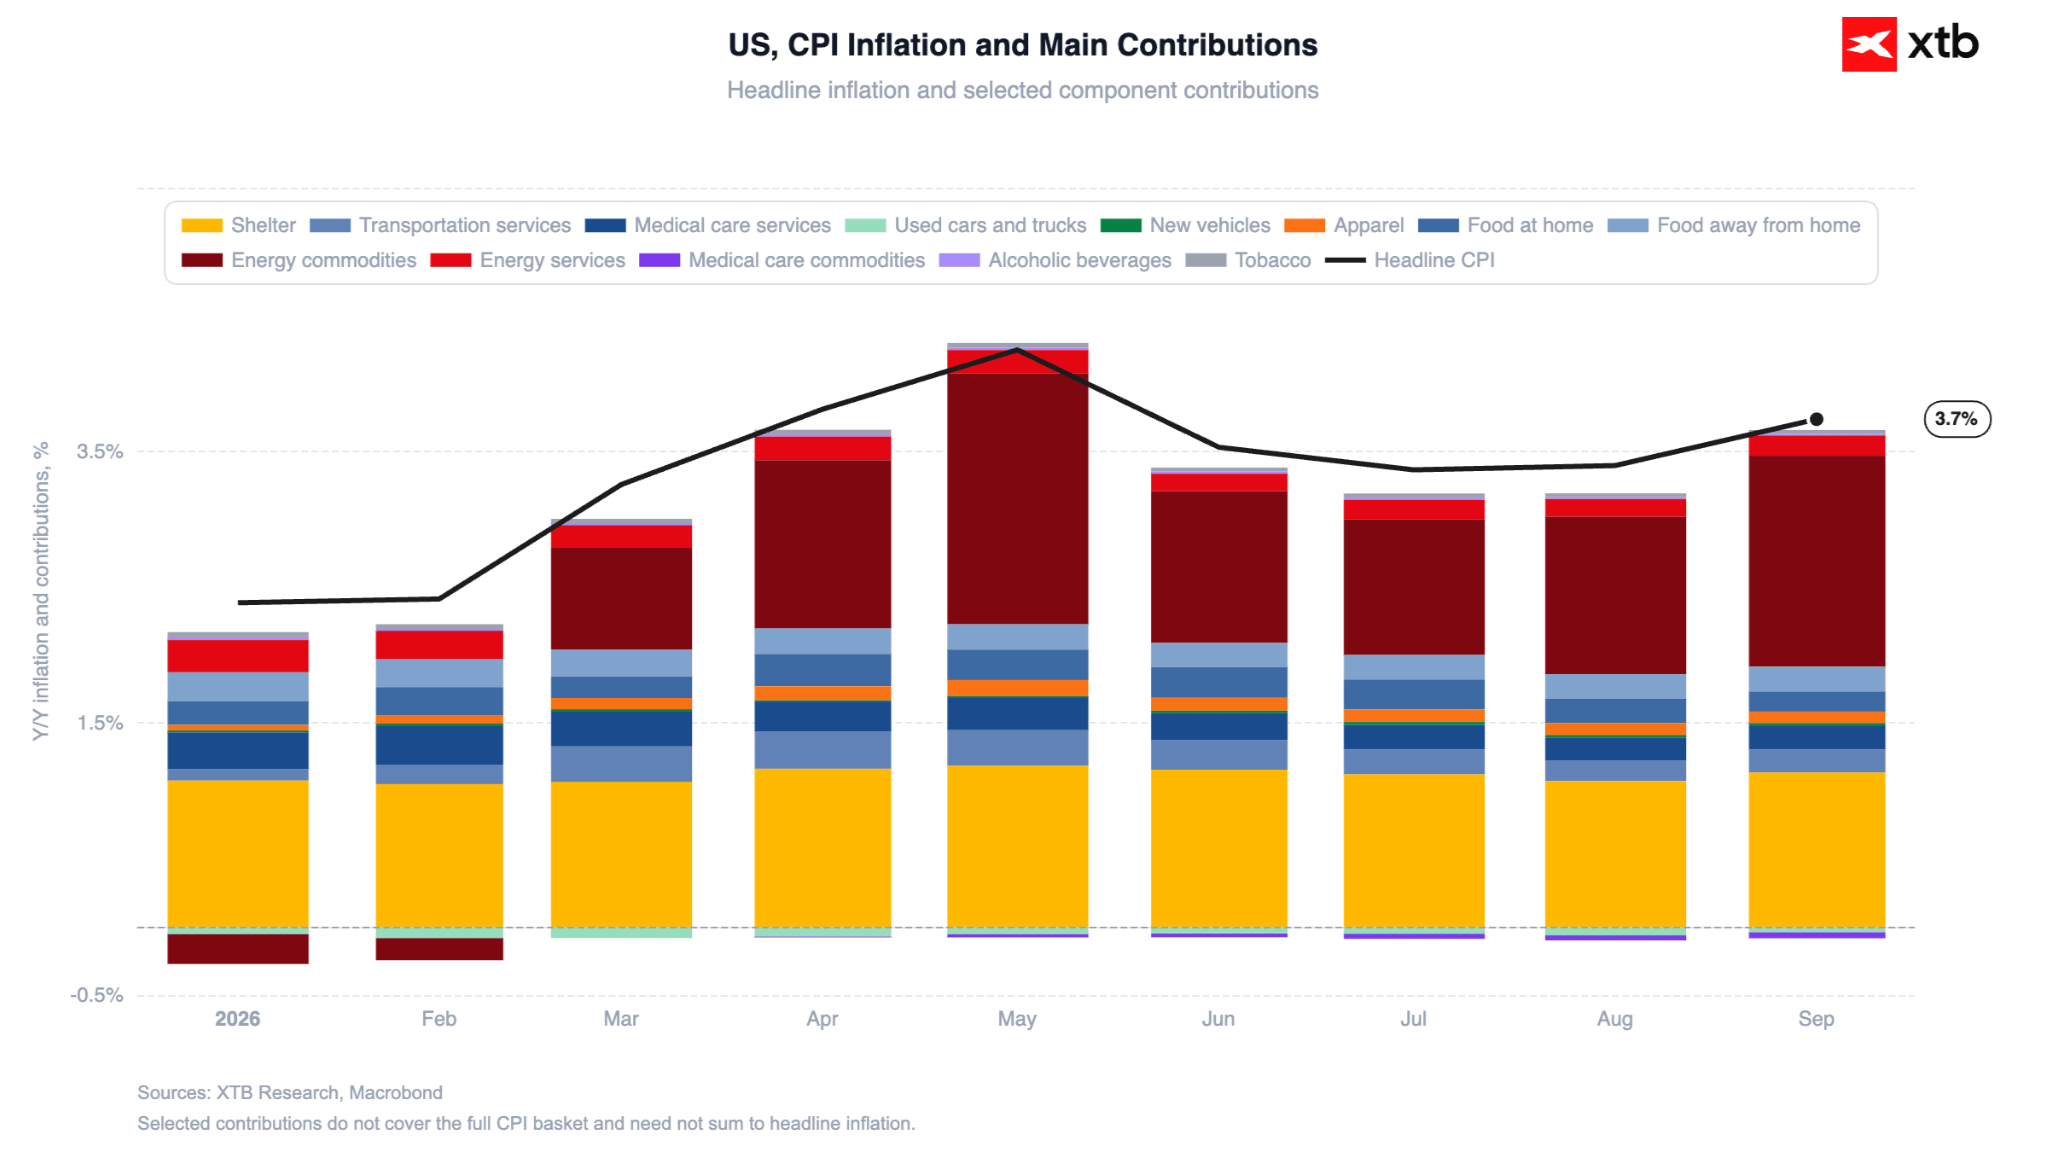 Source: XTB Research, 28.10.2026
High crude oil and LNG prices have not yet significantly spilled over into the broader US economy, though an intensification of this pass-through effect over coming months cannot be ruled out.
Sentiment
Most consumer sentiment indicators remain at or near multi-year lows, and the divergence in consumption growth between low-income households (bottom tercile) and high-income households (top tercile) stays elevated.
Figure 5: University of Michigan Consumer Sentiment Indicators (1976 - 2026)
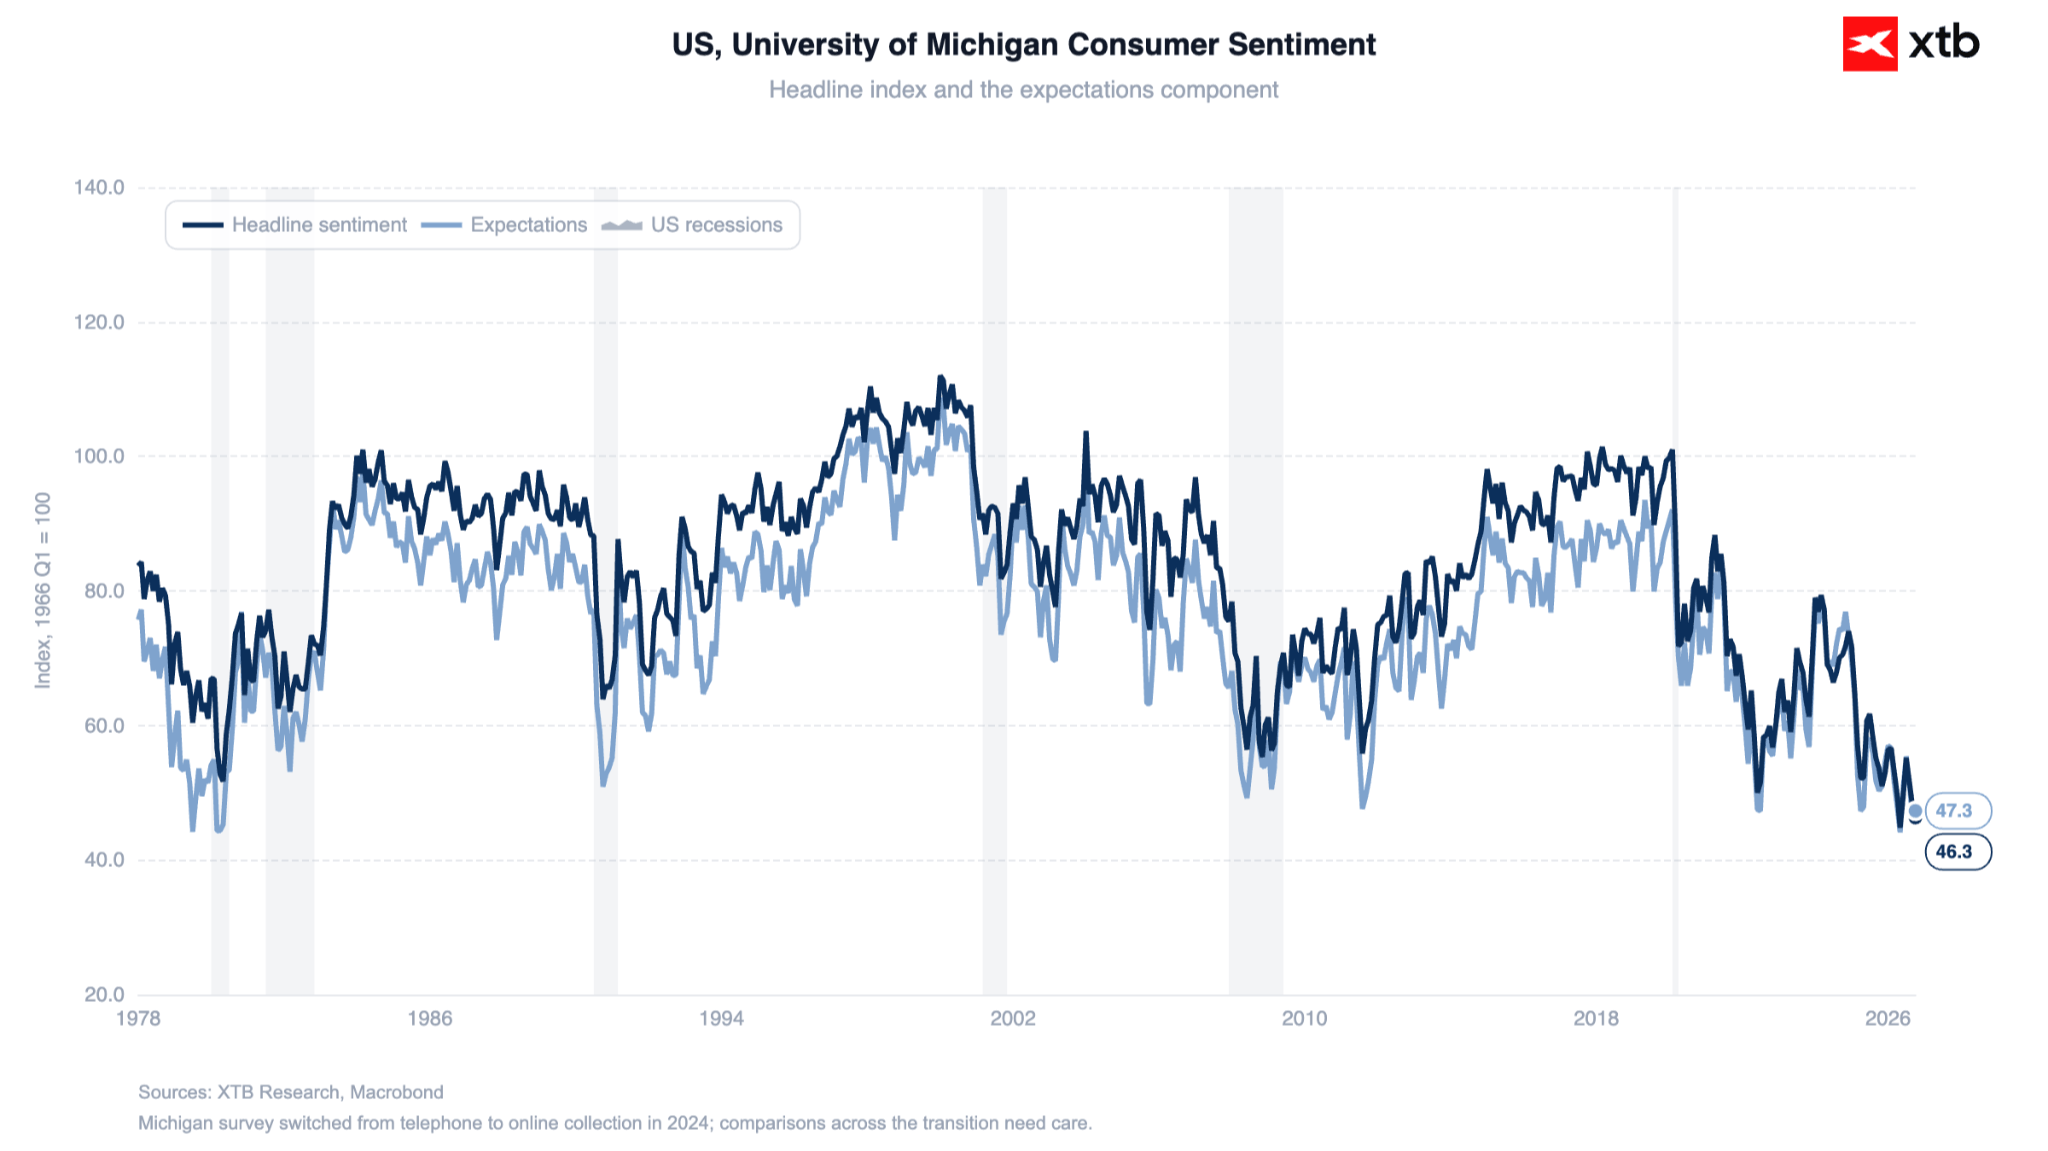 Source: XTB Research, 28.10.2026
Domestic demand
Nevertheless, retail sales surprised to the upside (+6.3% YoY). It is worth noting, however, that consumer spending continues to be supported significantly by dwindling household savings.
Figure 6: US Retail Sales (2024 - 2026)
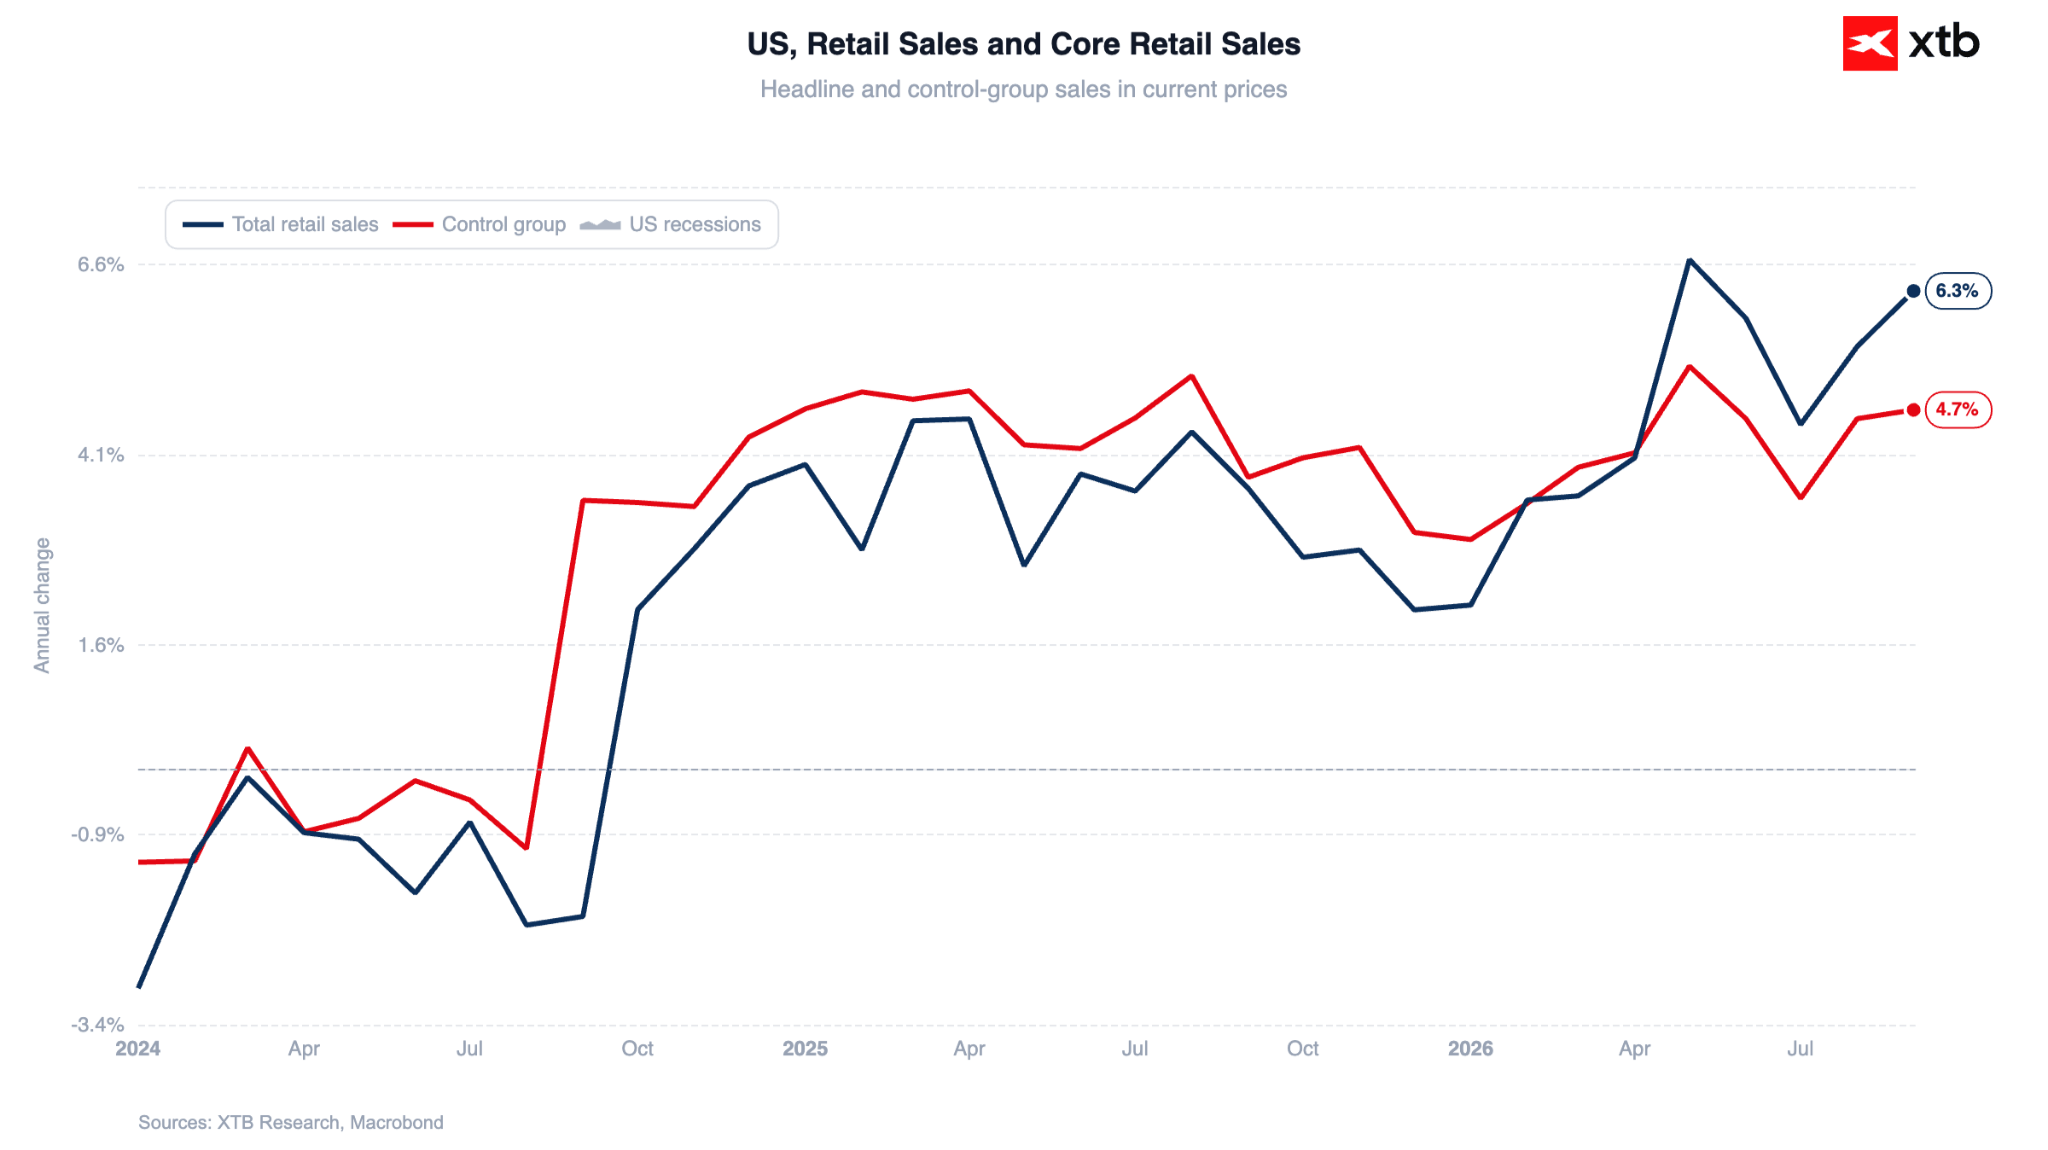 Source: XTB Research, 28.10.2026
Leading indicators
PMI data moderated slightly but continues to signal robust GDP growth of around 4%.
Manufacturing (56.0) is underperforming relative to services (57.9). However, looking ahead to the 12-month outlook, the reverse holds true. Furthermore, manufacturing employment is growing at its fastest pace since March 2012.
- New export orders for goods expanded for the first time since June last year, while service exports grew at their strongest pace since July 2023.
- Input prices are rising faster in manufacturing than in services, reflecting sharp increases in crude oil prices.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



Warsh changes the game, Fed catches its breath [Post-FOMC Comment]

Daily Summary: Oracle drives the market higher, dollar weakens following Fed meeting (28.10.2026)

BREAKING: Bank of Canada hikes for the first time in 3 years but signals caution on further moves



Market Wrap: Renewed confidence in AI drives stock market recovery (27.10.2026)
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.