


The latest preliminary PMI estimates for September brought a clear positive surprise on the demand side in the euro area. Economic activity in Europe is visibly accelerating, with key economies in the region, led by France and Germany, recording a strong rebound in the services sector. Despite challenges related to cost pressures and previous monetary policy tightening, the European private sector is returning to an expansion path at the fastest pace in months. The question remains, however, whether recent interest rate hikes in the euro area and rising energy commodities, such as oil and gas, will not slow down this growth.
Key PMI Data for September
Eurozone (S&P Global):
- Services PMI (Flash): 53.0 pts vs 51.5 pts expected (previous: 51.6 pts)
- Manufacturing PMI (Flash): 52.7 pts vs 52.6 pts expected (previous: 52.7 pts)
- Composite PMI (Flash): 53.1 pts vs 51.7 pts expected (previous: 52.0 pts)
Niemcy (HCOB):
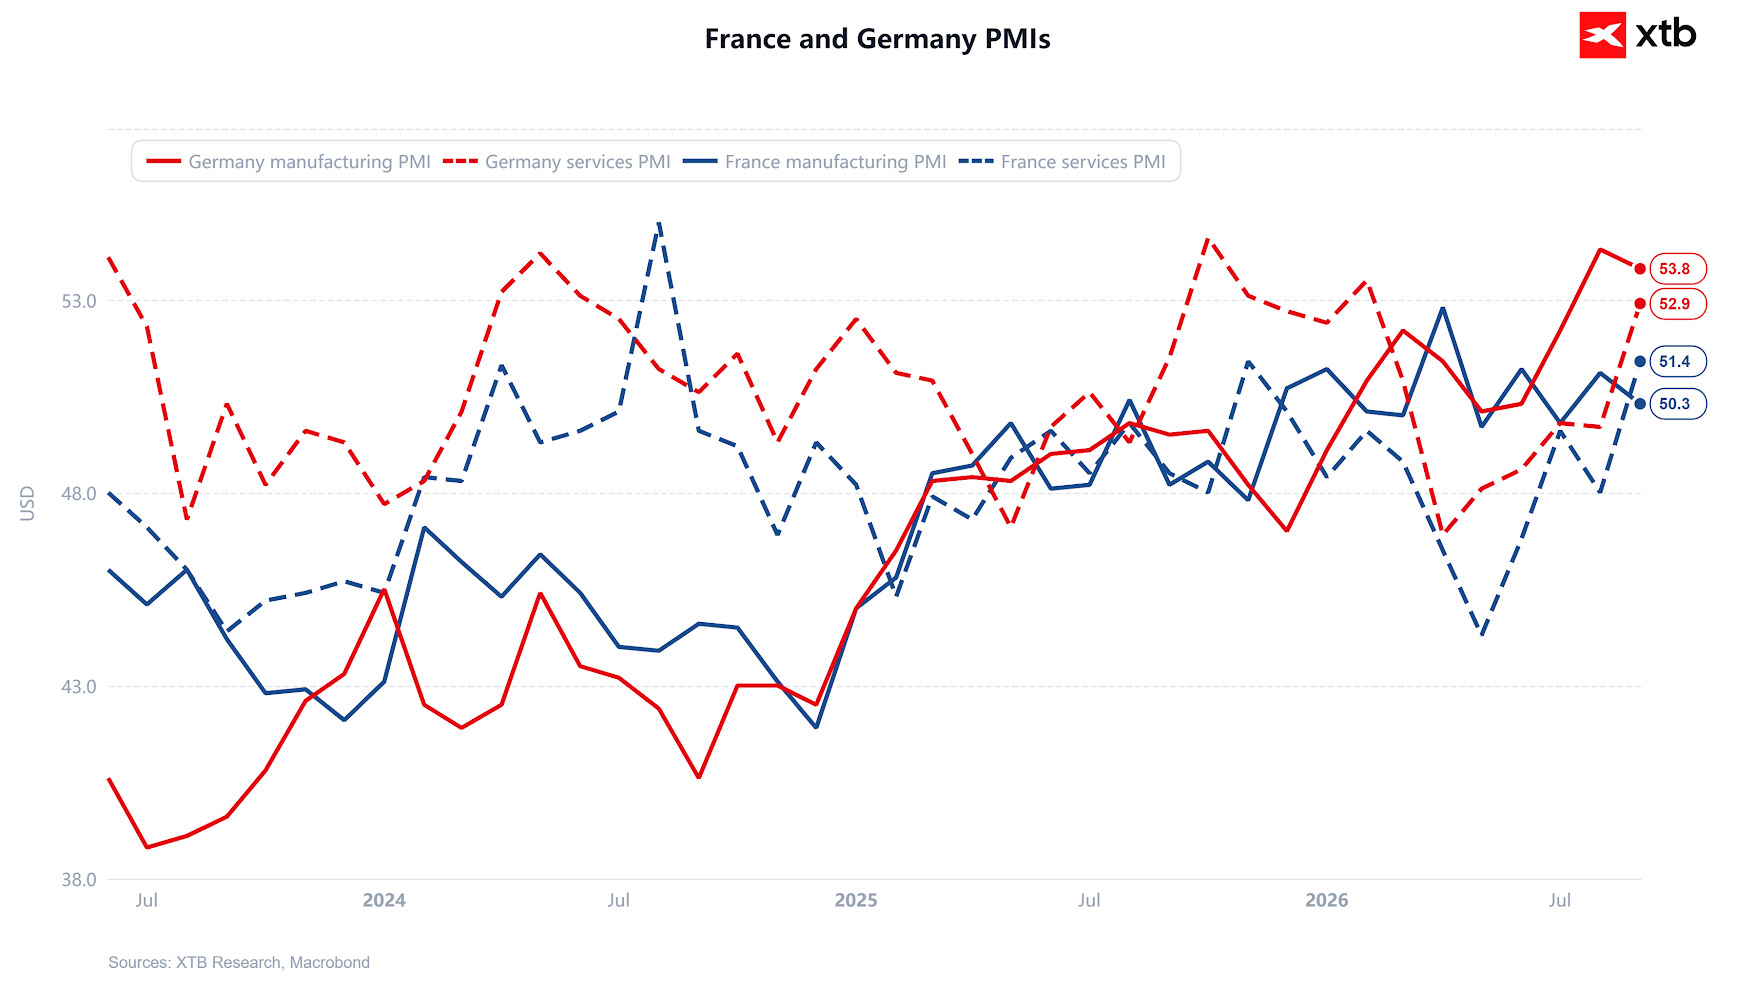
- Services PMI (Flash): 52.9 pts vs 49.9 pts expected (previous: 49.7 pts)
- Manufacturing PMI (Flash): 53.8 pts vs 54.0 pts expected (previous: 54.3 pts)
- Composite PMI (Flash): 53.8 pts vs 51.8 pts expected (previous: 51.8 pts)
Francja (S&P Global):
- Services PMI (Flash): 51.4 pts vs 48.3 pts expected (previous: 48.0 pts)
- Manufacturing PMI (Flash): 50.3 pts vs 51.0 pts expected (previous: 51.1 pts)
- Composite PMI (Flash): 51.2 pts vs 48.7 pts expected (previous: 48.5 pts)
Commentary on Data and a Dilemma for the ECB
The published data indicate clear resilience in the European economy. A particularly positive signal is the decisive return of the services sector to the expansion zone—above the 50-point threshold—in both France and Germany. In France, the aggregated Composite index reached its fastest growth rate in over two years, while for the entire euro area, it was the most dynamic rise in economic activity in nearly three and a half years.
However, the main challenge for the European Central Bank remains resurging inflationary pressure. Reports point to a renewed acceleration in input cost growth and finished goods prices, driven in part by higher fuel, energy, and raw material prices. For the ECB, improved economic activity alongside returning price pressures means that the bank cannot yet declare victory over inflation.
Although recent days brought a decline in global oil prices in response to hopes of de-escalating Middle East tensions, markets are pricing in roughly a 47% probability of another 25 bps rate hike by the ECB at its October meeting and see a strong chance of a full rate increase before the end of this year.
EURUSD Technical Analysis
Despite significantly better-than-expected readings from the European economy and recently falling oil prices, the EURUSD exchange rate reaction remained opposite to theoretical expectations. The US dollar maintains the advantage gained following the recent Federal Reserve meeting, pushing the currency pair toward a key support zone.
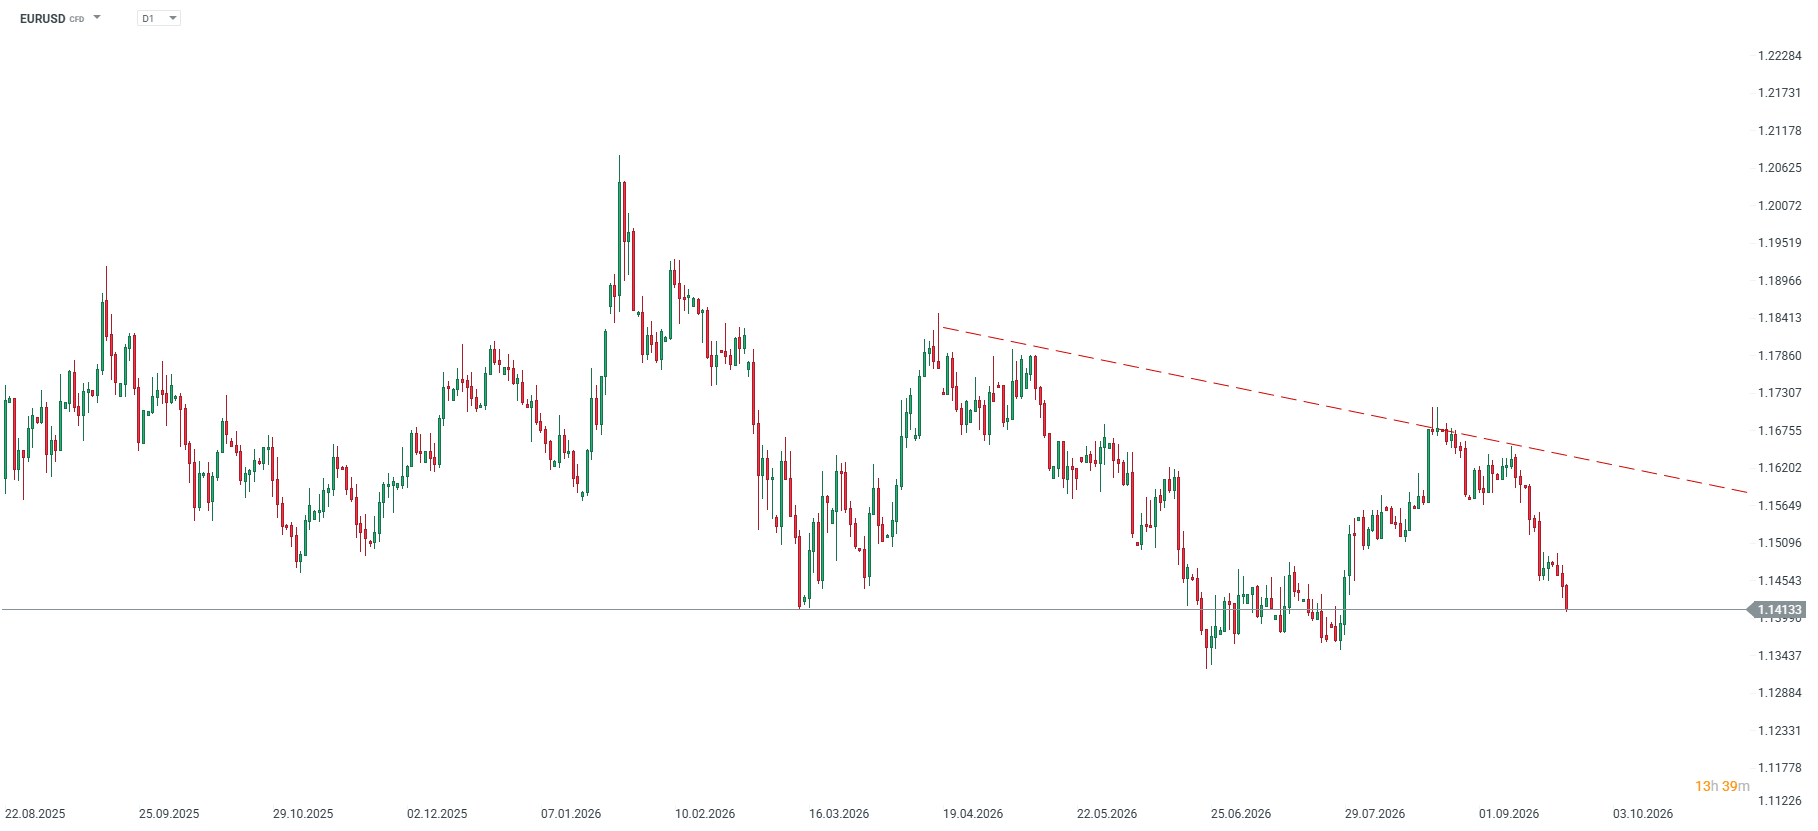
- Key support (1.1400): EURUSD quotes are approaching a broad and important support level around 1.1400. A sustained downside breakout past this barrier would open the door to a deeper sell-off toward the 1.1350 level.
- Trendline and resistance: The main structure on the daily (D1) and 4H timeframes is defined by a downtrend line. The first significant resistance in any attempt to recover losses is the local peak at 1.1495, followed by the trendline and resistance near 1.1560.
- Market scenarios: Buyers need a decisive breakout above the downtrend line to negate supply pressure and trigger a move toward 1.1560. As long as the rate stays below this line, the risk of testing and breaking the 1.1400 support remains elevated.



🛢️WTI crude tests $90. Brent below $100


Economic Calendar - Another day of central bankers' speeches. Is AUDUSD responding to inflation risks?


Morning Briefing: Global Markets Riding AI Wave, Rising Geopolitical Tensions, and Hawkish Central Banks (22.09.2026)

Chart of the Day: European Gas (NATGAS.EU) below 80 EUR, but Goldman Sachs warns of 105 EUR/MWh.
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.