


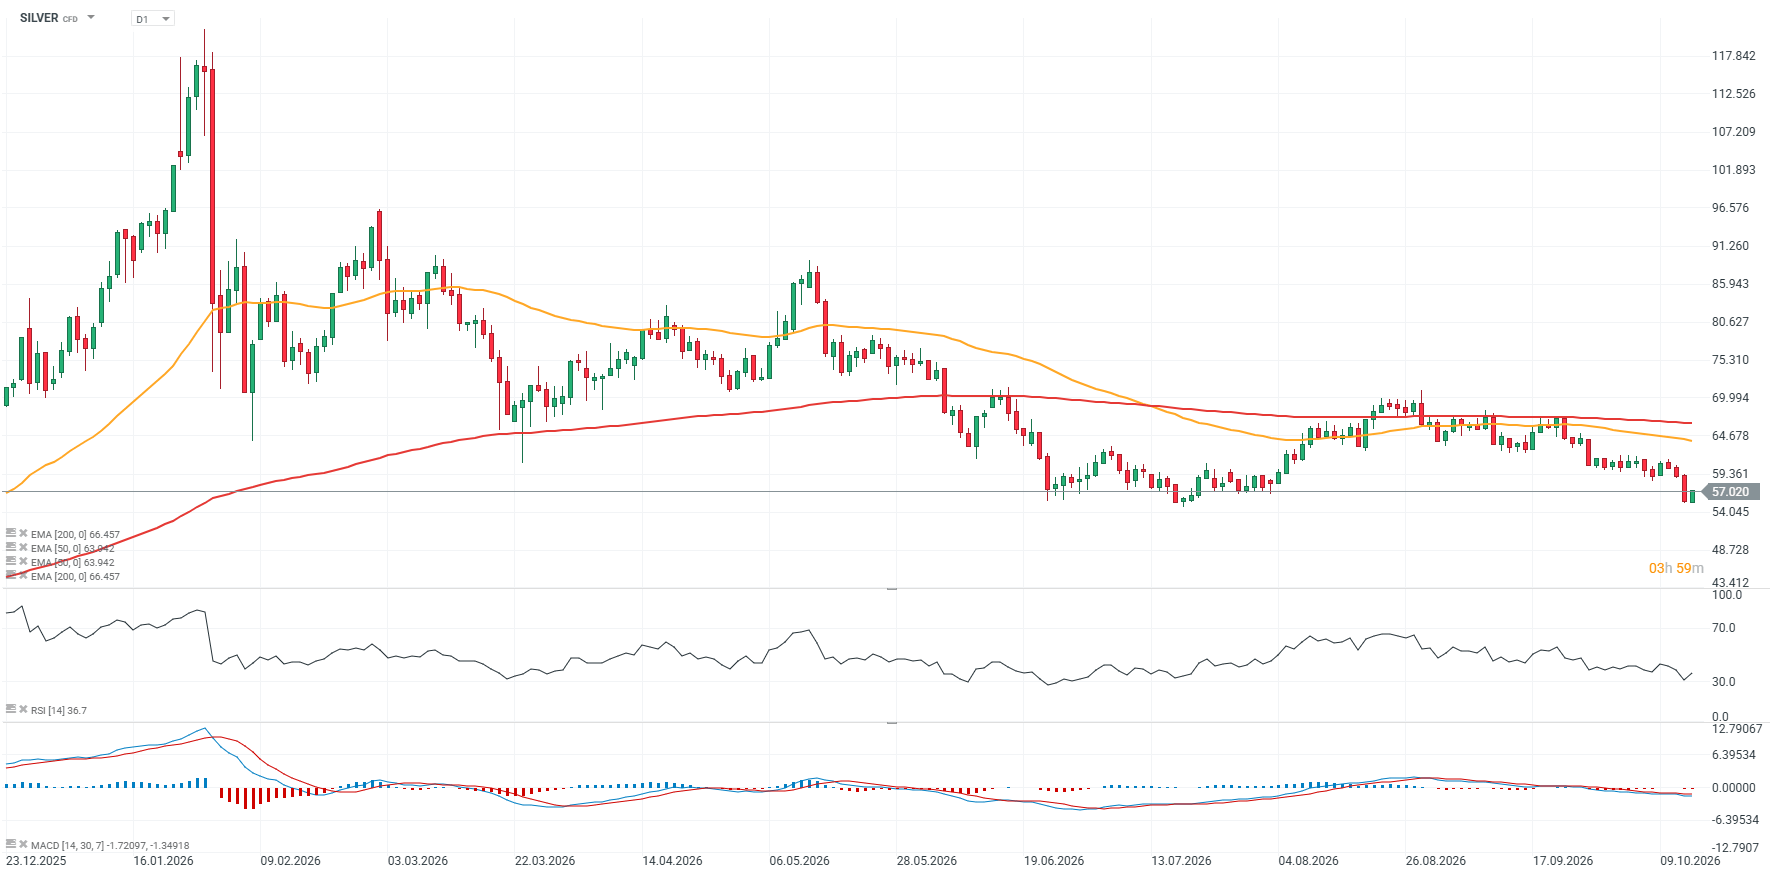
The pullback in U.S. Treasury yields from record levels supported a rebound in precious metals and risk assets today, including equities and Bitcoin. The U.S. 10-year Treasury yield has fallen from around 5.3% to 5.08%, while gold is up 1.2% and silver is rebounding by 2.5%. Wall Street futures are stabilising and attempting to recover, with US30 (Dow Jones Industrial Average) performing best, up 1.1%, while the US2000 (Russell 2000), which tracks small- and mid-cap companies, is also looking strong with a gain of 0.9%.
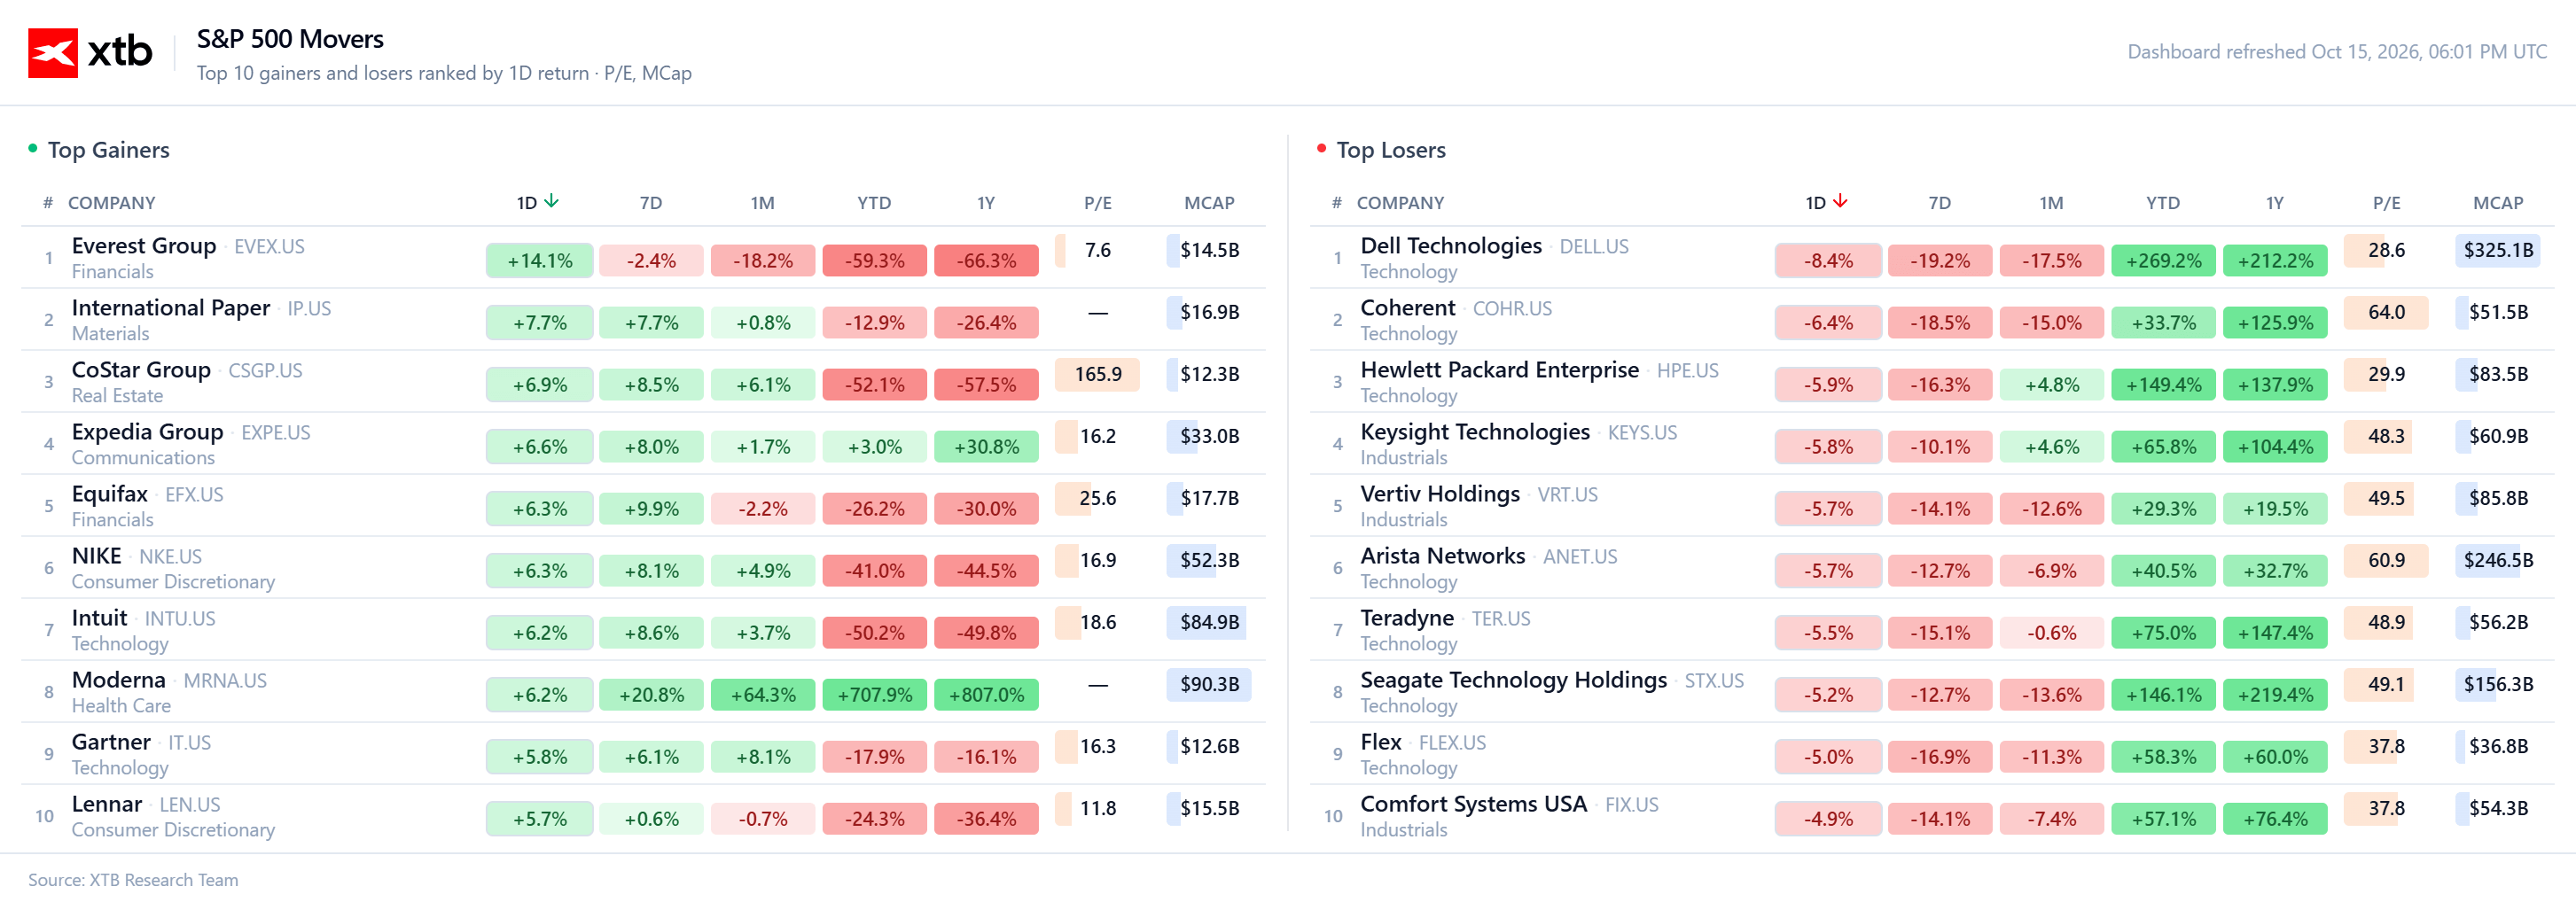
In the U.S. equity market, we are seeing renewed interest in stocks outside the technology sector, many of which have underperformed in recent years. Today’s outperformers include real estate data and analytics provider CoStar, International Paper and even Nike. The weakest performers are concentrated in technology, particularly among companies viewed as key beneficiaries of the build-out of AI infrastructure.
WTI and Brent crude are rising today after EIA data showed that U.S. crude inventories fell by 8.557 million barrels, while the market had expected an increase of 150,000 barrels; inventories had declined by 3.186 million barrels previously. The draw in crude and distillate inventories was not offset by the increase in gasoline stocks, which came in around 3.5 times higher than expected.
- Gasoline inventories rose by 3.518 million barrels, well above the expected decline of 0.911 million barrels; inventories had increased by 0.382 million barrels previously.
- Distillate inventories fell by 2.527 million barrels, more than the expected decline of 1.720 million barrels; inventories had decreased by 0.042 million barrels previously.
- Crude inventories at the Cushing hub increased by 1.862 million barrels, compared with a rise of 0.444 million barrels in the previous week.
Higher-than-expected U.S. inflation data failed to stop the decline in Treasury yields. U.S. producer price inflation rose by as much as 1.3% m/m in September, well above the 0.6% forecast and up from 0.4% previously. U.S. PPI increased by 6.3% y/y, compared with expectations of 5.4%, while the previous reading was revised higher from 5.4% to 5.6%.
- Core PPI rose by 0.7% m/m, more than twice the 0.3% forecast and up from 0.2% previously.
- Core PPI increased by 5.0% y/y, above expectations of 4.4% and the previous 4.6%.
- U.S. retail sales rose by 0.8% m/m, clearly above the 0.3% forecast, although slower than the previous 1.2% increase.
- Core retail sales increased by 0.9% m/m, compared with expectations of 0.5% and 1.4% in the previous month.
- U.S. initial jobless claims came in at 199,000, compared with a forecast of 200,000 and 197,000 previously.
- Continuing jobless claims stood at 1.71 million, broadly in line with the 1.709 million forecast and slightly below the previous 1.716 million.
- The New York Fed manufacturing index rose to 25.5 points, well above the 12-point forecast and the previous 7.6.
- The Philadelphia Fed business activity index fell to 20.9 points, below the 28-point forecast and down from 37.8 previously.
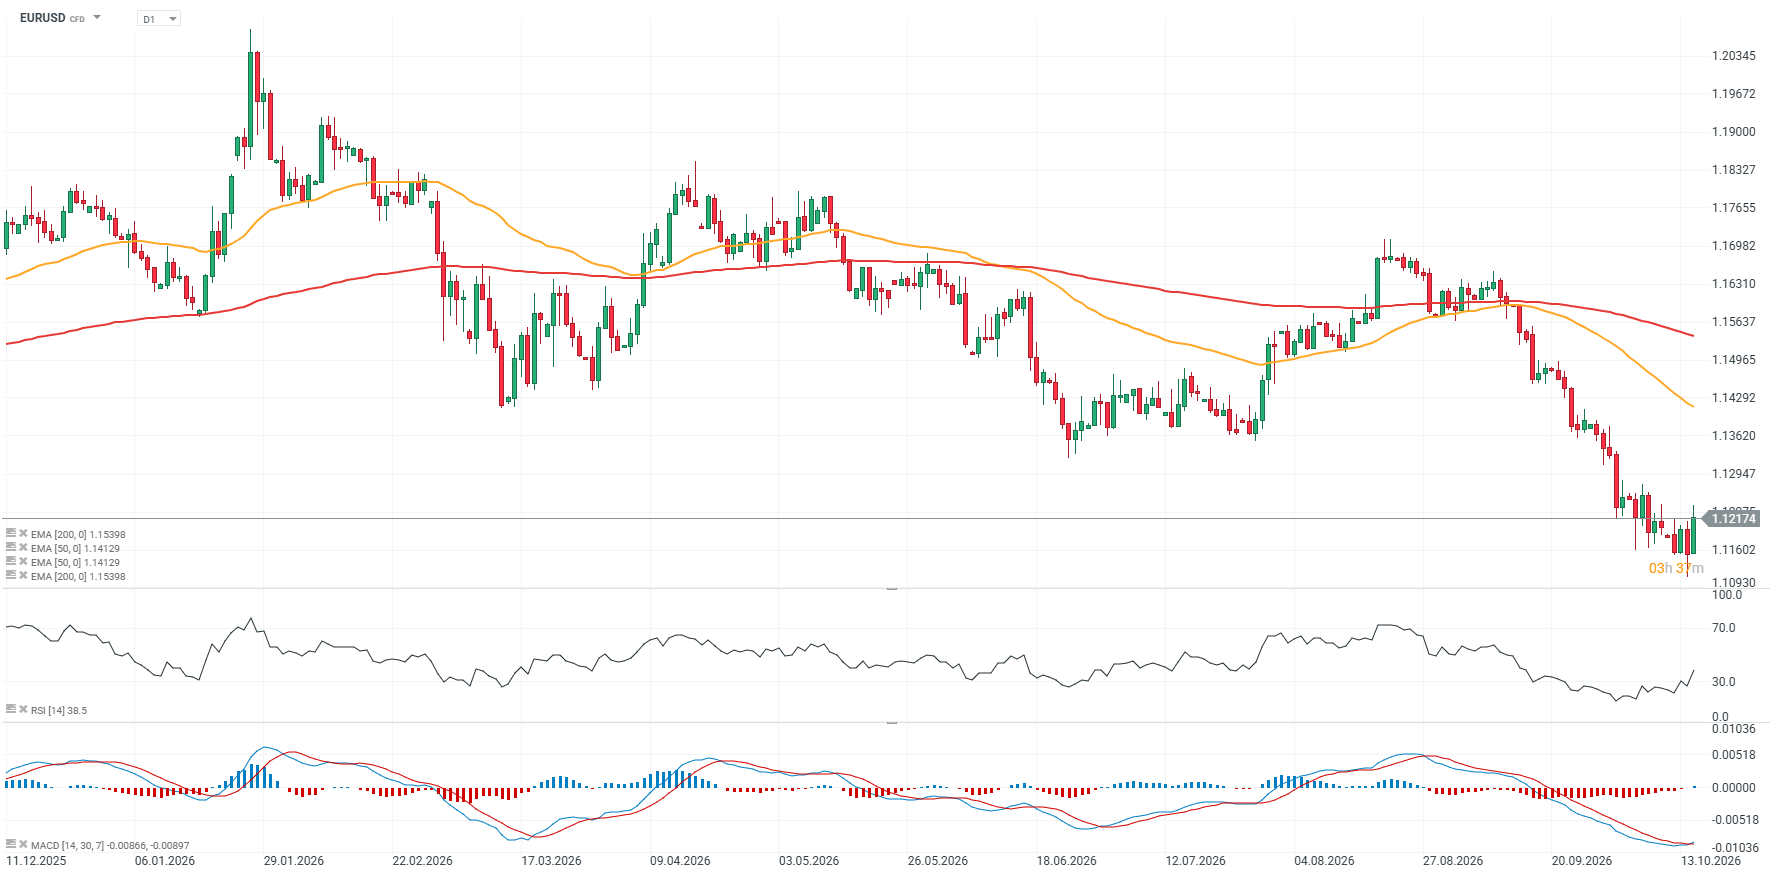
EUR/USD is up nearly 0.6%, while the U.S. Dollar Index futures contract (USDIDX) has pulled back to around 101.8 from 102.7 seen yesterday. The U.S. 4-week Treasury bill auction was solid: the bid-to-cover ratio rose to 2.56 from 2.40, pointing to clearly stronger investor demand despite as much as $110 billion of debt being sold. The stop-out yield came in at 4.% versus 3.98% previously, meaning financing costs increased slightly, but given the strong auction coverage, the data do not suggest any problems with the market’s ability to absorb short-term U.S. government debt.
The U.S. Treasury received offers to sell bonds worth nearly $40.84 billion, of which it accepted the maximum planned amount of $6 billion. As part of the operation, the Treasury accepted 3 of 42 eligible issues, focusing on coupon securities maturing between 2037 and 2046. Bitcoin rebounds today to $82k after defending $80k support level.
SILVER, EURUSD chart (D1 interval)
Source: XTB
Source: XTB
Strongest and weakest stocks in the S&P 500
Today’s S&P 500 session shows a very high degree of dispersion between individual stocks, with clear pressure concentrated in parts of the technology and industrial segments. On the upside, Everest Group stands out with a gain of around 14.1%, while International Paper (+7.7%), CoStar Group (+6.9%) and Expedia (+6.6%) are also posting strong rebounds. Gains in Nike (+6.3%), Intuit (+6.2%) and Moderna (+6.2%) show that buying interest is spread across several sectors rather than being limited to a single industry.
At the same time, the downside is dominated by companies closely linked to technology, AI infrastructure and data centres: Dell Technologies is down 8.4%, Coherent 6.4%, HPE 5.9%, Vertiv 5.7%, Arista Networks 5.7% and Seagate 5.2%. It is worth noting, however, that many of these stocks remain very strong over a longer horizon, with Dell still up around 269% YTD, HPE 149%, Seagate 146% and Teradyne 75%. This suggests that the current move may be more consistent with sharp profit-taking than with a clear reversal of their longer-term trends. Overall, the session points to a strong rotation of capital and reduced exposure to the most crowded parts of the market, alongside a rebound in some previously heavily sold-off stocks.
Source: XTB


Strong US macro data 🗽 Industrial production and prices rise


Market wrap: European indices rebound 🔼 Defence stocks on the rise


TSMC in Talks with Elon Musk Over Terafab


Chart of the Day: NATGAS - Are there chances for a seasonal rebound amid warm weather?
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.