

- Nasdaq 100 futures gained over 1% following the worst weekly sell-off for the index since April 2025.
- China Q3 GDP grew by 4.5% YoY, beating the 4.4% consensus forecast.
- Brent crude pulled back to around 108 USD after approaching 112 USD amid stabilising Persian Gulf oil flows.
- Upcoming quarterly earnings from Netflix, Tesla, Meta, and IBM will test market confidence in the artificial intelligence sector.
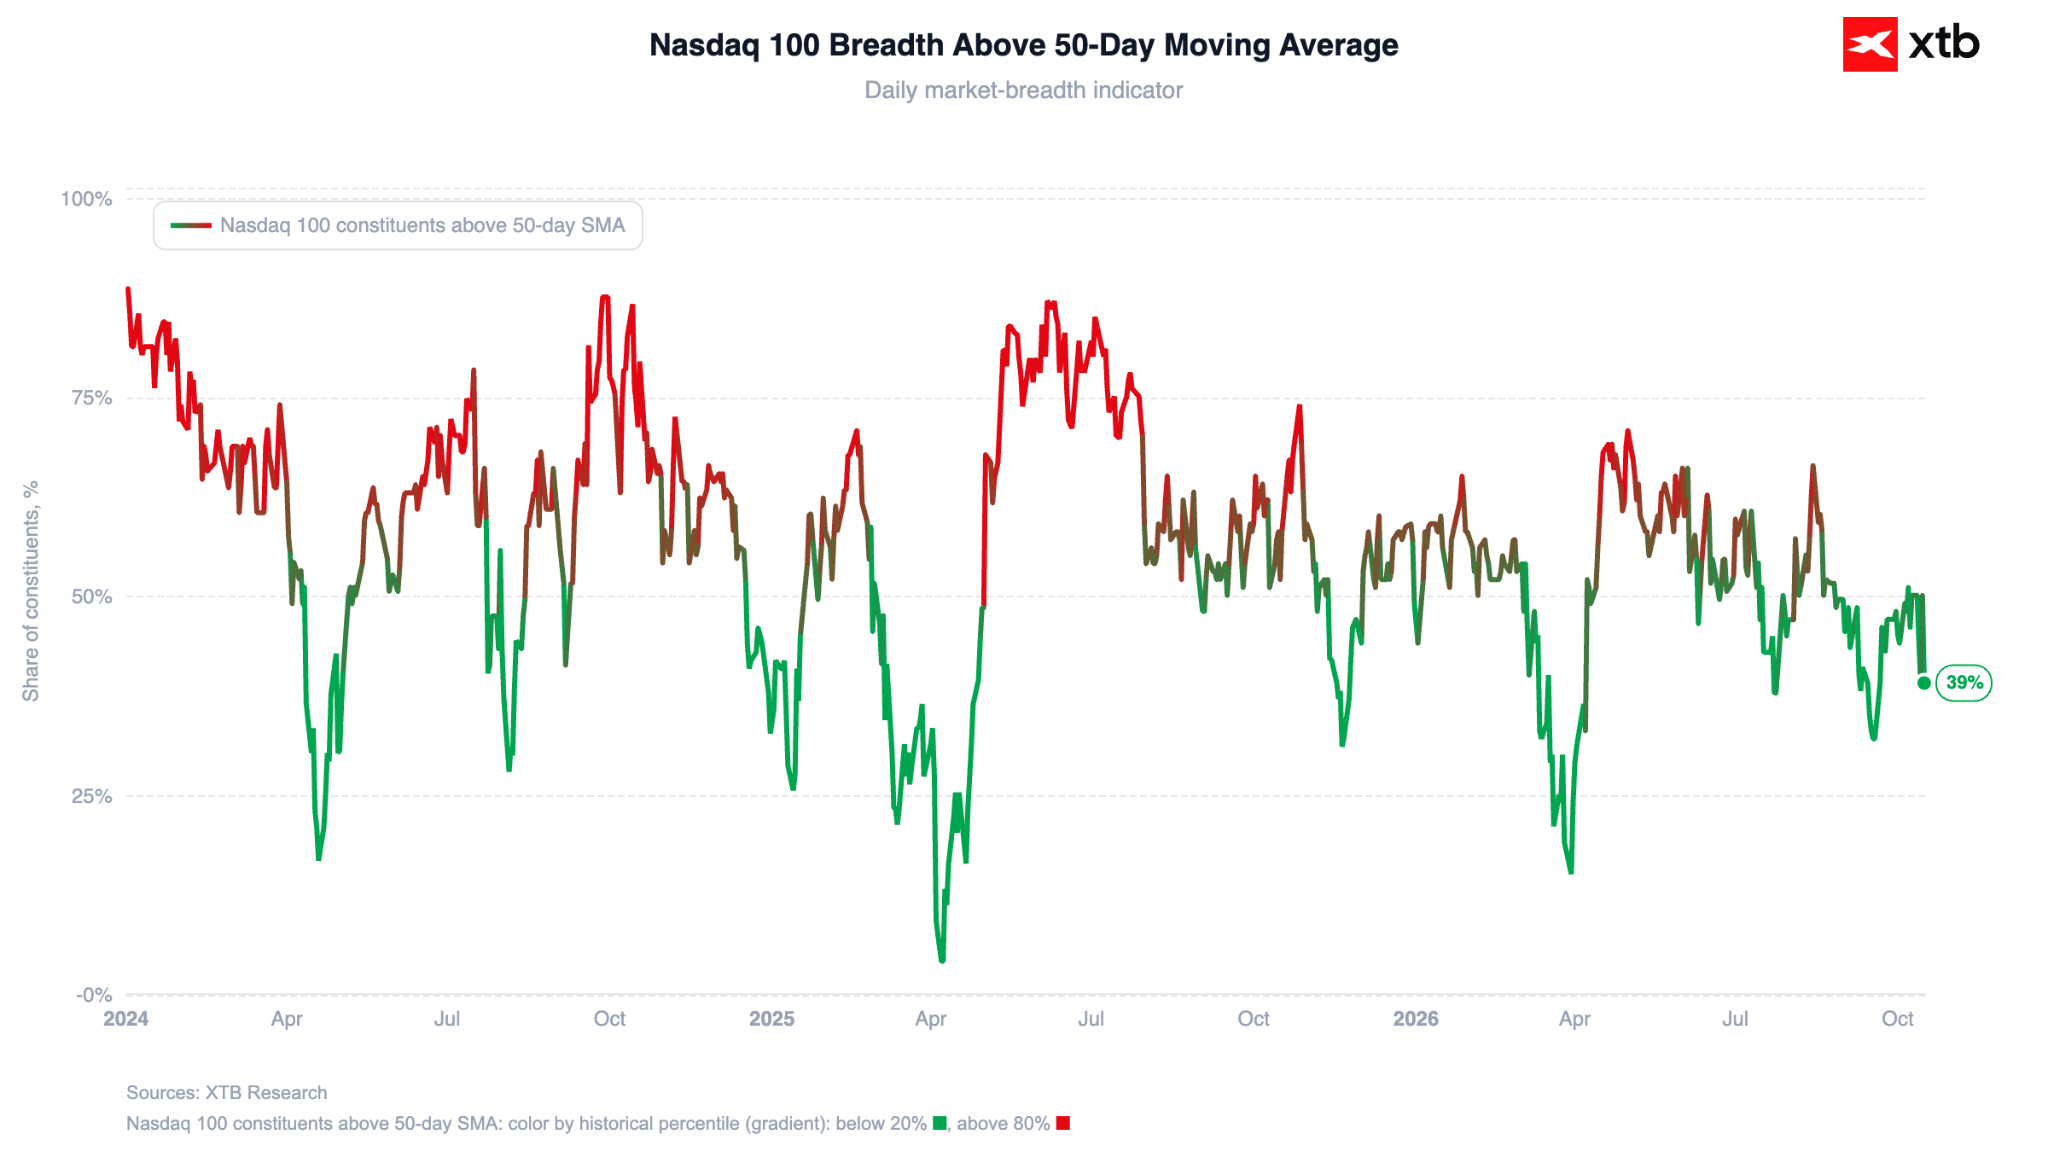
Last week was the worst for the Nasdaq since April 2025, when the highest tariffs on exports to the United States in over 100 years were announced.
Figure 1: Percentage of Nasdaq 100 Companies Above 50-Day Moving Average (2024 - 2026)
 Source: XTB Research, 19.10.2026
Today, we are seeing a slight improvement in market sentiment. Nasdaq 100 futures are up by more than 1%, and the S&P 500 has gained around 0.7%. Crude oil is retreating from five-month highs, whilst US bond yields remain substantially below their recent peaks.
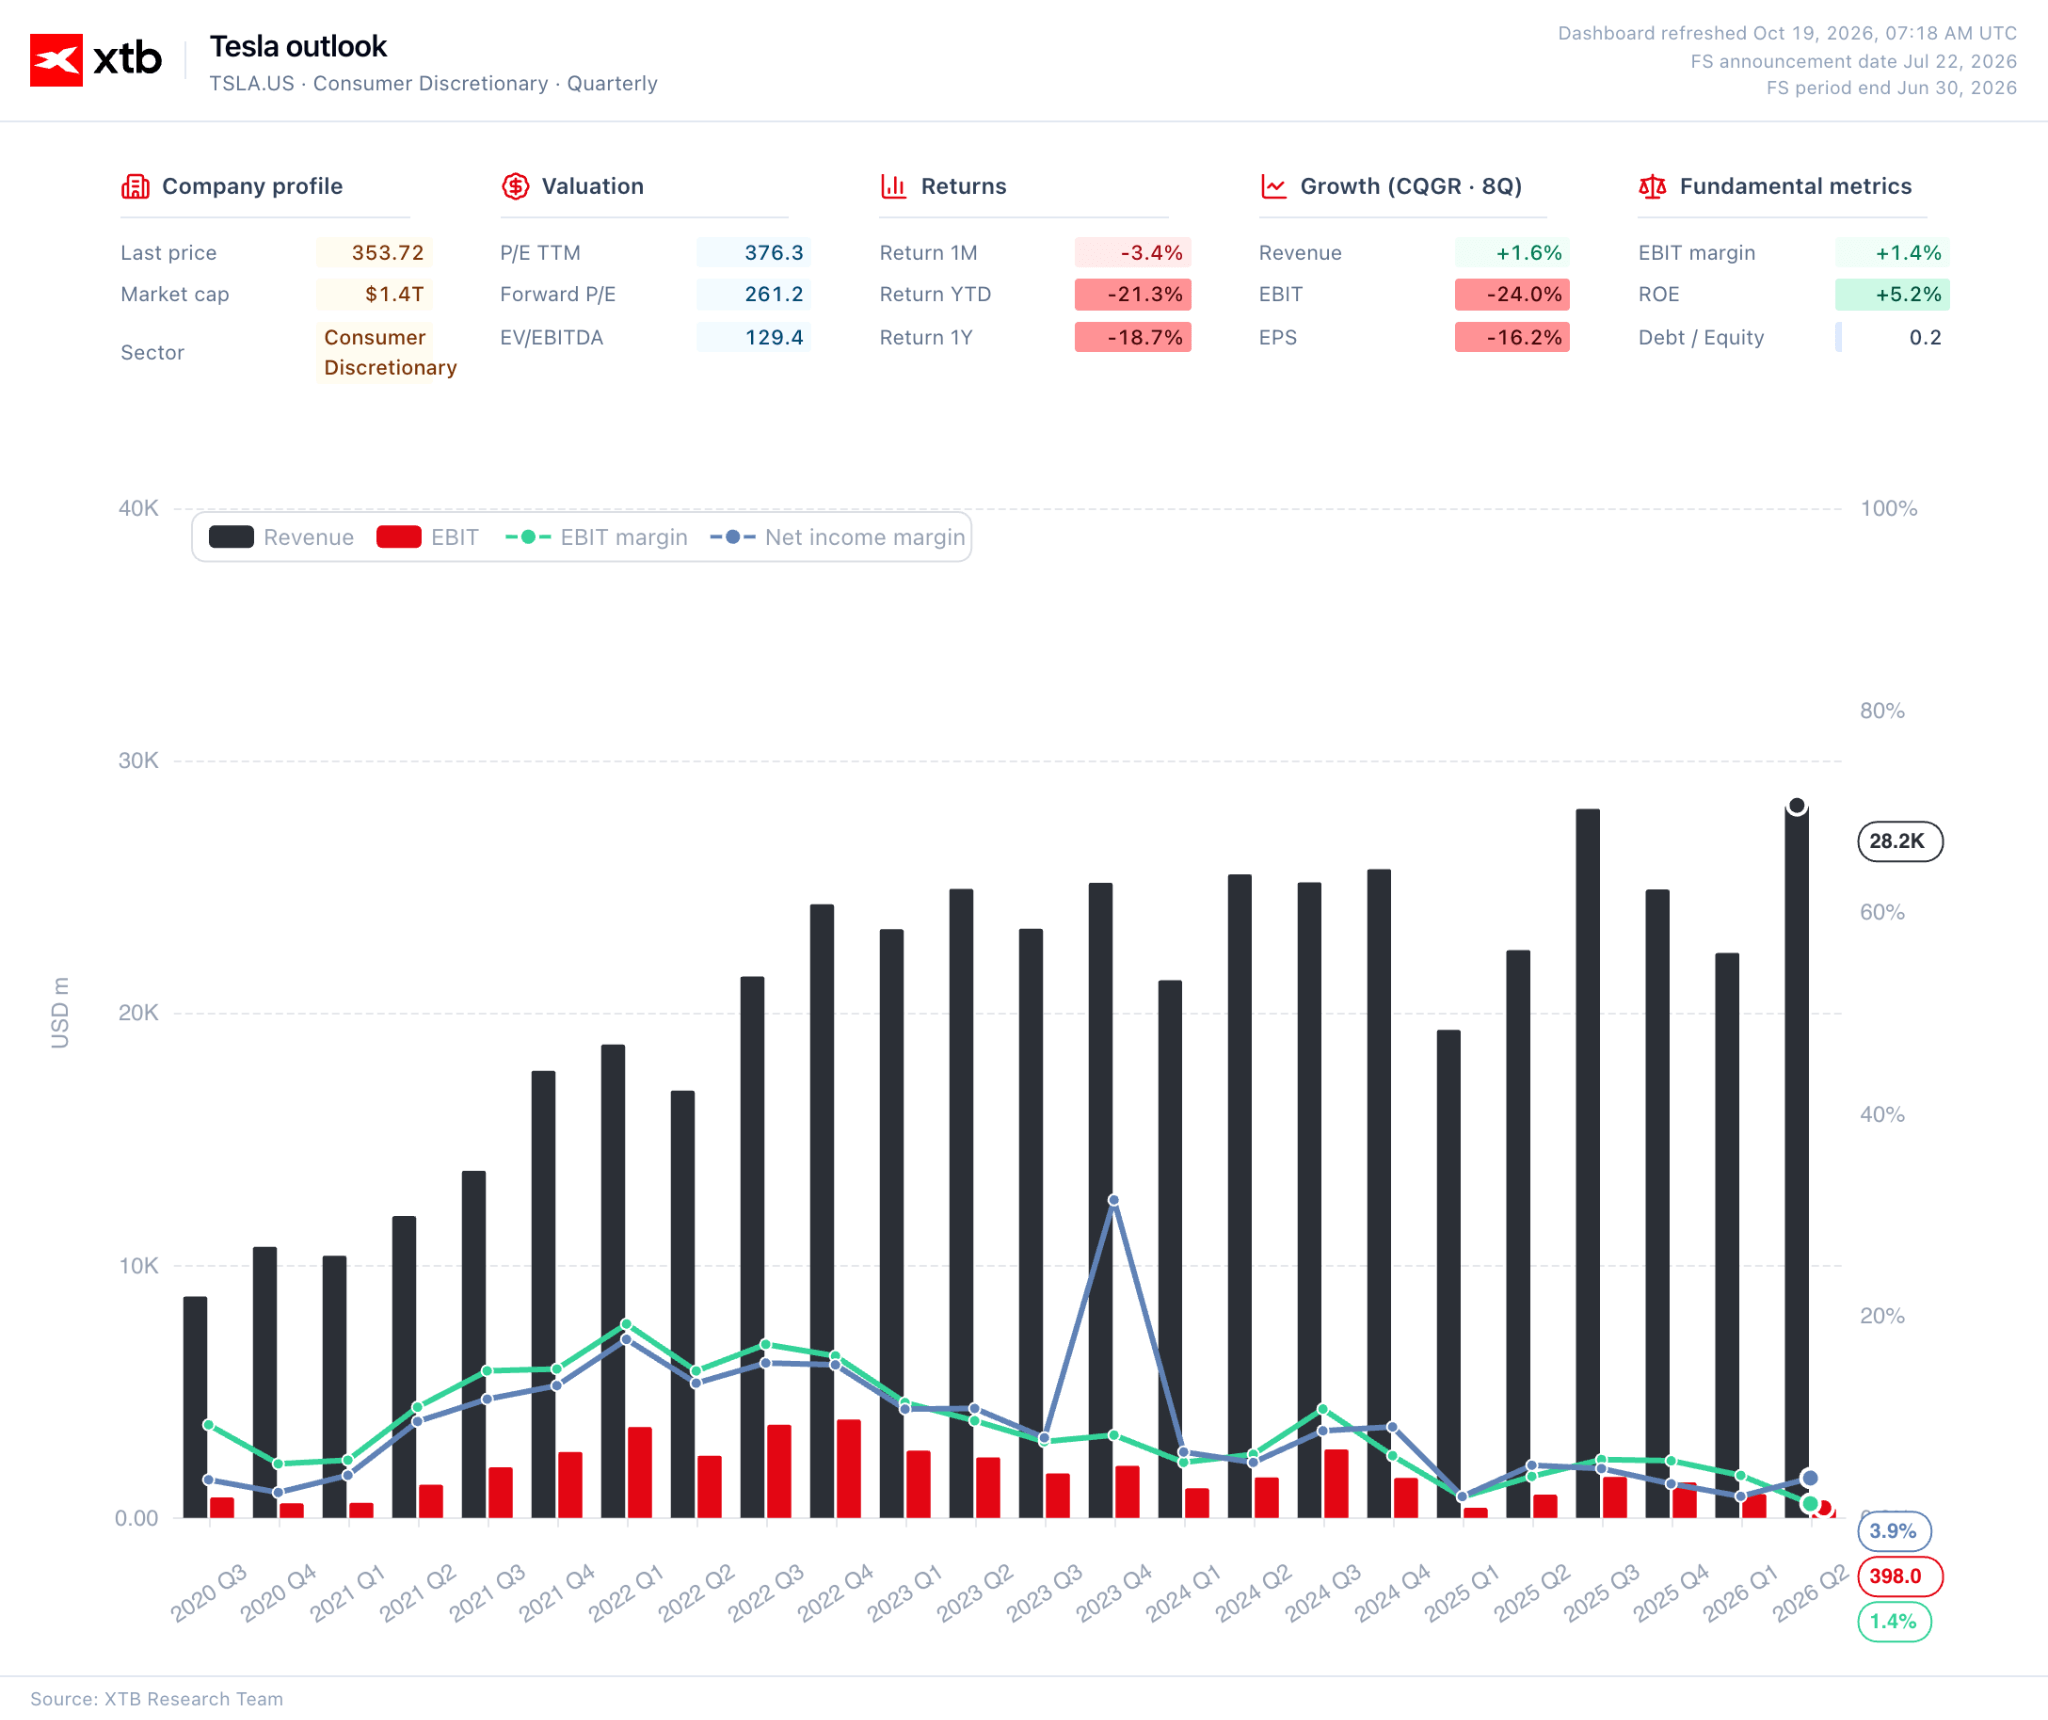
Ahead of us are quarterly results from Netflix, Tesla, Meta, and IBM, which will verify whether last week's sell-off in tech stocks was an overreaction or a warning signal for the entire "AI Play" theme.
Figure 2: Dashboard for Tesla (2024 - 2026)
 Source: XTB Research, 19.10.2026
🌏 Key Macroeconomic Releases
Monday
China
- Q3 GDP grew by 4.5% YoY (consensus: 4.4%, previous: 4.3%). On a quarterly basis, growth reached 1.2% (consensus: 1.1%).
- Industrial production rose by 5.5% YoY in September (consensus: 5.4%, previous: 5.2%).
- Retail sales accelerated to 1.1% YoY, comfortably above consensus (0.5%) and the previous reading (0.4%).
- Fixed asset investment fell by 7.2% YTD YoY (consensus: -7.3%).
- The unemployment rate fell to 5.2% from 5.3%.
- House prices continue to decline, albeit at a slower pace (-2.8% YoY vs -3.0%).
📆 Economic Calendar
Monday
- Canada: CPI Inflation for September
- Time: 1:30 PM
- Consensus: 3.2%
- Previous: 3.0%
Tuesday
- UK: Unemployment Rate (3 months to August)
- Time: 7:00 AM
- Consensus: 5.0%
- Previous: 4.9%
- US: Building Permits for September
- Time: 1:30 PM
- Consensus: 1.40m
- Previous: 1.403m
📆 Economic Calendar (Rest of the Week)
Tuesday, 20 October
- 07:00 AM UK – Unemployment Rate (ILO)
Wednesday, 21 October
- 07:00 AM UK – CPI Inflation YoY
- 03:30 PM US – DOE Crude Oil Inventories (Change)
Thursday, 22 October
- 01:30 PM US – Initial Jobless Claims
- 03:30 PM US – EIA Natural Gas Storage (Change)
Friday, 23 October
- 12:30 AM Japan – CPI Inflation YoY
- 09:00 AM Eurozone – Flash Services and Manufacturing PMI
- 02:45 PM US – Flash Services and Manufacturing PMI
- 03:00 PM US – University of Michigan Sentiment (Preliminary)
🗂️ Corporate Earnings Releases
- Fifth Third Bancorp ($FITB.US) – Before Market Open (BMO)
- Cleveland-Cliffs ($CLF.US) – Before Market Open (BMO)
- Steel Dynamics ($STLD.US) – After Market Close (AMC)
- Zions Bancorporation ($ZION.US) – After Market Close (AMC)
- W. R. Berkley ($WRB.US) – After Market Close (AMC)
- Western Alliance Bancorporation ($WAL.US) – After Market Close (AMC)
🗂️ Corporate Earnings Releases (Rest of the Week)
Tuesday: Netflix, Intuitive Surgical, General Electric, RTX, 3M, United Airlines, MSCI, Capital One, General Motors, Northrop Grumman.
Wednesday: Tesla, Meta Platforms, IBM, Lam Research, Texas Instruments, NextEra Energy, SAP, AT&T, QuantumScape, Abbott, Moody's, Philip Morris, Thermo Fisher, Southwest Airlines, Elevance Health.
Thursday: Spotify, Beyond Meat, Western Digital, Procter & Gamble, Lockheed Martin, Nokia, Honeywell, Blackstone, Deckers, Nasdaq, American Airlines, Newmont, Comfort Systems, Comcast, Union Pacific.
Friday: American Express, Schlumberger, Booz Allen Hamilton, Rithm Capital, Eni.
3 Markets to Watch
- OIL – Brent crude approached $112 on Friday before retreating by nearly 2% on Monday to around $108. US Energy Secretary Chris Wright reported that oil flows from the Persian Gulf have returned to approximately 80% of pre-conflict levels, although refined product supplies remain constrained. Meanwhile, regional incidents persist, including a damaged tanker in the Persian Gulf and a downed helicopter near the Yemen border, maintaining a risk premium.
- TNOTE – Following a drop of around 17 bps last week (the sharpest decline since April 2025, accompanying a 5.5% sell-off in the Nasdaq 100), bond yields settled near 5.06%. Treasury bonds appear to be resuming their role as a safe haven in the event of further disruption surrounding AI spending.
- US100 – After its worst week since the April tariff sell-off, focus shifts to quarterly earnings from Netflix, Tesla, Meta, and IBM. These results will determine whether last week's concerns over AI capital expenditure financing (including developments around CoreWeave and Anthropic) were a temporary wobble or the beginning of a broader correction in the artificial intelligence trade.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



Chart of the Day: What’s next for tech stocks after the deepest sell-off since April 2025? (19.10.2026)


Morning Wrap: Nasdaq rebounds ahead of Mag7 earnings, bonds regain favour, oil falls from peak (19.10.2026)


Sell-off in the semiconductor market 📉🖥️

TSMC breaks records once again driven by the AI boom
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.