



The morning is marked by assessments of the impact of yesterday’s Fed decision and a wave of earnings reports from Big Tech companies. As expected, the Federal Reserve kept rates unchanged, with hawkish dissenting votes from Hammack and Cook; however, Fed Chairman Kevin Warsh’s press conference did not yield any hawkish surprises—which weighed on the dollar and yields at the short end of the curve. Sentiment, however, is being dampened by disappointment with Alphabet, which—following weaker-than-expected results (below expectations for both revenue and profit)—is dragging down Nasdaq futures. Asia ended the session mixed, digesting the FOMC and tech company reports; the weakest performer was South Korea’s KOSPI, weighed down by Samsung’s results, which failed to meet sky-high expectations. Futures in Europe point to a flat open (Euro Stoxx 50 +0.1%).
Oil prices are looking interesting today, as they are falling despite the geopolitical premium seen so far—the reason being hopes for mediation following reports of intensive Iran-U.S. contacts through intermediaries and Vice President Vance’s outreach to Iranian hardliner Rezaei. This marks a reversal of the narrative from recent days, when the market was primarily pricing in the risk of escalation.
What's driving the market today:
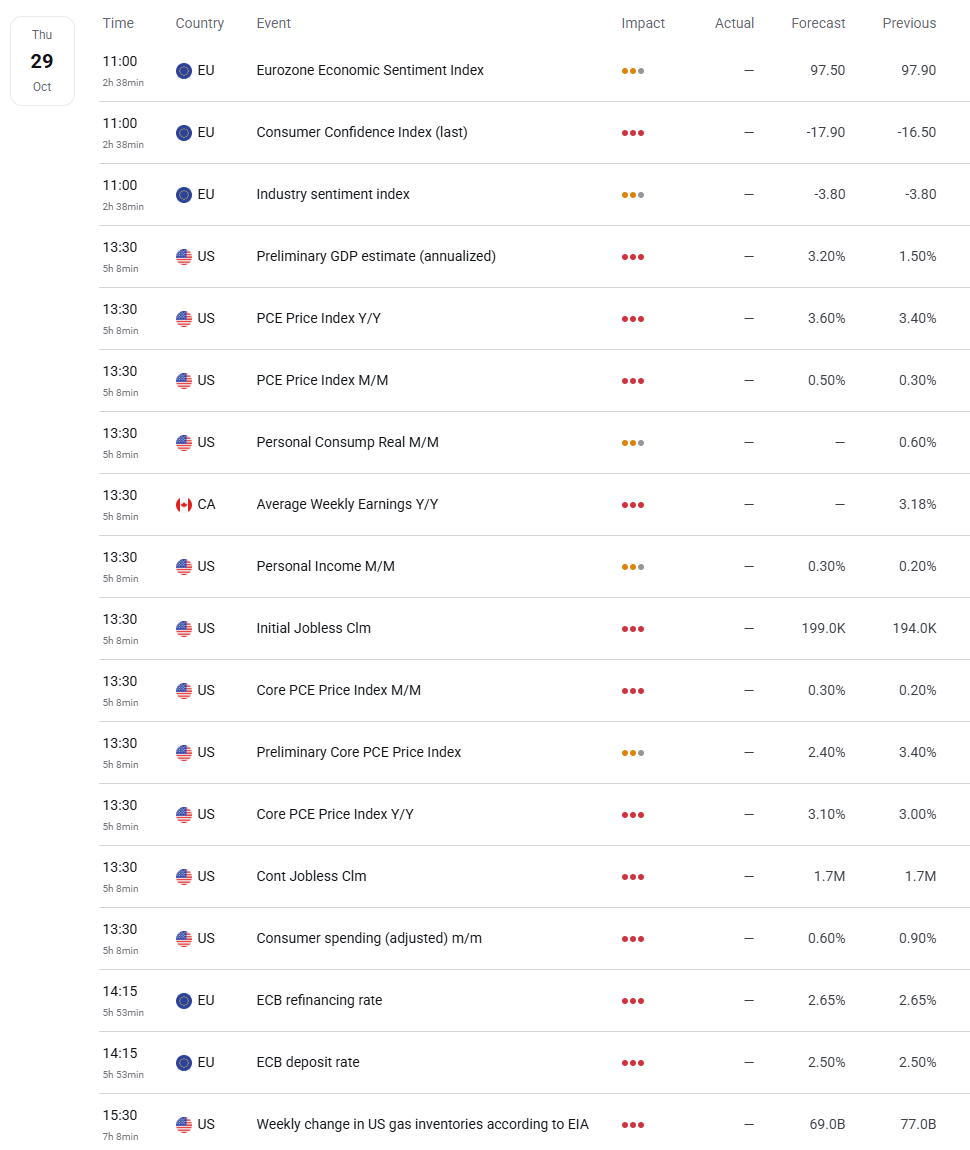
Today is packed with data releases. Before noon, at 11:00, we’ll see a full set of sentiment indicators from the eurozone (Economic Sentiment, Consumer Confidence, Industry Sentiment). The highlight, however, will be the U.S. session this afternoon at 13:30—the September reading of PCE inflation (the Fed’s preferred measure) will be released, along with the first estimate of Q3 GDP (annualized, consensus 3.2% vs. 1.5% previously) and weekly jobless claims (forecast: approx. 199,000). The consensus expects core PCE to rise by 0.3% MoM and 3.1% YoY, with consumer spending up 0.5% MoM. Following Warsha’s dovish press conference, the balance of risks is tilting toward a reaction to a weaker reading—a strong result would not change much, but a weaker one could intensify doubts about the tightening scenario.
At 2:15 p.m., the ECB will announce its interest rate decision — The refinancing rate is expected to remain at 2.65% and the deposit rate at 2.50%, so the tone of President Lagarde’s press conference will be key. The day will close at 3:30 p.m. with the EIA’s gas inventory report.
The earnings season also sets the pace. Reports from Europe have already come in—oil companies posted strong results (Shell with EPS of $1.93 versus an expected $1.79 and operating cash flow of $21 billion; TotalEnergies exceeded forecasts across the board), while Lloyds and Adidas posted solid results; Volkswagen, however, disappointed with an operating loss of $5.86 billion and lower margins. On Wall Street, ahead of the session, Eli Lilly (LLY.US) , Mastercard (MA.US), Caterpillar, and Merck; after the session, key reports will come from Amazon (AMZN.US)—particularly AWS growth and comments on AI capex—and Intel (INTC.US) . Following Alphabet’s weak performance, it is now up to Amazon to take on the thankless task of restoring broader confidence in the tech sector.
In the background, it will be worth watching whether the Fed’s dovish tone and a possible easing of tensions surrounding Iran will offset the disappointment over Alphabet, and how the market will react to the PCE/GDP data just ahead of the ECB’s decision.


Daily Summary: Bloody Thursday on Wall Street: Nasdaq Leads the Sell-Off

Silver falls, testing the $52 Level



US Open: Alphabet Sends Nasdaq Plunging. Strong US Data Fails to Rescue Wall Street


ECB Holds Rates Unchanged💶 EURUSD down 📉
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.