


This morning’s trading is marked by a global flight from risk, which had its epicenter in Asia overnight. The sell-off in the tech sector on Wall Street spilled over to the markets in Korea and Japan, and futures for major indices are heading into Europe in negative territory. The sharpest decline is being seen in Japan’s JP225 (-2.59%), which is being dragged down by a sell-off in memory and semiconductor equipment manufacturers. The tech-heavy US100 (-1.07%) is also performing poorly, while the broader US500 (-0.32%) and European indices (EU50 -0.50%, DE40 -0.18%) are holding up slightly better—this is a typical picture of a trading session in which companies sensitive to the cost of financing AI expansion are under the most pressure.
At the other end of the spectrum are precious metals. GOLD (+0.93%) is consolidating its position as a safe haven around $4,142 per ounce, as is SILVER (+1.38%), driven by a weaker dollar and falling bond yields. The dollar index (USDIDX -0.40%) is pulling back after reaching a multi-month high, which is supporting major currency pairs—EURUSD is up 0.52% to 1.1210, and GBPUSD is up 0.48% . Interestingly, oil prices are falling despite tensions in the Strait of Hormuz—OIL is down 2.05%, and OIL.WTI is down 1.38%, which the market attributes to reports of a possible easing of sanctions on the “shadow fleet.” The risk-off sentiment is also affecting cryptocurrencies—BITCOIN -0.83% (approx. $80,900).
What's driving the market today:
Among the morning data releases, the spotlight was on the UK’s GDP for August, which came in better than expected—the economy grew by 0.1% MoM (forecast: -0.1%) and as much as 2.1% YoY versus the expected 1.7%, the highest rate since August 2022. The pound rose in response, and gilt yields fell across the entire yield curve. On the other hand, data from Australia disappointed—employment fell by 39,300 jobs (forecast: +20,000), which weighed on the Australian dollar and reduced expectations for an RBA rate hike in November.
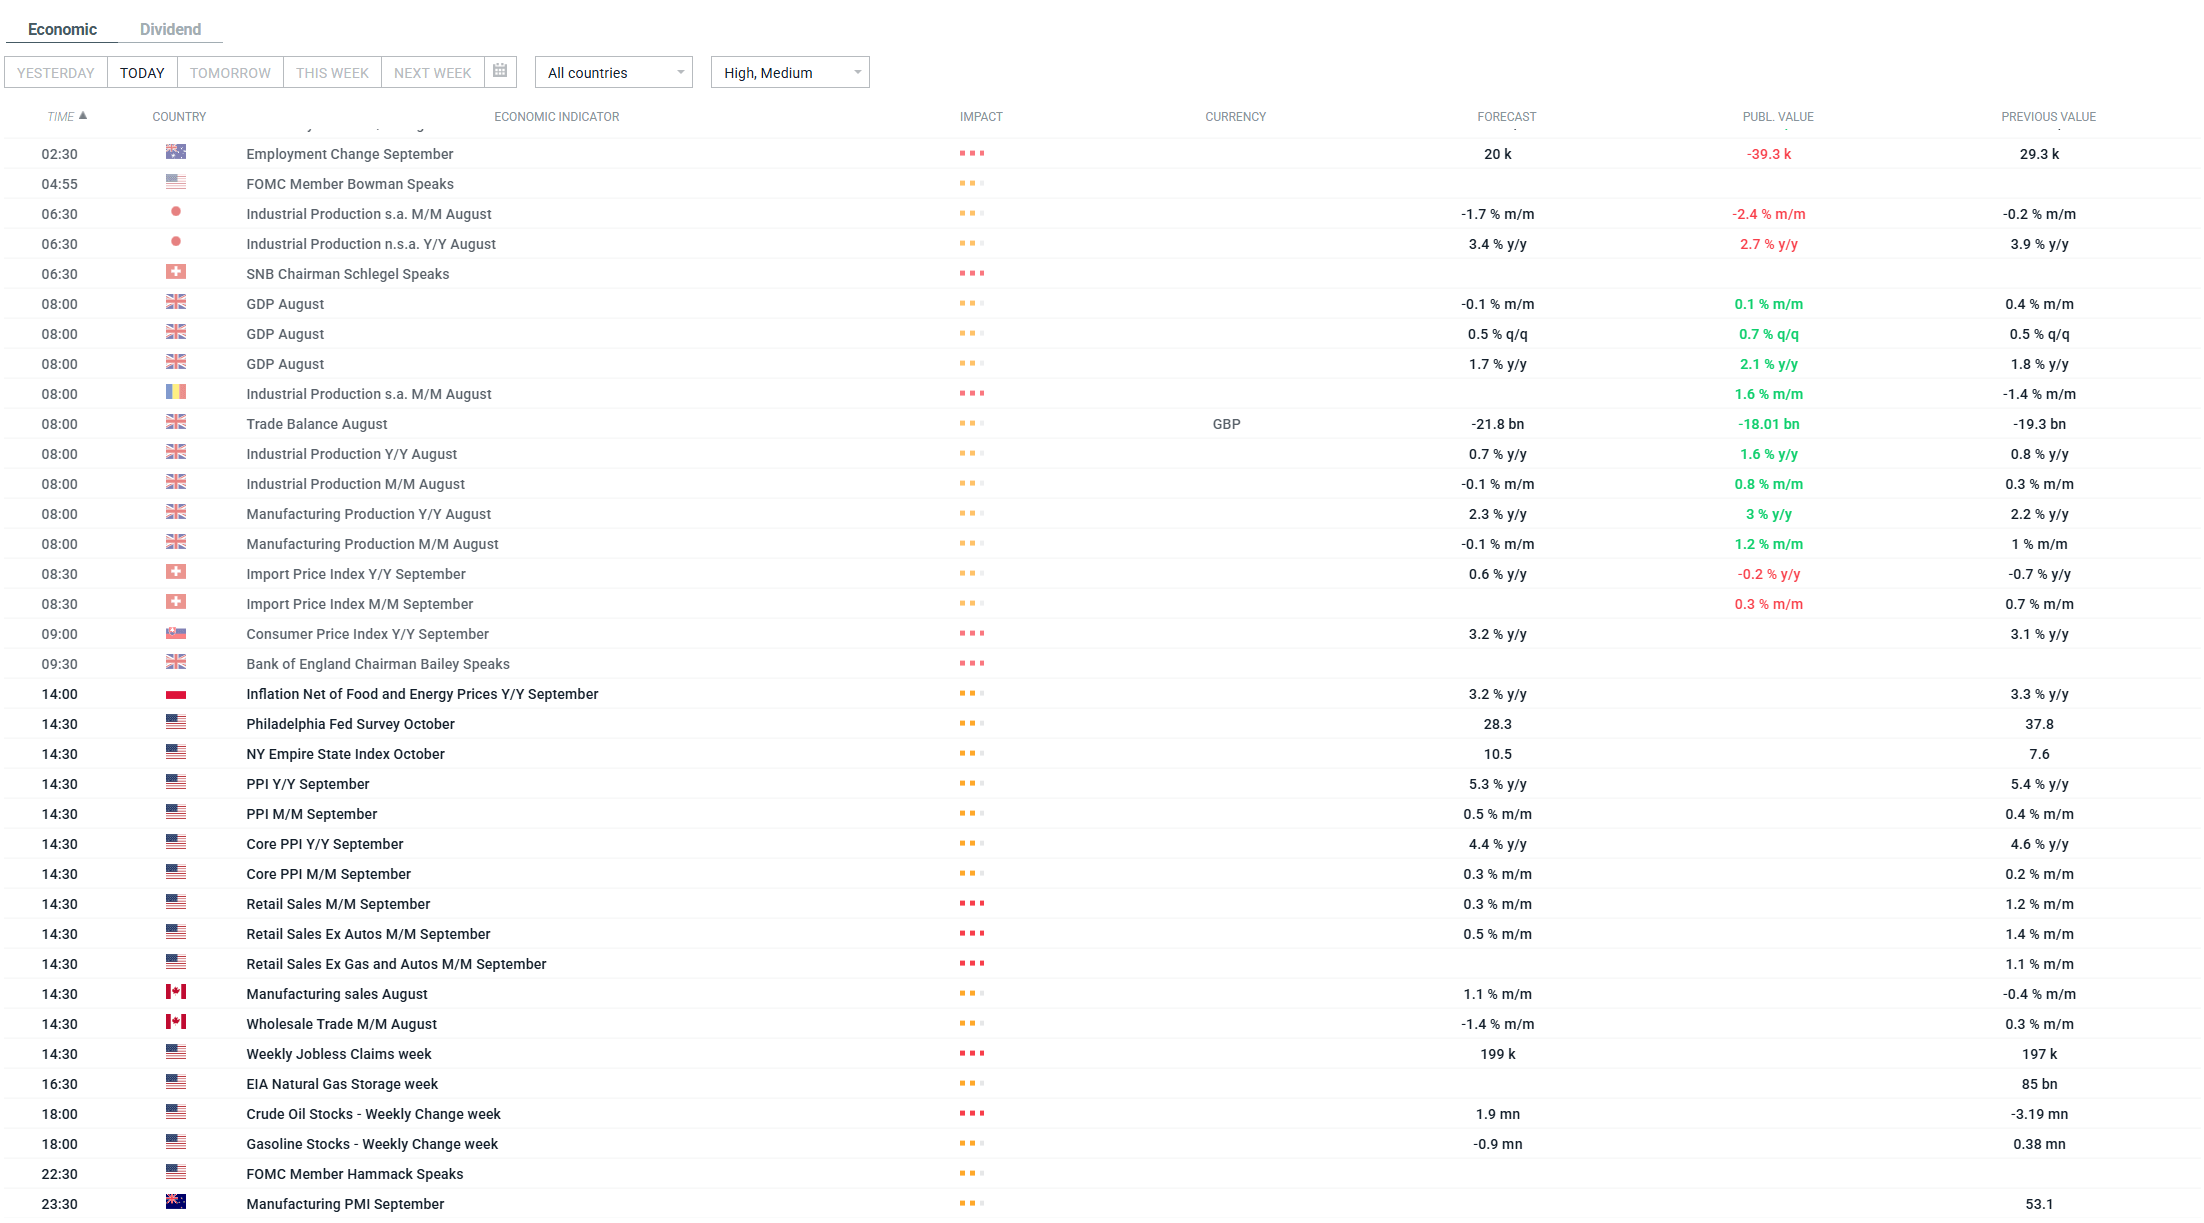
The key macroeconomic release is still ahead of us—at 2:30 p.m., we’ll see a full set of U.S. data: September’s PPI, retail sales, and weekly unemployment insurance claims. Following Tuesday’s hotter-than-expected CPI reading, these figures could further tip the balance of expectations regarding the Fed, with the market currently pricing in about a 29% chance of an October rate hike. It’s also worth keeping an eye on a series of speeches by Fed officials in Bangkok, including Federal Reserve Chairman Kevin Warsh.
On the earnings front, TSMC delivered a positive signal for the AI sector—its sixth consecutive record quarter, with net income up 68.7% year-over-year ($23.7 billion) and raised revenue forecasts for 2026. This is a strong counterargument to growing doubts about the profitability of AI spending, though for now it is not enough to reverse the morning’s defensive sentiment across the broader market.


Market Wrap: Rebound in China and Falling Oil Prices, France Leads EU Declines



Chart of the Day: What’s next for tech stocks after the deepest sell-off since April 2025? (19.10.2026)


Optimism Returns to Asia❔


Economic Calendar: Big tech earnings week and test for the AI rally (19.10.2026)
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.