


European stock markets are trying to limit losses after a sharp sell-off in Asian technology shares. In the futures market, the UK and Swiss indices are performing best, up around 0.7%. Moderate gains of about 0.4% are also seen in SPA35 and FRA40. The weakest performers in today’s session are futures in Poland and Germany, where declines reach about 0.3%.
- The main drag on sentiment remains yesterday’s US inflation release. September CPI rose by 0.6% month over month and 3.7% year over year, again reinforcing expectations of a restrictive Fed policy stance. Core inflation came in at 2.6% year over year. For the tech sector, this revives the question of whether the pace of future earnings growth justifies current valuations with such a high cost of financing.
- The strongest reaction was in Asia. South Korea’s Kospi closed down 7.6%, and Japan’s Nikkei 225 lost about 4.9%. Samsung and SK Hynix shares fell by 9.5% and 11.1%, respectively.
- At the same time, capital is returning to government bonds. The yield on US 10-year Treasuries is down by about 10 to 11 basis points, to around 5.08%. German debt prices are also rising. This setup can be read as a search for safety: the drop in yields is accompanying concerns about funding AI investment rather than a clear improvement in the economic outlook.
Company News
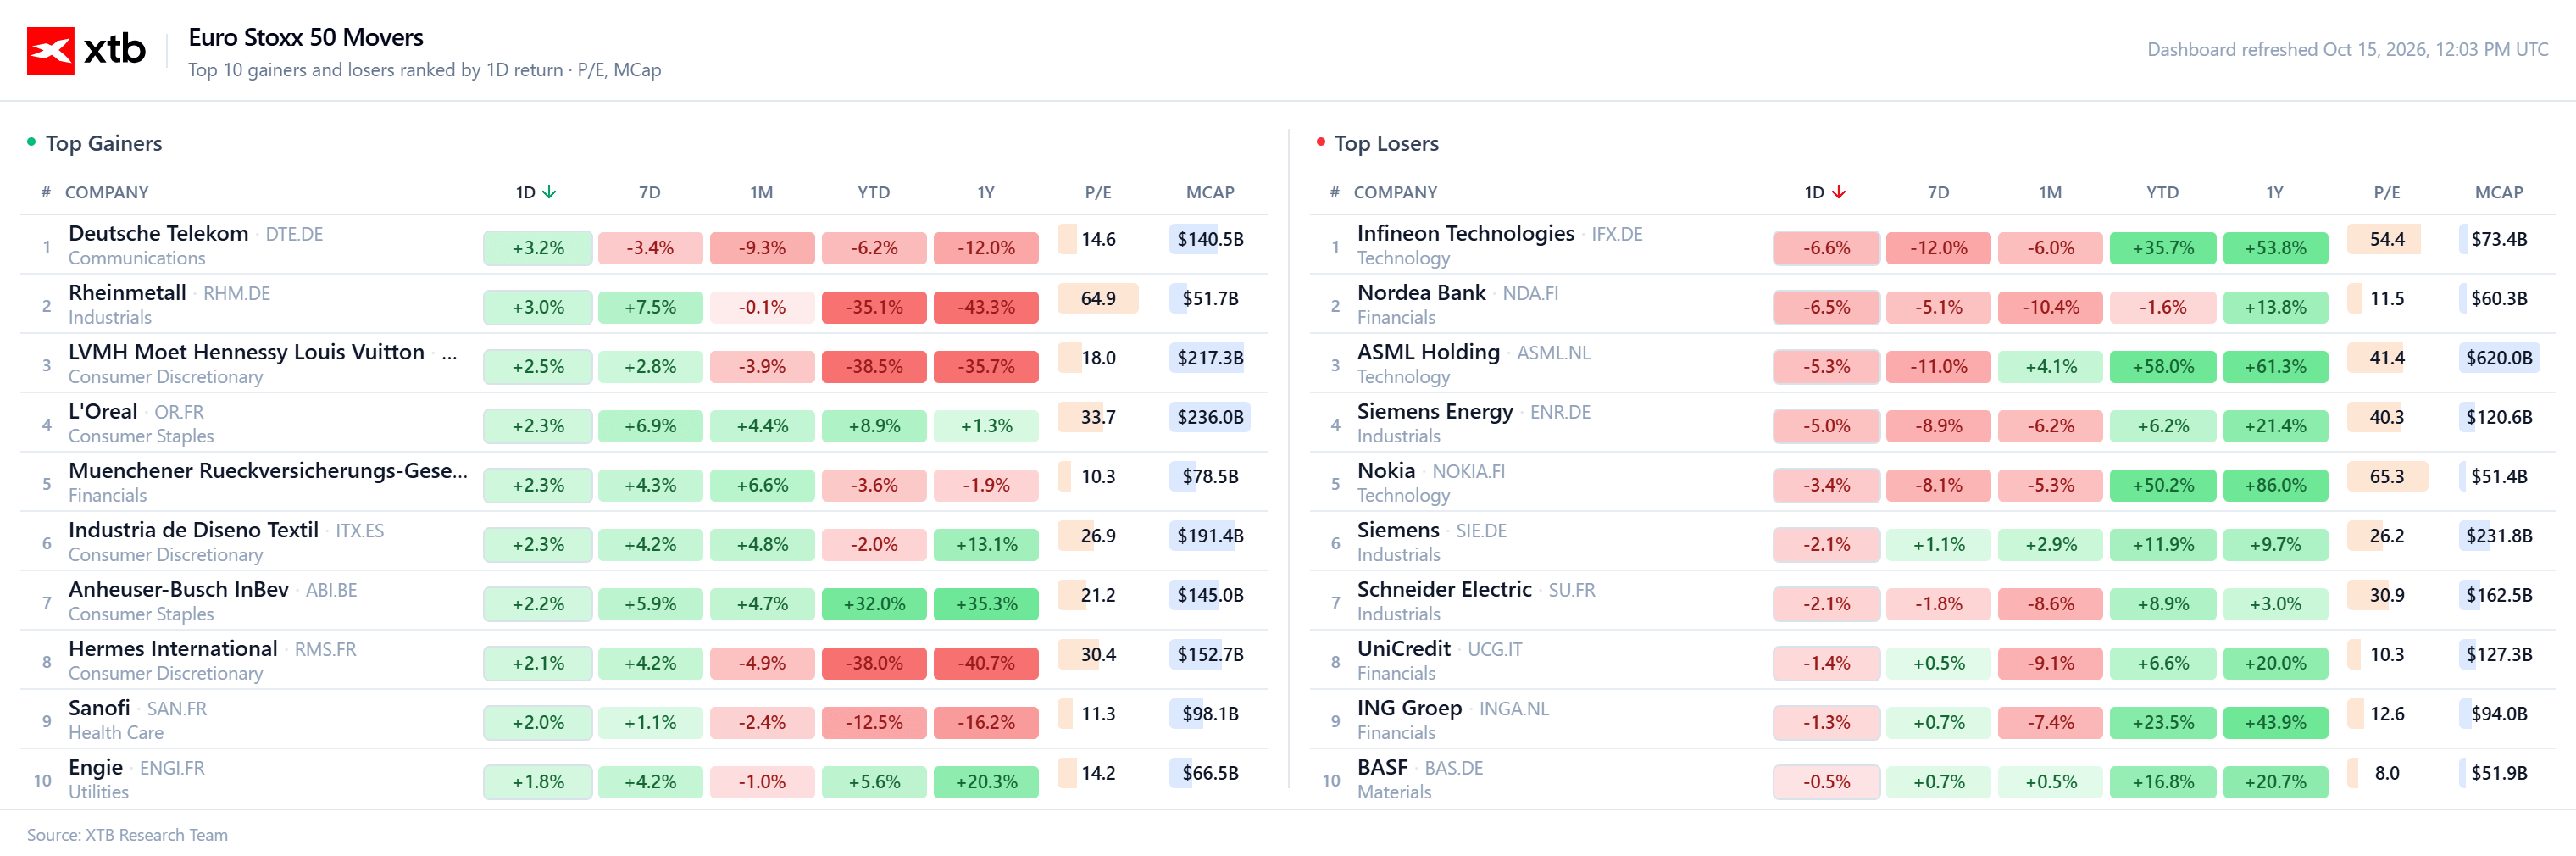
- ASML (ASML.NL): Shares are down about 4%. The lithography equipment maker is being pulled into the broader semiconductor sell-off, despite a positive tone in yesterday’s business update.
- Ericsson (ERIC.US): The stock is up about 8%. Adjusted EBITA came in at SEK 10.1bn versus SEK 7.87bn expected, and sales reached SEK 59.5bn versus a consensus of SEK 55.4bn. The company warns, however, that rising component costs will pressure margins next year as well.
- Schneider Electric (SU.FR) and Legrand (LR.FR): Shares are down about 3.8% and 3.4%, respectively. The sell-off is also hitting providers of electrical infrastructure for data centers, showing that pressure extends beyond chipmakers themselves.
- Mondi (MNDI.UK): Shares fall about 10.8%. Paper price increases failed to convince investors that the company is effectively offsetting cost pressure. The quarterly underlying result was EUR 196m; the improvement versus the previous quarter benefited from a low base tied to the earlier write-down.
- Antofagasta (ANTO.UK): Copper production rose 7% quarter over quarter to 151.9k tonnes, but the 2027 outlook disappoints: the 630k to 690k tonne range does not provide the expected growth boost. An additional headwind is an increase in the cash cost forecast due to more expensive diesel. Shares are down about 6%.
- TSMC (TSM.US): Third-quarter net profit rose 69% to a record TWD 763.1bn, beating expectations. The company raised its forecast for this year’s revenue growth to about 44%, but signaled caution in planning for 2027. Shares in Taipei closed the session down 2%, before the results were published.
Forex
- The dollar is giving back part of its earlier strength. EUR/USD climbs back above 1.21, up about 0.6%, after dropping to 1.11 yesterday. The Swiss franc benefits from weaker risk appetite and narrowing yield differentials, with EUR/CHF falling toward 0.93.
- The pound gains about 0.5% to nearly USD 1.32.
- The Australian dollar is weaker: AUD/USD falls toward 0.6954 after an unexpected drop in September employment of 39.3k.
Commodities
- Brent crude trades around USD 104.9 per barrel, down more than 1%, while WTI is near USD 95. Prices are pressured by reports that Washington is considering easing restrictions on some tankers in Russia’s “shadow fleet.” Supply risks remain high, however, given attacks on shipping near the Strait of Hormuz and renewed Ukrainian strikes on Russian refineries.
- Gold is benefiting from a weaker dollar and falling yields. In late-morning trading, the spot price rose about 1.2% to USD 4,156 per ounce. Silver gained about 1.5% to USD 56.7.
DE40 Analysis (D1)
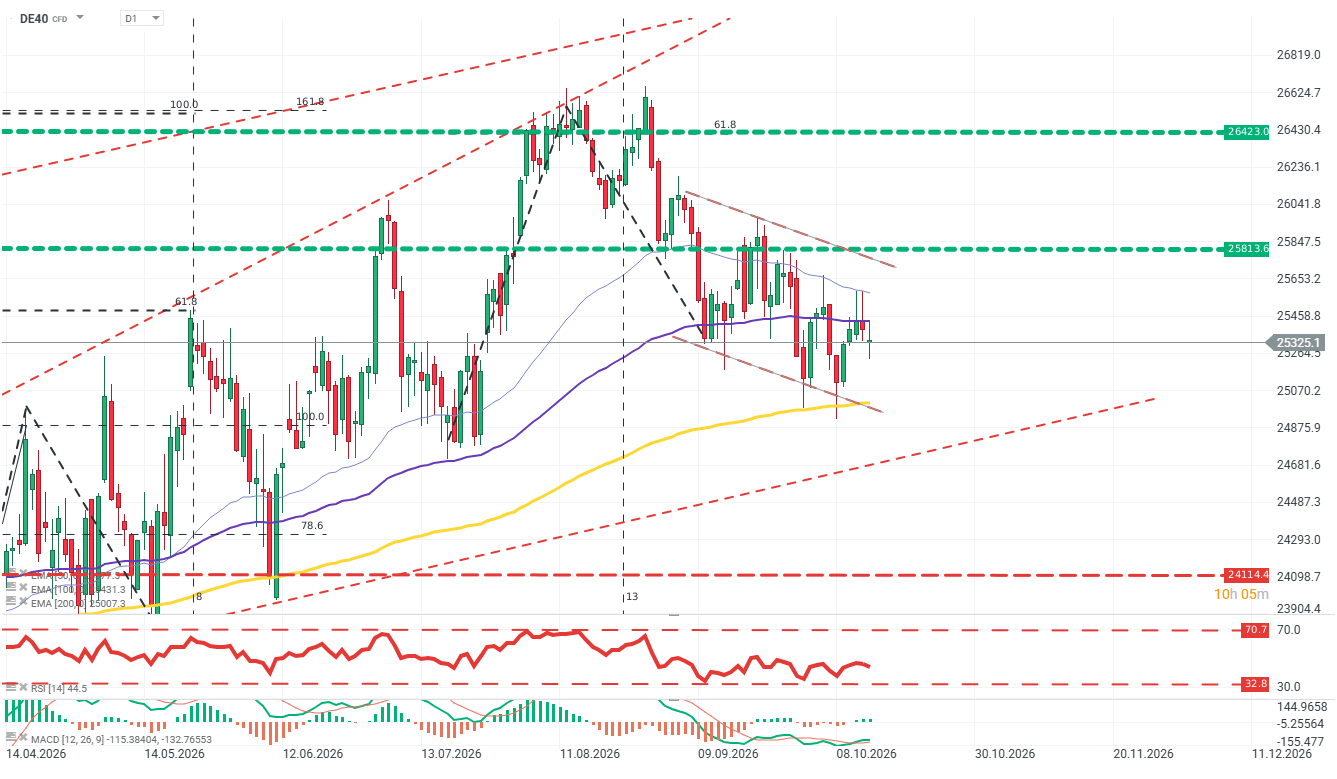
The DE40 index is moving within a short-term, parallel descending channel. The key resistance zone is around 25,000 points, where the EMA200 line is also located. Source: xStation5
Crypto
- The cryptocurrency market remains under clear pressure.
- Bitcoin trades around USD 80.8k, down about 3% over 24 hours.
- Ethereum falls about 5.6% to USD 2,361.
- Solana drops about 4.4% to USD 102.3.


Market wrap: European indices rebound 🔼 Defence stocks on the rise


🔼 EURUSD continues to rebound


TSMC in Talks with Elon Musk Over Terafab


Chart of the Day: NATGAS - Are there chances for a seasonal rebound amid warm weather?
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.