


Red spread across nearly all major trading floors: the German DAX is down by around 1.8%, the French CAC 40 is losing close to 1.2%, the broad Euro Stoxx 50 index is down by nearly 0.8%, and Warsaw's WIG20 is slipping by about 1.7%. What is more, European retail sales tumbled by around 0.7% month over month in September, against expectations of a minor correction of around -0.1%, highlighting a clear slowdown in eurozone consumption. Thursday's sell-off across the Atlantic directly hit sentiment on the Old Continent.
Investor anxiety is being fueled by the tech debt market. Dutch bank ING has put up for auction a loan portfolio valued at around 500 million USD, issued for the construction of artificial intelligence data centers, including a tranche of around 25 million USD tied to the massive Stargate project in New Mexico. This is an unprecedented signal that concerns over returns on huge capital expenditures in AI infrastructure and potential regulatory tightening after the US elections are spilling over from equities directly into the balance sheets of financial institutions. Despite the pessimism in Europe, US futures are attempting to recover today, with the exception of Dow Jones futures, which continue to show relative weakness.
FX Market
- EURUSD: Quotes are falling due to weaker retail sales in the eurozone and anticipation ahead of US labor market data (decline of around 0.5%).
- USDJPY: The dollar gains against the yen on broad demand for the US currency, pushing speculation about BoJ monetary tightening into the background (rate increase of over 0.5%).
- USDPLN: The zloty loses ground following the global dollar appreciation and worsening sentiment across emerging markets (PLN weakening of nearly 0.5%).
Commodities Market
- Crude oil (Brent and WTI posting declines exceeding 1%): Selling pressure gathers momentum once again, deepening the week-long sell-off. Concerns over weakening global demand outweigh supply-side risk factors, such as tensions around the Strait of Hormuz and drone attacks on another Russian refinery.
- Natural gas: In Europe (NATGAS.EU), the sell-off continues, with the commodity down around 3% today (extending its weekly decline to around -15%), while in the US, the Henry Hub Natural Gas contract is seeing a modest rebound of around +1.5%.
- Precious metals: Gold consolidates near 4070 USD per ounce (down by around 0.4% following a strong weekly gain of over 5%), while silver gains around 0.5%, defending the 52 USD level.
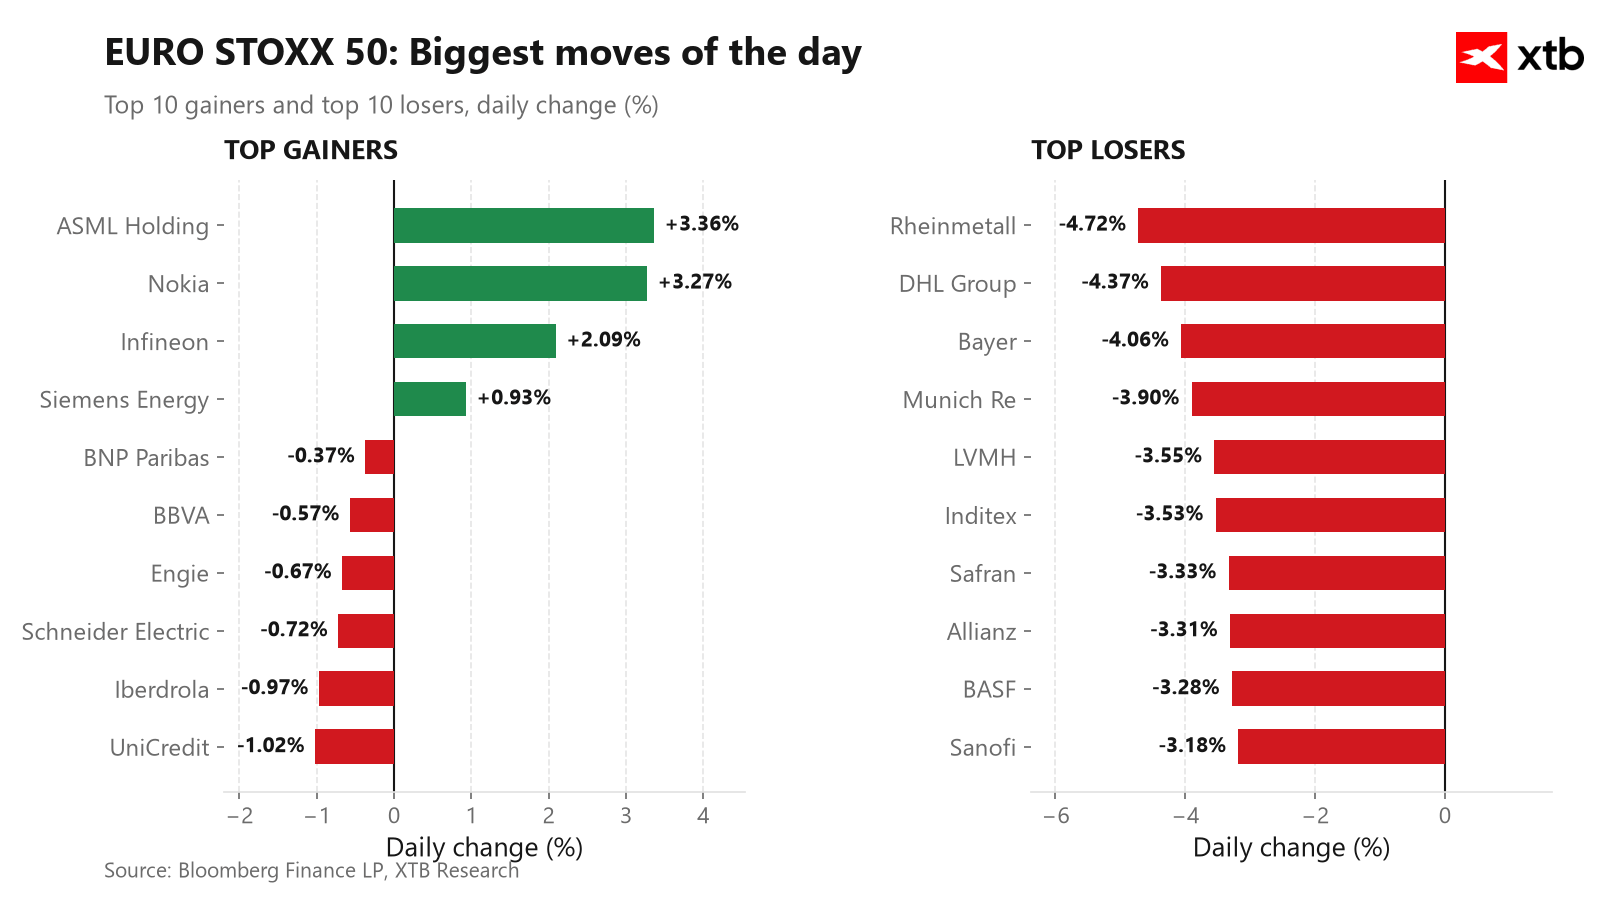
Top Gainers:
- ASML Holding (ASML.NL): Dynamic rebound following the tech sell-off, with investors returning to the lithography monopoly amid ongoing strong demand for AI-related systems. The market is using the earlier drop as a buying opportunity (gain of over 3.5%).
- Nokia (NOKIA.FI): Optimism surrounding the commercialization of AI telecom solutions and projections of sharp increases in network traffic. The company is emerging as a cheaper, defensive alternative for playing the AI infrastructure boom (gain of around 3%).
- Infineon (IFX.DE): Rebound alongside the broader European chip market after Thursday's slump, supported by stable outlooks for the automotive sector. Capital is selectively returning to oversold leaders in industrial electronics (shares up by over 1%).
Top Losers:
- Rheinmetall (RHM.DE): Cut to full-year revenue and margin guidance caused by delays in ammunition and equipment deliveries (sell-off reaching 4.5%).
- DHL Group (DHL.DE): Profit-taking following the release of the Q3 financial report against weak European retail sales data. Even solid operating figures failed to protect the cyclical stock from capital outflows (drop of close to 4.5%).
- Bayer (BAYN.DE): Weakness in the Crop Science agricultural division paired with persistent concerns over massive litigation expenses in the US. The absence of a quick resolution to legal disputes continues to drag on the stock price (drop of around 4%).
Macroeconomic Data
Markets are awaiting the release of a batch of US economic data. Investor attention is focused not only on non-farm payrolls (NFP) numbers; today we will also learn the unemployment rate, wage growth, and consumer sentiment measured by the University of Michigan index. Significantly stronger jobs and wage data could stoke concerns over persistent inflation and prompt the Fed to remain cautious, though parts of the market could interpret this simply as evidence of economic resilience. On the other hand, a moderate cooling of the labor market coupled with stable consumer sentiment would provide central banks with arguments for a gradual easing of monetary rhetoric. However, the risk remains a reading that falls too sharply, in which case investor focus would rapidly shift from battling inflation to fears of a slowdown.
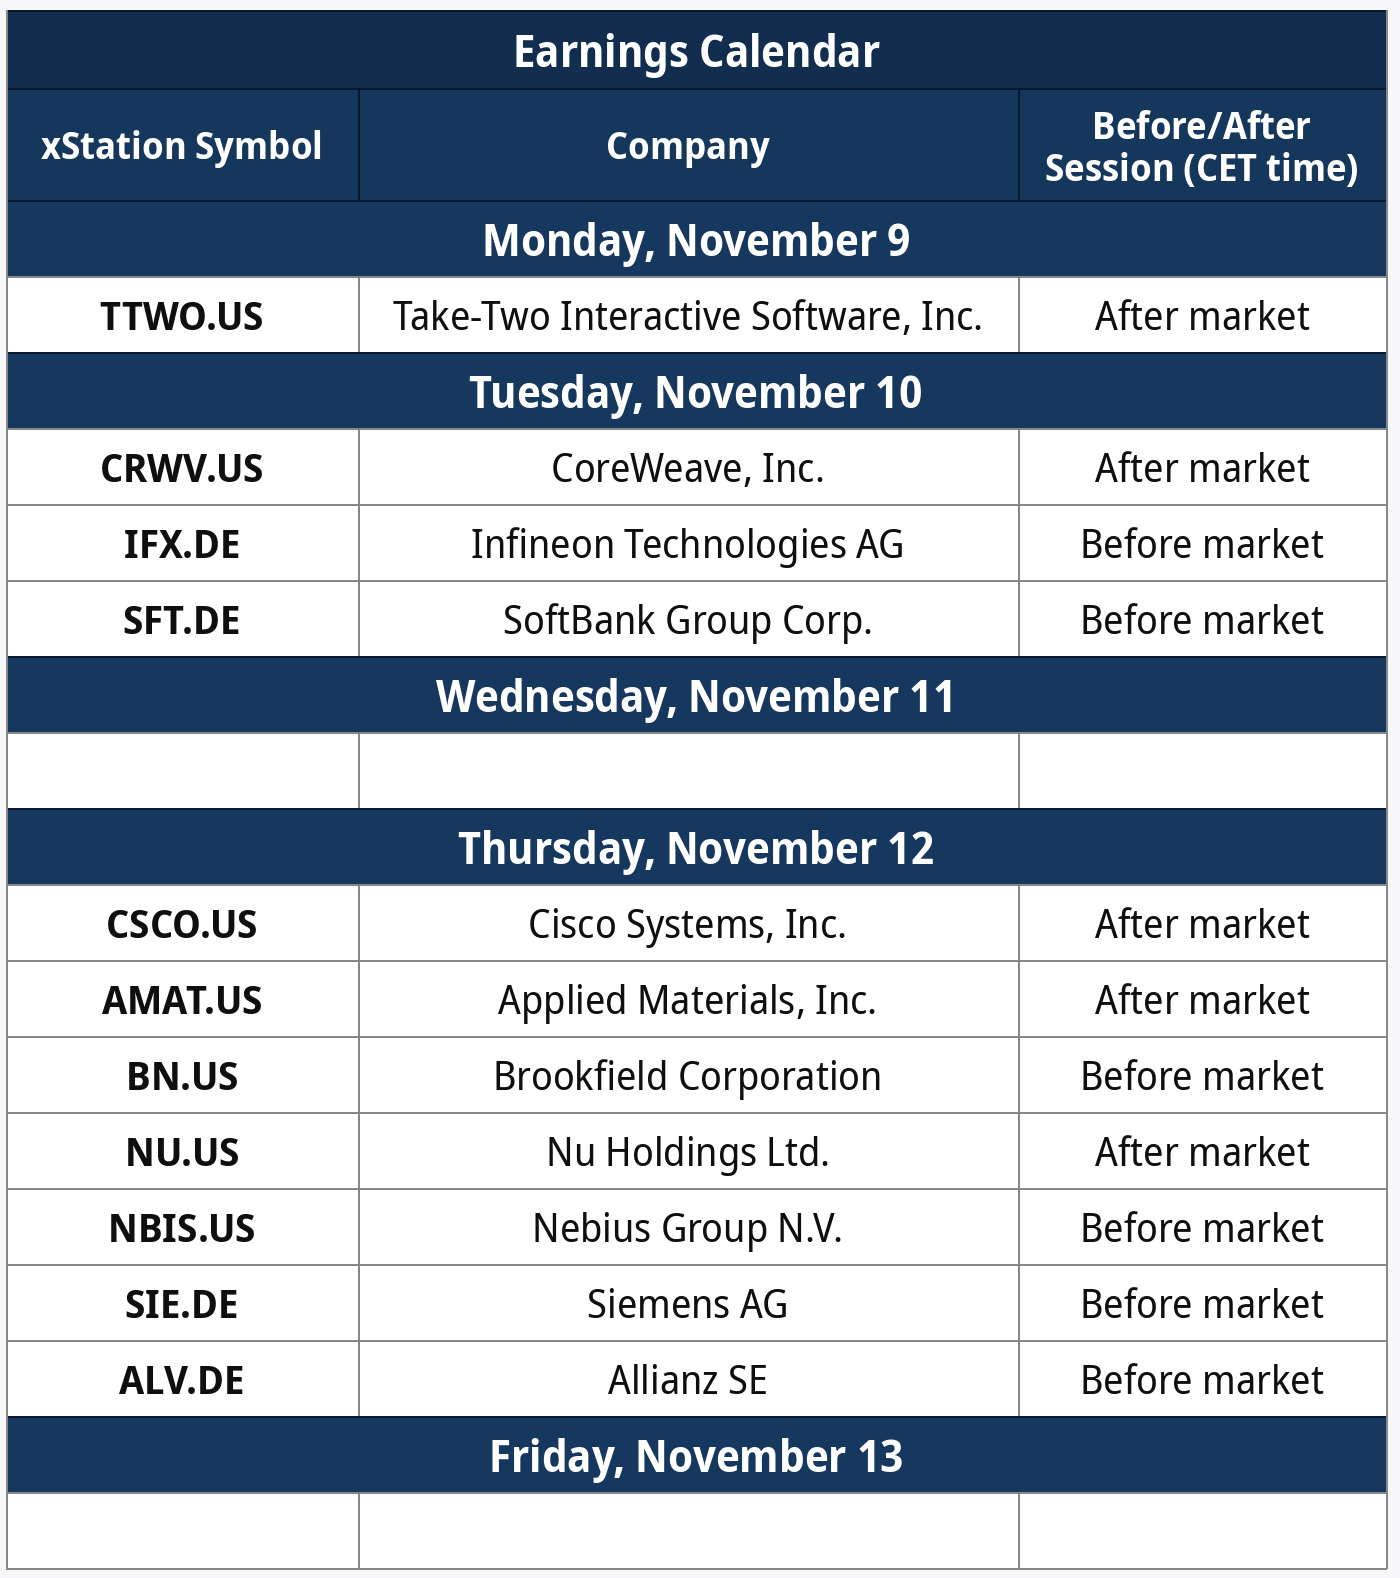
Next week, market attention will focus on financial reports from companies including Take-Two, Infineon, SoftBank, and CoreWeave, and in the second half of the week on results from giants such as Cisco, Applied Materials, Siemens, and Allianz. Detailed breakdown below:



Daily Summary: From Panic to Euphoria. The Market Recoups Losses.



US OPEN: Falling Oil Prices and Dip-Buying Fuel Rebound as Nvidia falls


Market Wrap: Strong Banking Sector, Sharp Drop in Oil
Economic Calendar: Nvidia at the Center of a Spying Scandal; Oil Prices Fall After Trump's Remarks📆
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.