


Right after releasing its results, Netflix fell more than 4% in after-hours trading.
Despite slightly beating market expectations on the core financial metrics, the company disappointed shareholders in other key areas.
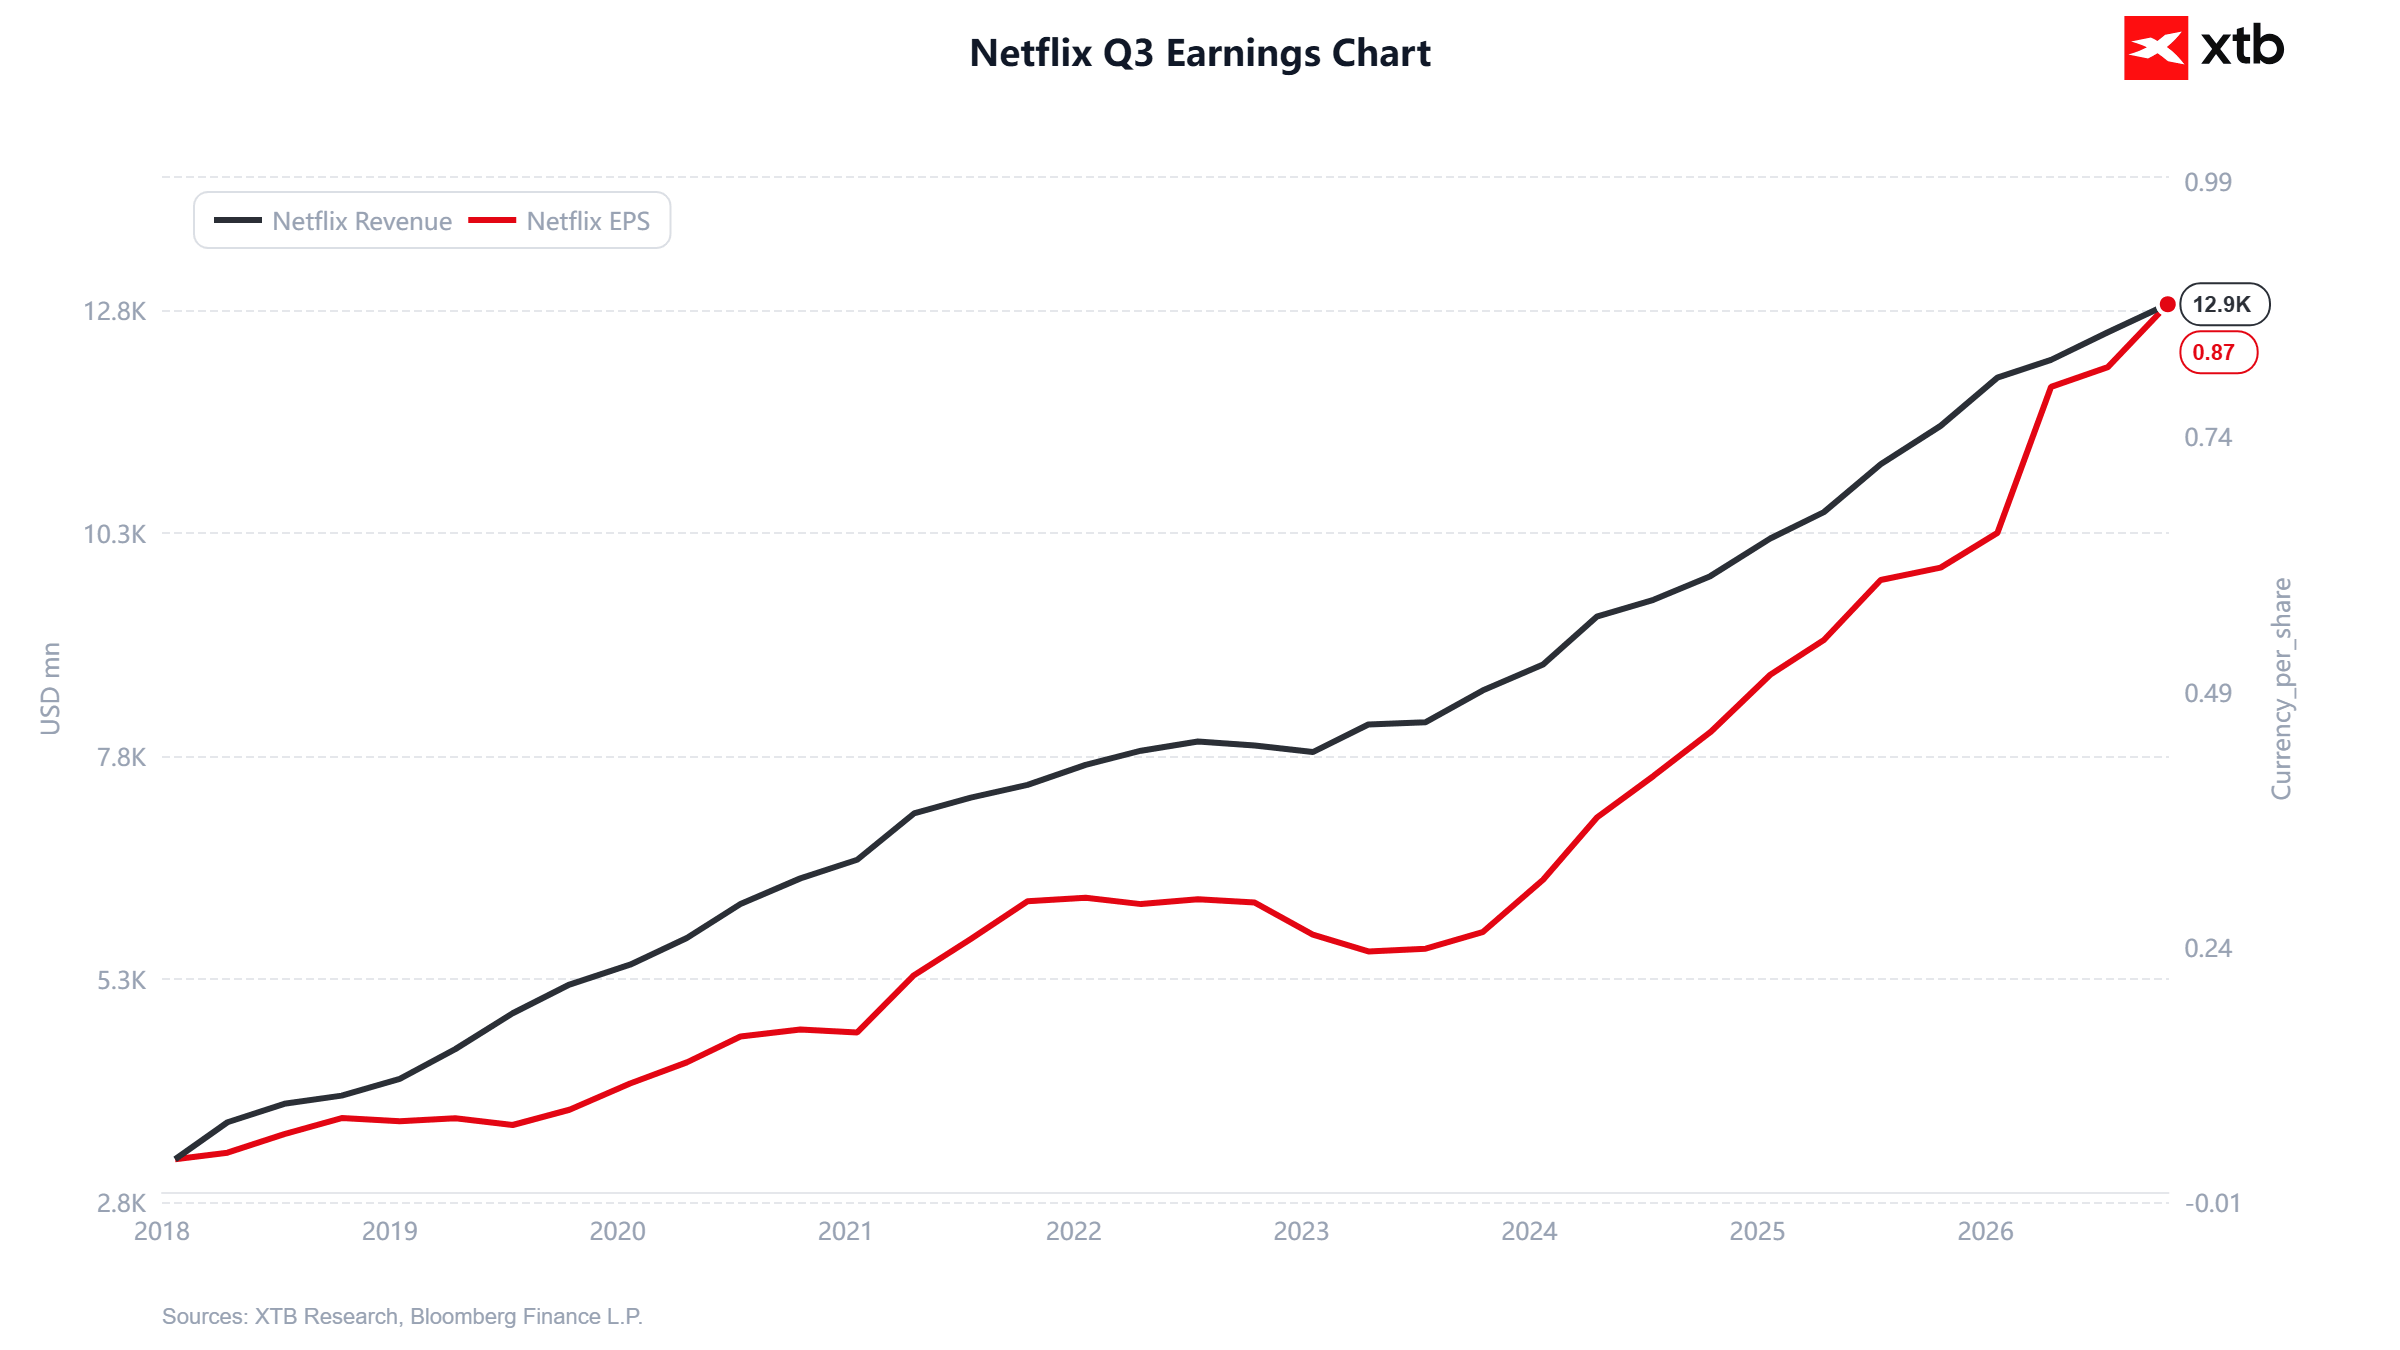
Market expectations were midly optimistic, although the bar still was not set very high:
- Revenue: 12.87 billion USD versus the expected level above USD 12.8 billion.
- EPS: 0.87 USD, above market expectations around USD 0.82. This represents year over year growth of about 60%.
- The strong profit growth was driven by an impressive margin increase, with operating margin rising to 34.6%, which is 1.4 percentage points above management’s guidance.
What went wrong?
The rise in profit and margin looks impressive, but it is not organic. Last year’s operating result was weighed down by more than USD 620 million related to a tax dispute with the Brazilian government. The reported year over year margin increase is as much as 6 percentage points, but after adjusting the comparison base, the improvement falls to around 1 percentage point.
But this is not shareholders’ biggest concern.
Management was forced to cut its Q4 EPS guidance. The new forecast is about USD 0.67 per share versus USD 0.73 expected before the earnings call. That is a drop of nearly 10%.
Even worse, one of the expected growth engines for the coming quarters and years, advertising, underperformed. The company is forecasting revenue limited to USD 2.7 billion versus the expected USD 3.0 billion. Management explains this disappointment by slower than anticipated rollouts of solutions intended to improve monetization. This has major implications for valuation, because a delay or slowdown can trigger a much larger selloff than the nominal difference in the result might suggest.
This stems from the concept of the time value of cash flows, which is strongly amplified by the operating leverage shareholders are counting on.
Concerns remain
In Q2, revenue grew 13.4%, while total viewing hours across the entire first half of the year increased by only 2%. The company also signaled then that content amortization would grow more slowly in the second half of the year, which was expected to support profitability.
This means the company is showing high monetization efficiency, but the pace of organic growth remains very low. This creates a clear constraint on the company’s maximum profitability and at the same time increases operational risk.
Technical analysis of NFLX.US (D1)
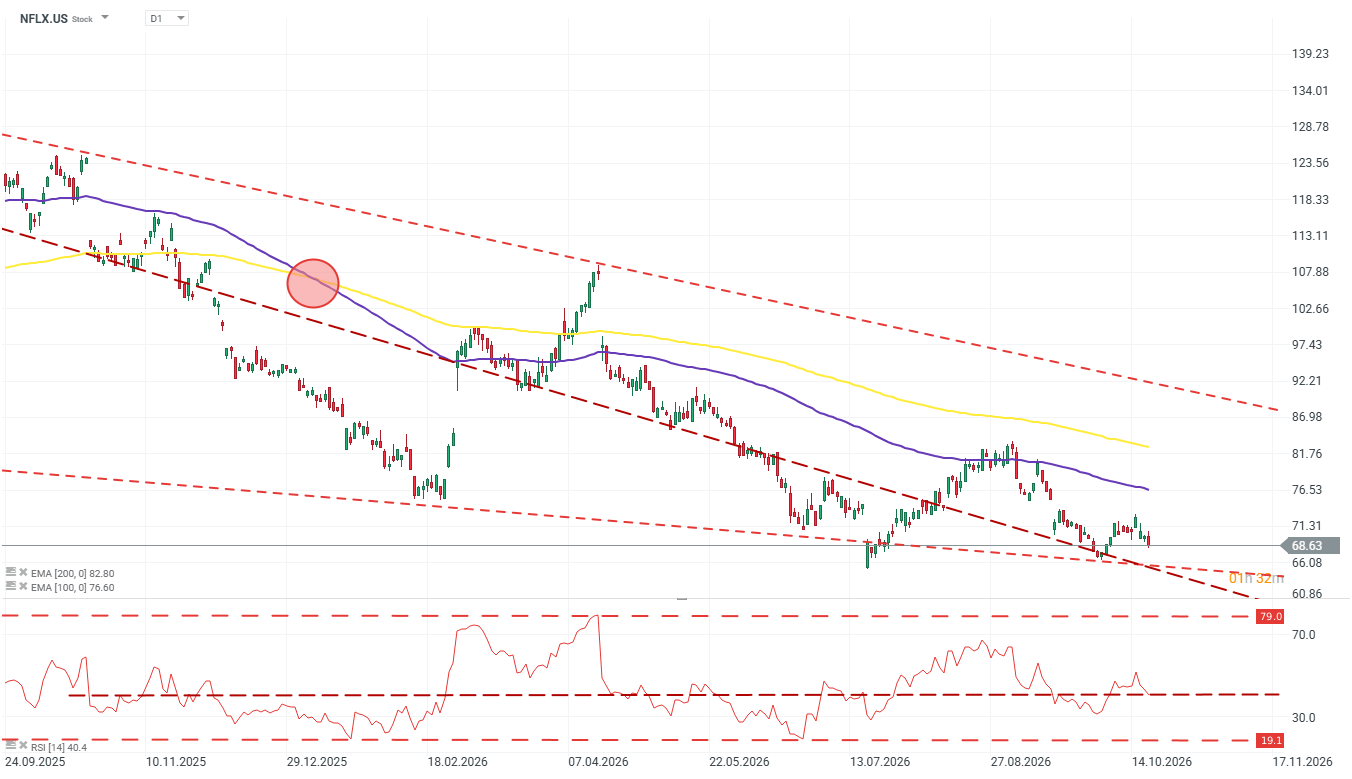
Netflix (NFLX.US) on the daily timeframe remains in a downtrend, with the price around USD 68.63 moving within a long-term descending channel. The price remains below the falling EMA 100 and EMA 200, confirming selling pressure and a persistently negative technical structure. Recent rebound attempts ended at progressively lower levels, and the market is again approaching an important support zone at USD 66 to 64. A break below this area could open the way for further declines toward USD 61. The RSI (14) is hovering near the neutral level of 50. The first resistance remains around USD 71 to 72, while a stronger barrier is located at the EMA 100 near USD 76.60. Source: xStation5.



Daily Summary: Buyers Refuse to Give In

CoreWeave: Record Demand Collides with Crushing Costs



US OPEN: The wave of AI concerns is building again, oil returns near highs

SpaceX must show that Starlink can fund the Group’s growing ambitions
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.