


Wall Street opened Wednesday's session in the red. The S&P 500 fell 0.8%, while the Nasdaq 100 retreated 1%. The main driver behind the sell-off was a stronger-than-expected September CPI reading, which once again raised expectations of Fed rate hikes - both this year and next.
Inflation Returns to the Forefront
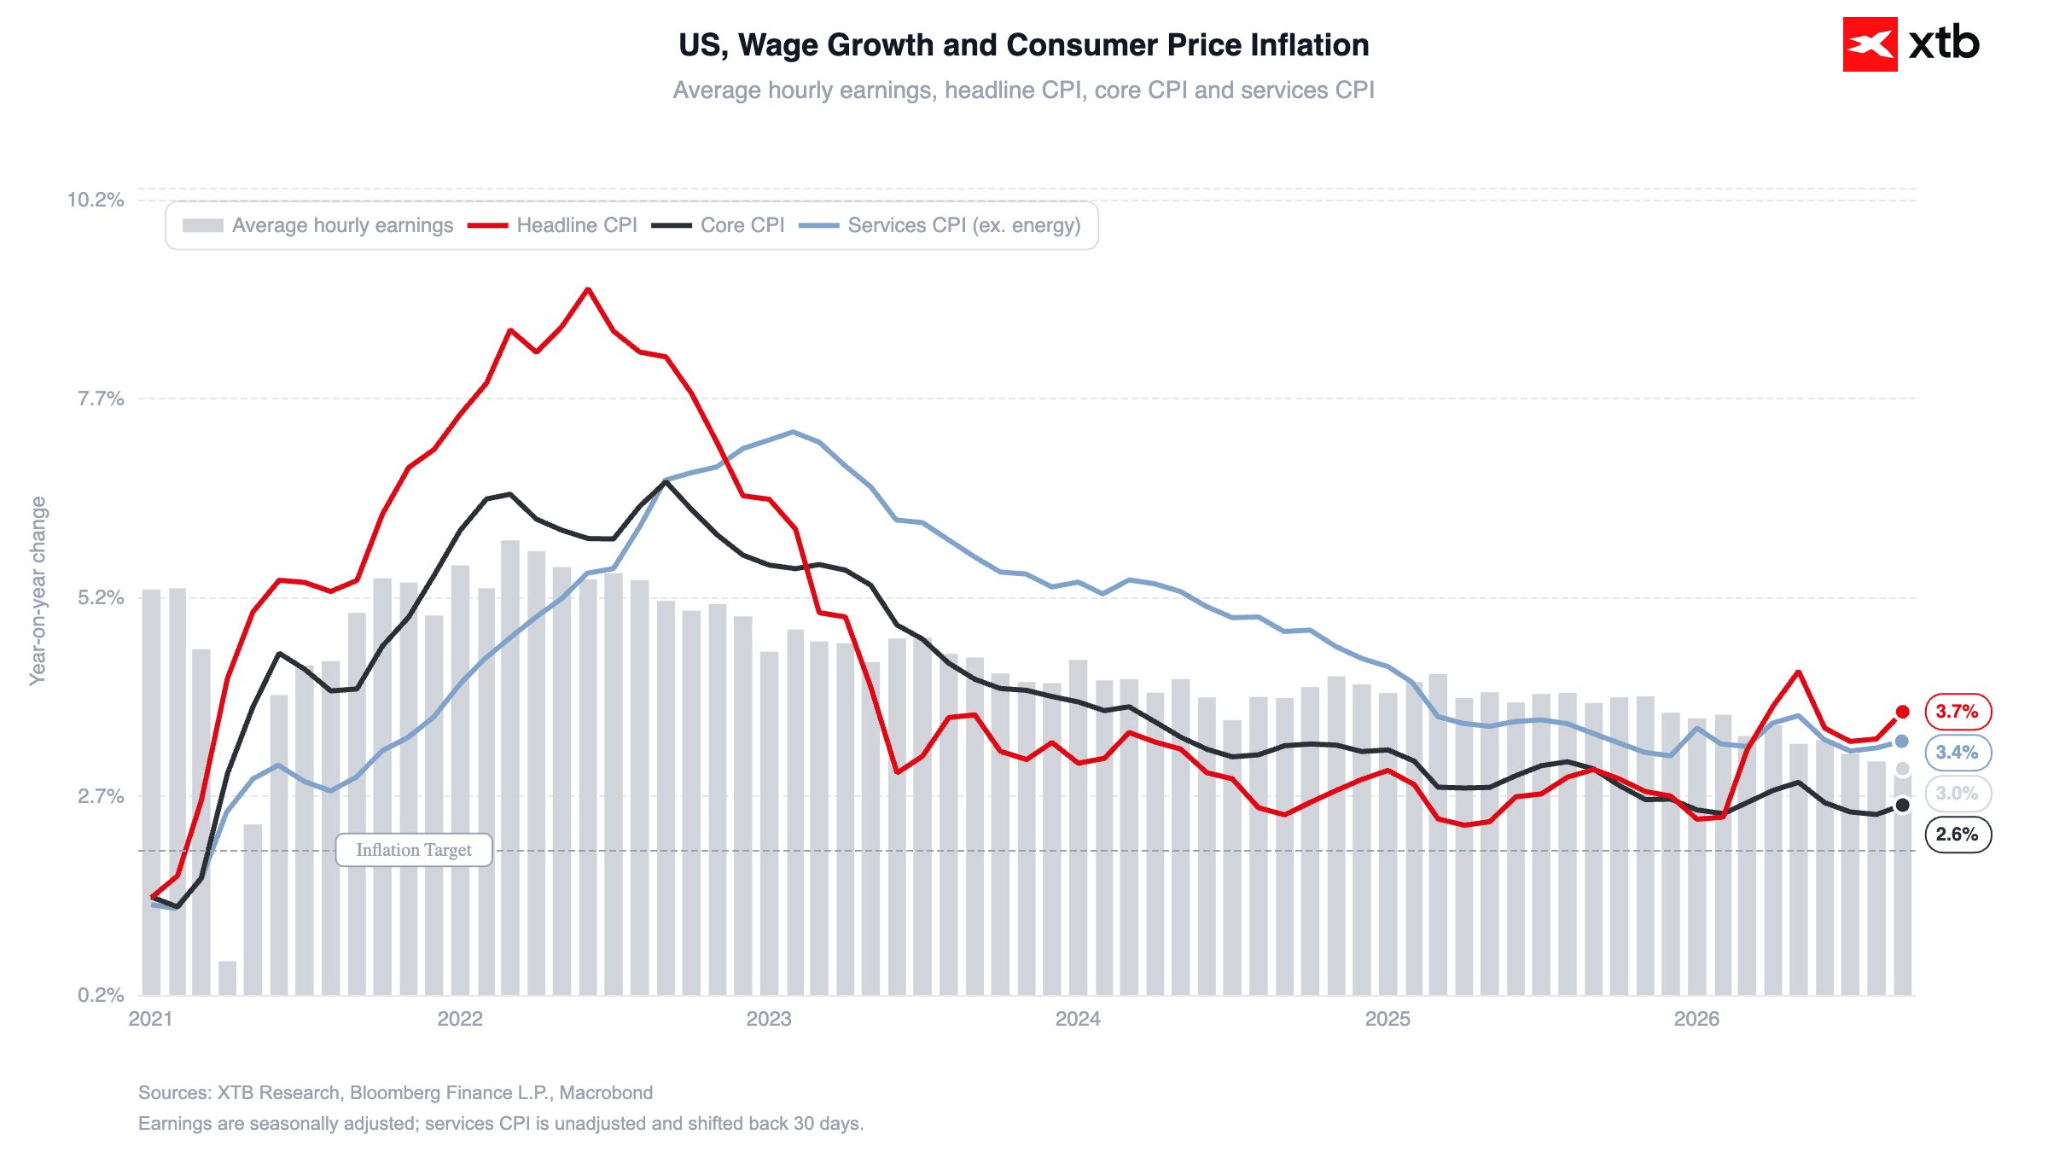
Today's CPI publication proved hotter than the consensus had anticipated. Headline inflation accelerated to 3.7% YoY (up from 3.4% in August), surpassing expectations of 3.6%. Core inflation (excluding food and energy prices) rose to 2.6% YoY against forecasts of 2.5%. Inflation has remained above the Fed's target for 66 consecutive months, with little indication of a swift return to target.
Figure 1: US CPI Inflation and Wage Growth (2021 - 2026)
 Source: XTB Research, 14.10.2026
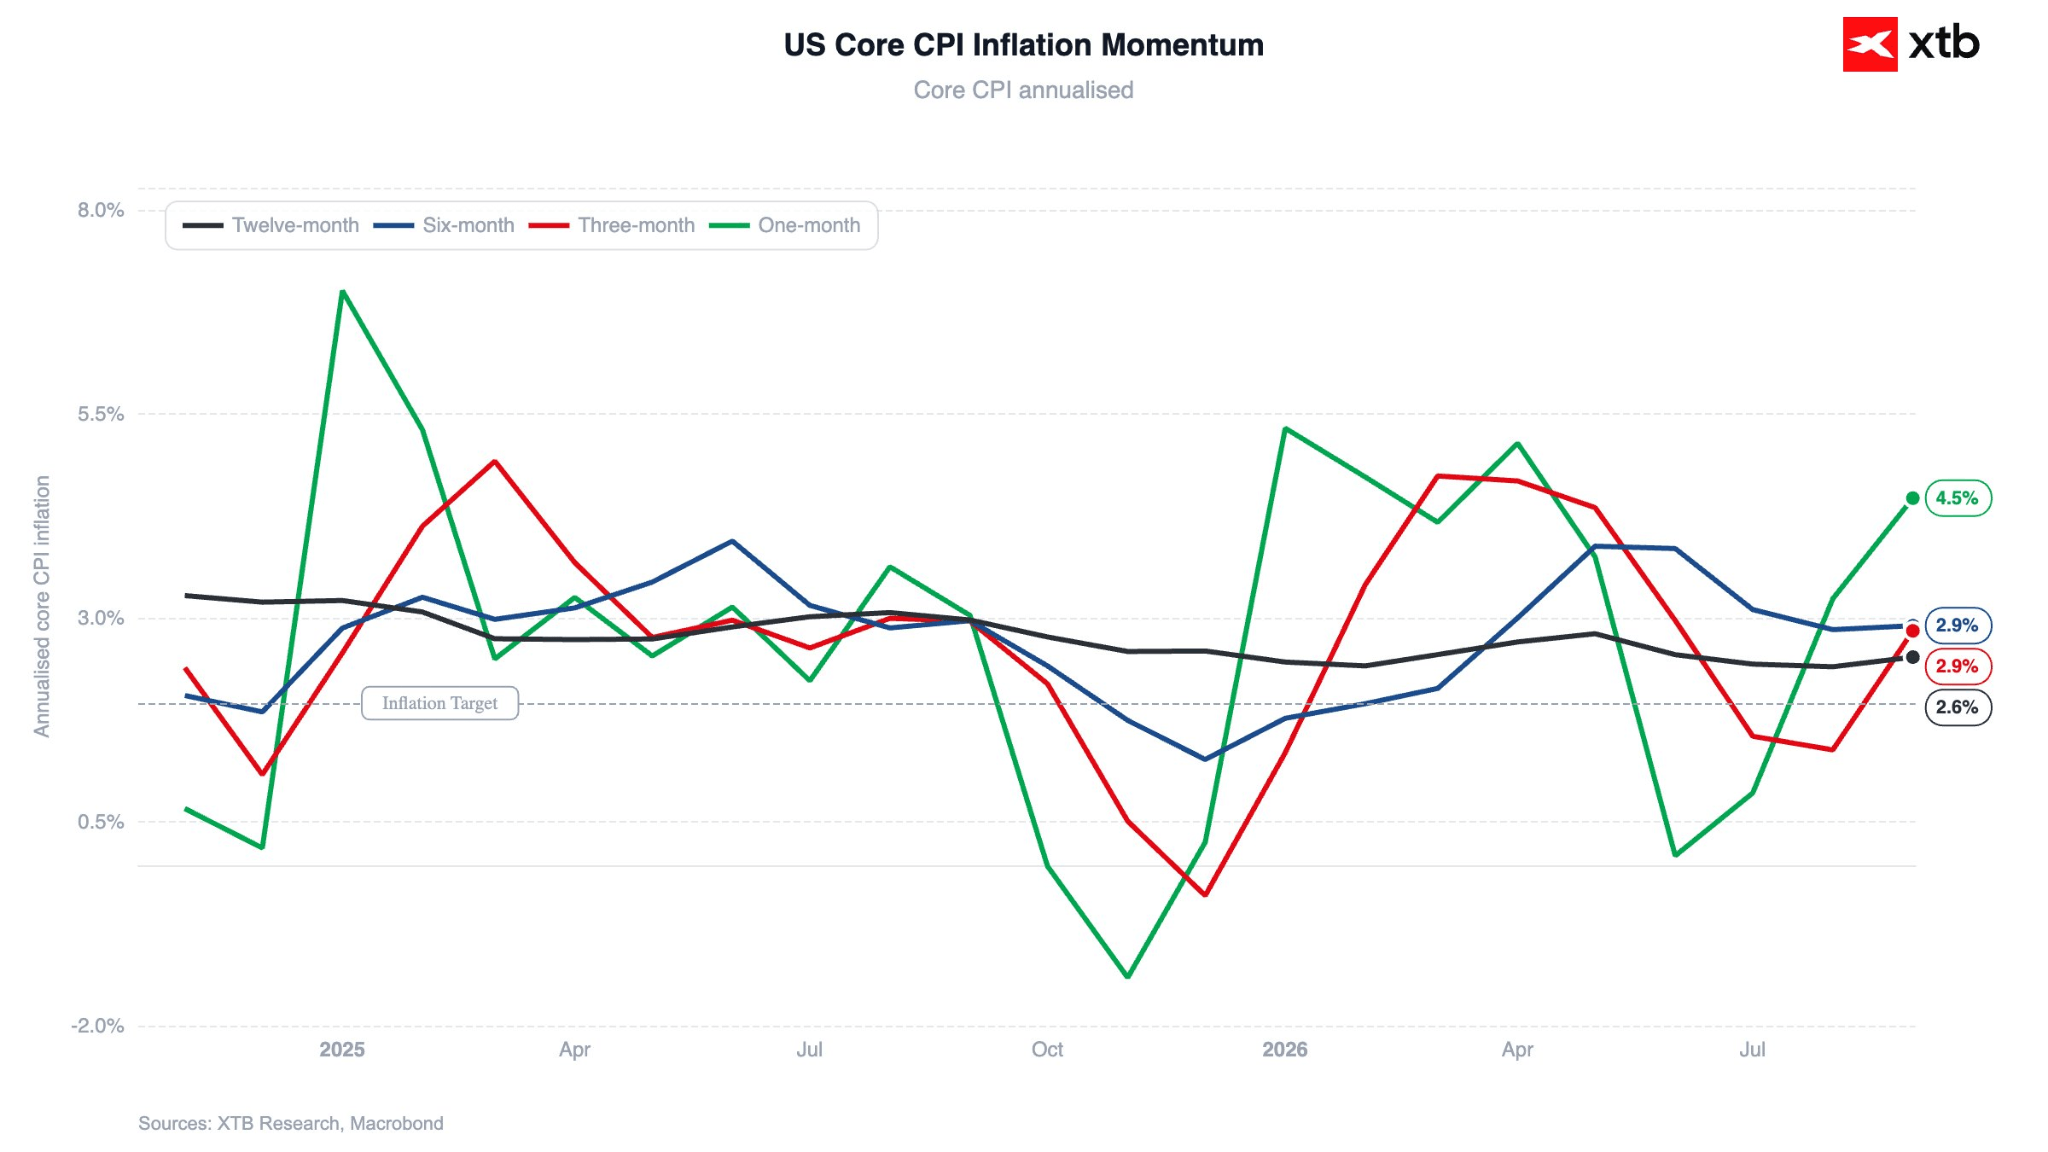
On a monthly basis, the headline measure increased by 0.6% (the fastest pace in five months), while the core measure rose by 0.3%. Unsurprisingly, 3-month momentum for the core measure returned above the Fed's inflation target.
Figure 2: US Core CPI Inflation Momentum (14.10.2026)
 Source: XTB Research, 14.10.2026
The scope of the inflationary impulse is also expanding. Prices for over 52% of products grew at a rate exceeding 3% in September, with 35% rising at a rate higher than 4%.
It is worth noting, however, that the sharp rise in the core measure was largely driven by a single component: OER (owners’ equivalent rent). Housing market conditions had been relatively muted in preceding months, naturally raising questions as to whether this increase might be a temporary outlier.
Dollar reaches highest level since May 2025; gold and bonds decline
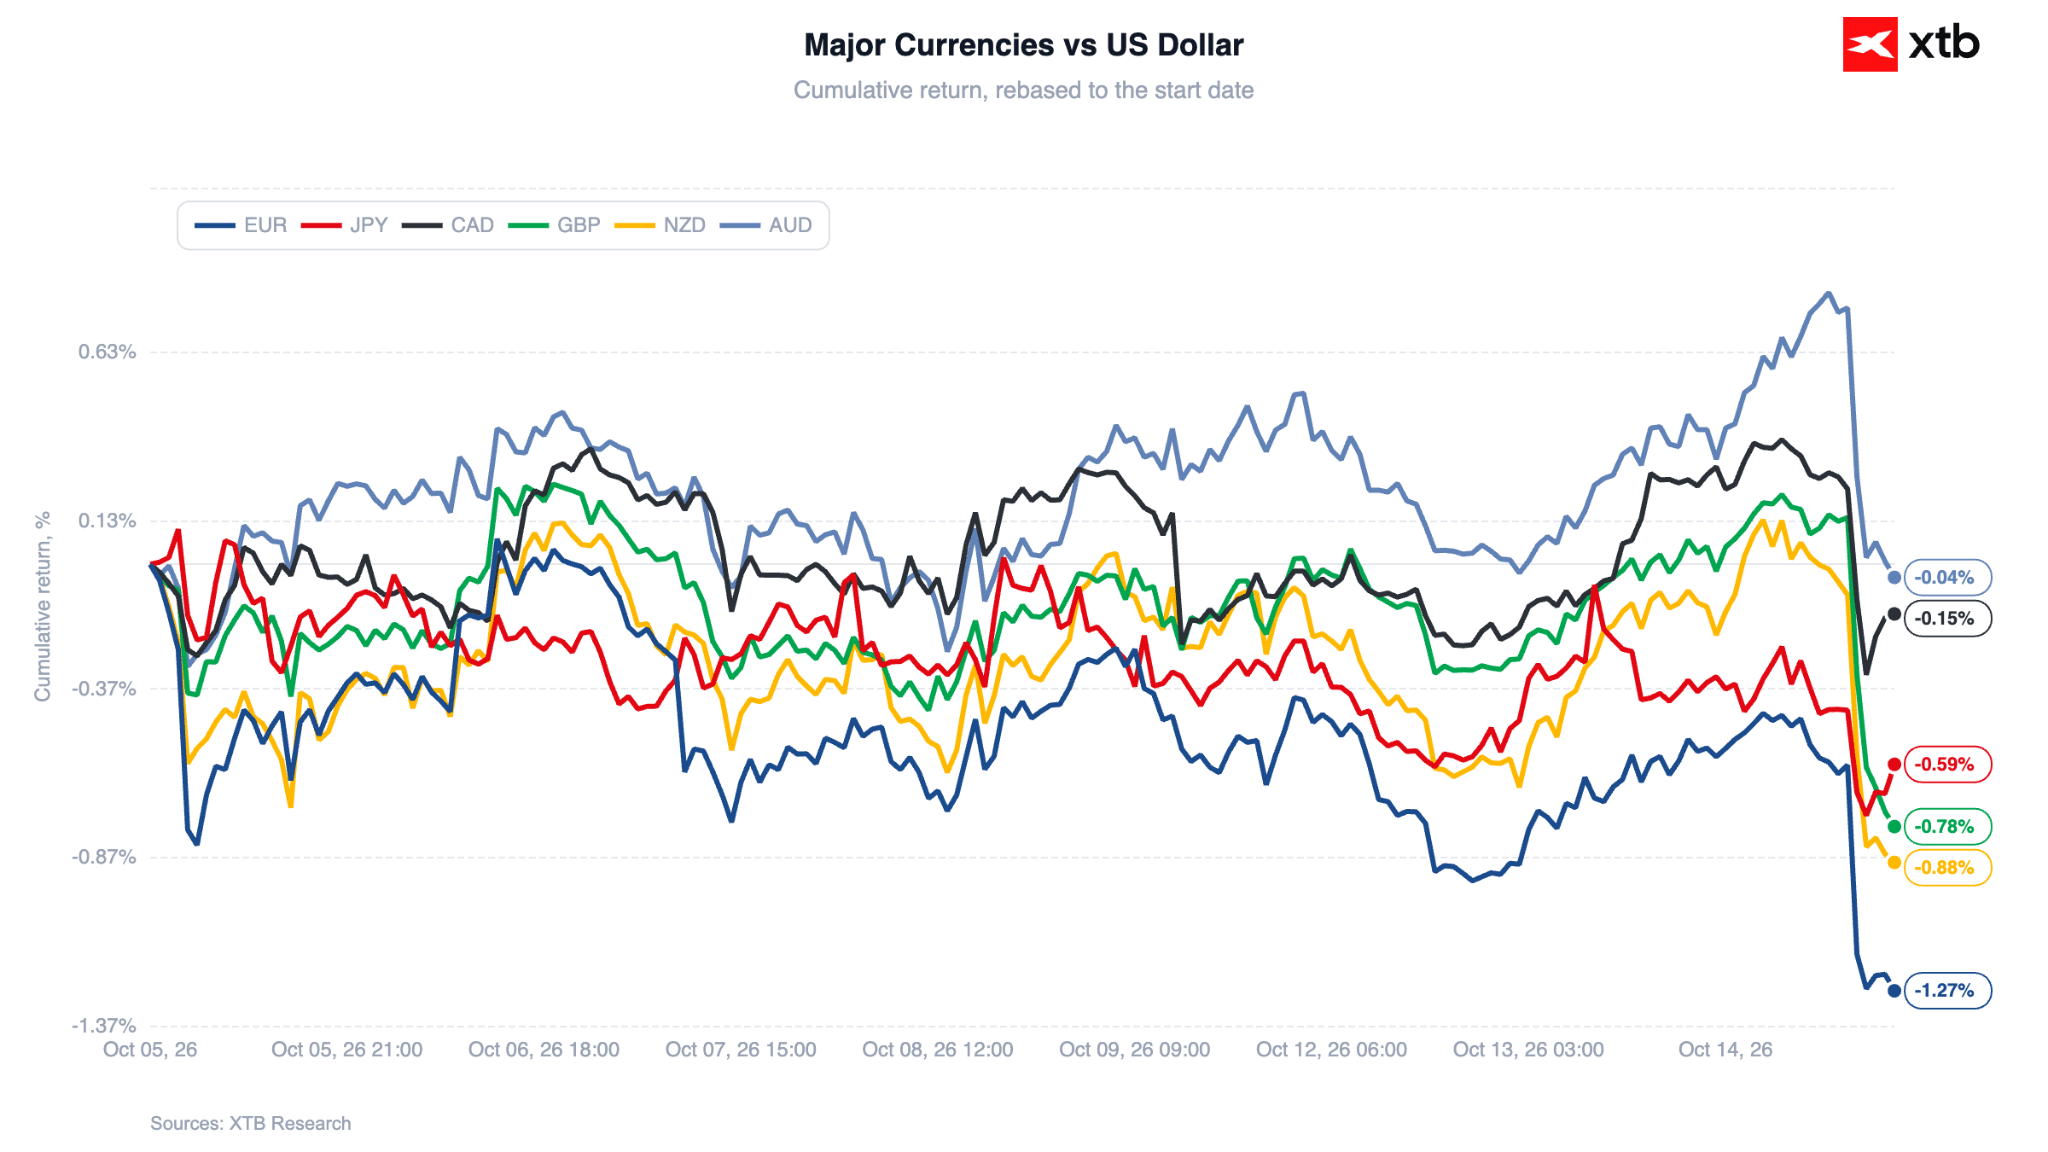
A strong market reaction to today’s data was visible across foreign exchange markets. All G10 currencies weakened against the US dollar, including the euro, which fell approximately 0.7%. The EUR/USD pair is approaching the 1.11 level.
Figure 3: Major Currency Performance [vs. USD] (05.10.2026 - 14.10.2026)
 Source: XTB Research, 14.10.2026
This reaction follows a significant increase in bets on the Fed continuing its tightening cycle at the October meeting. Only yesterday, markets assigned a relatively low probability to such an outcome via futures contracts pricing, but expectations have now converged towards 50%.
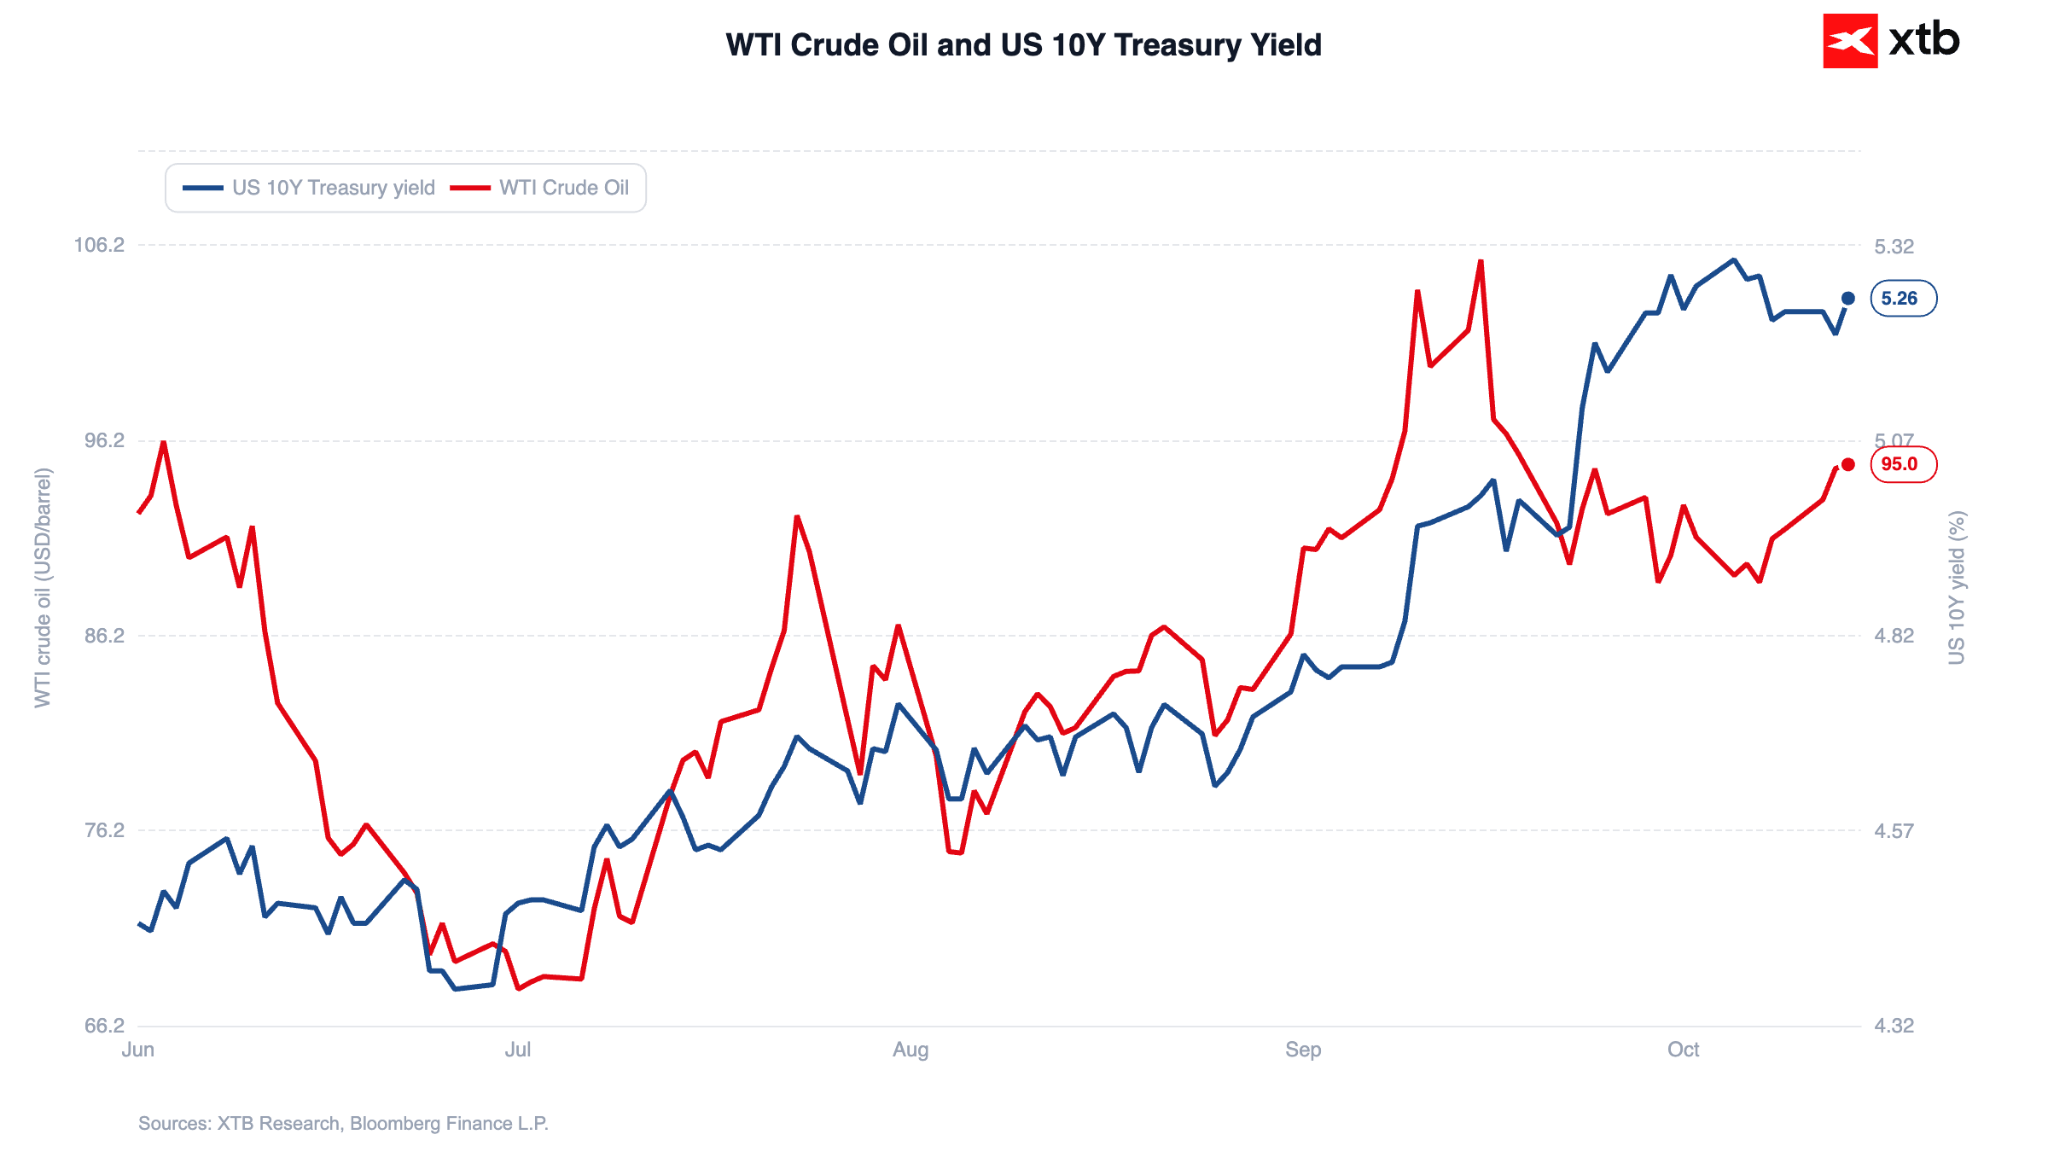
Predictably, US Treasury yields moved higher. Benchmark 10-year yields briefly touched 5.33% before settling near 5.27%. Two-year yields, which are substantially more sensitive to inflation expectations, spiked to 4.95% before easing to around 4.86%.
Figure 4: US 10-Year Treasury Yield and WTI Crude Oil (06.2026 - 10.2026)
 Source: XTB Research, 14.10.2026
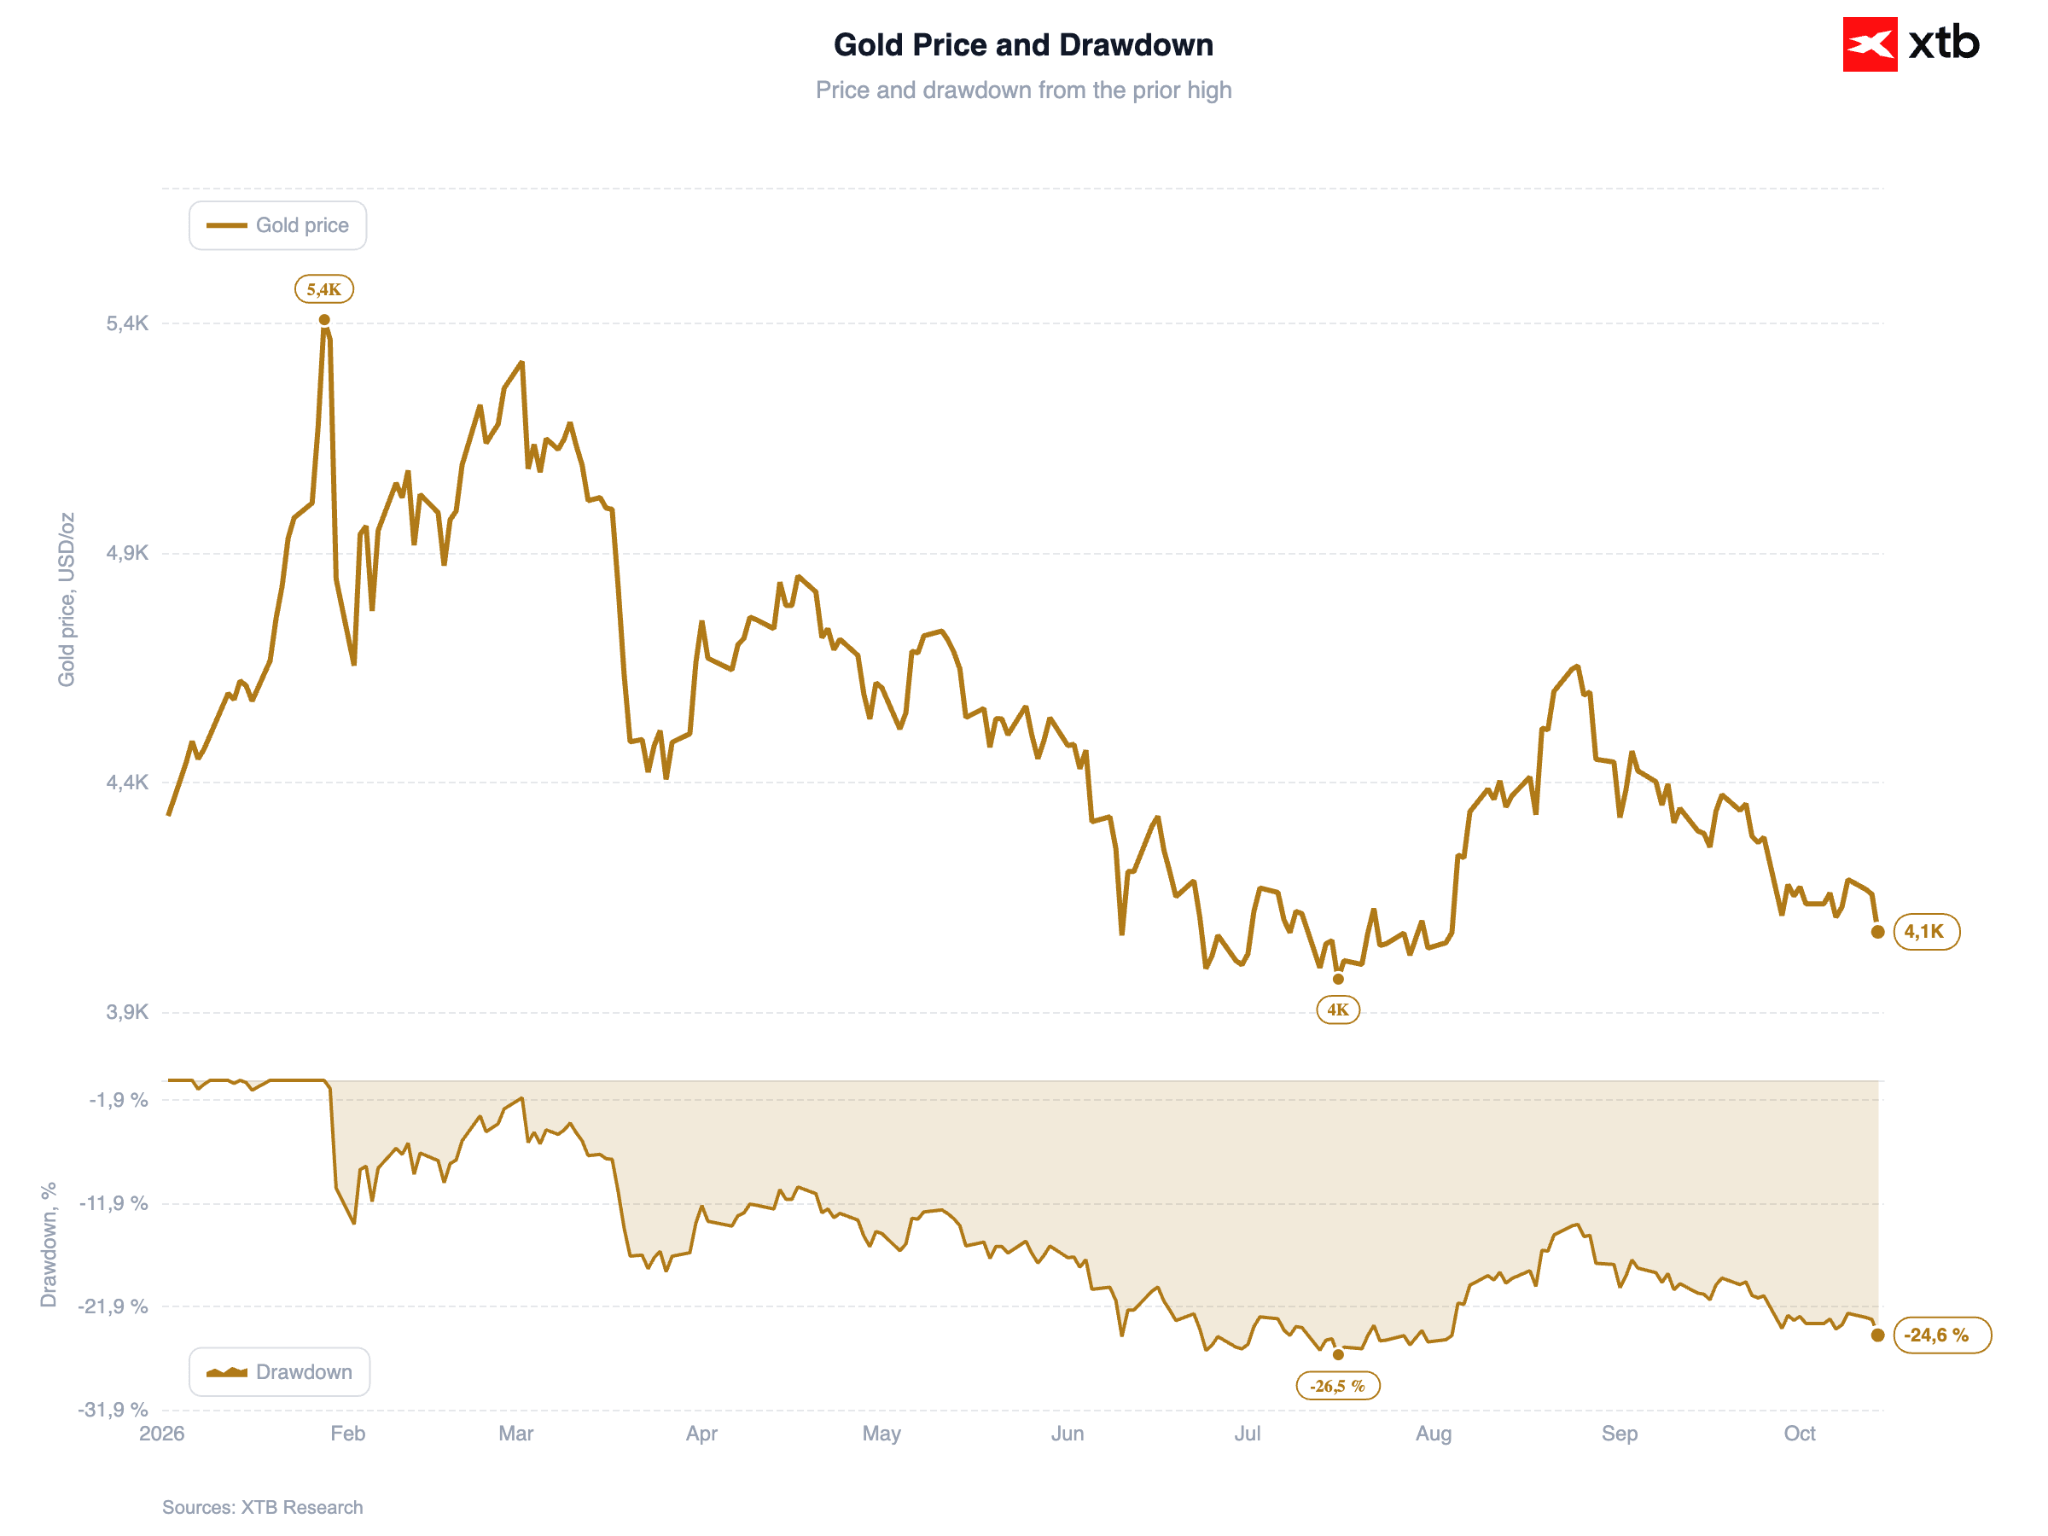
Precious metals, acting as direct alternatives to US government debt, faced selling pressure. Gold declined 2% towards $4,075 per troy ounce, whilst silver dropped 6% to $55.60.
Figure 5: Gold (2026)
 Source: XTB Research, 14.10.2026
Rising bond yields naturally created headwinds for major equity indices as well.
Semiconductor sell-off accelerates
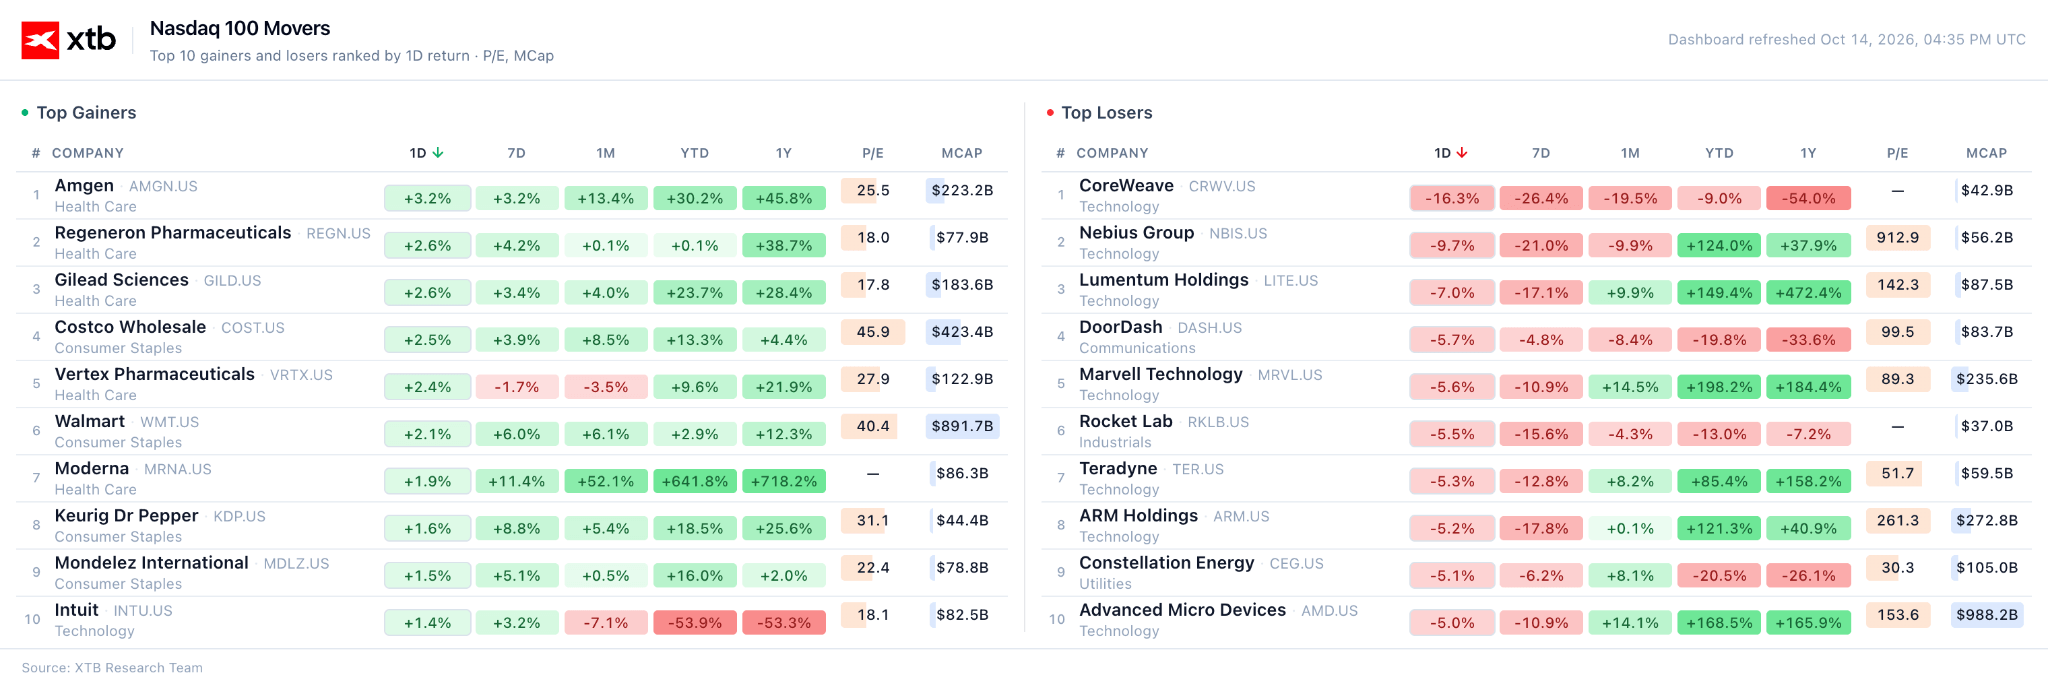
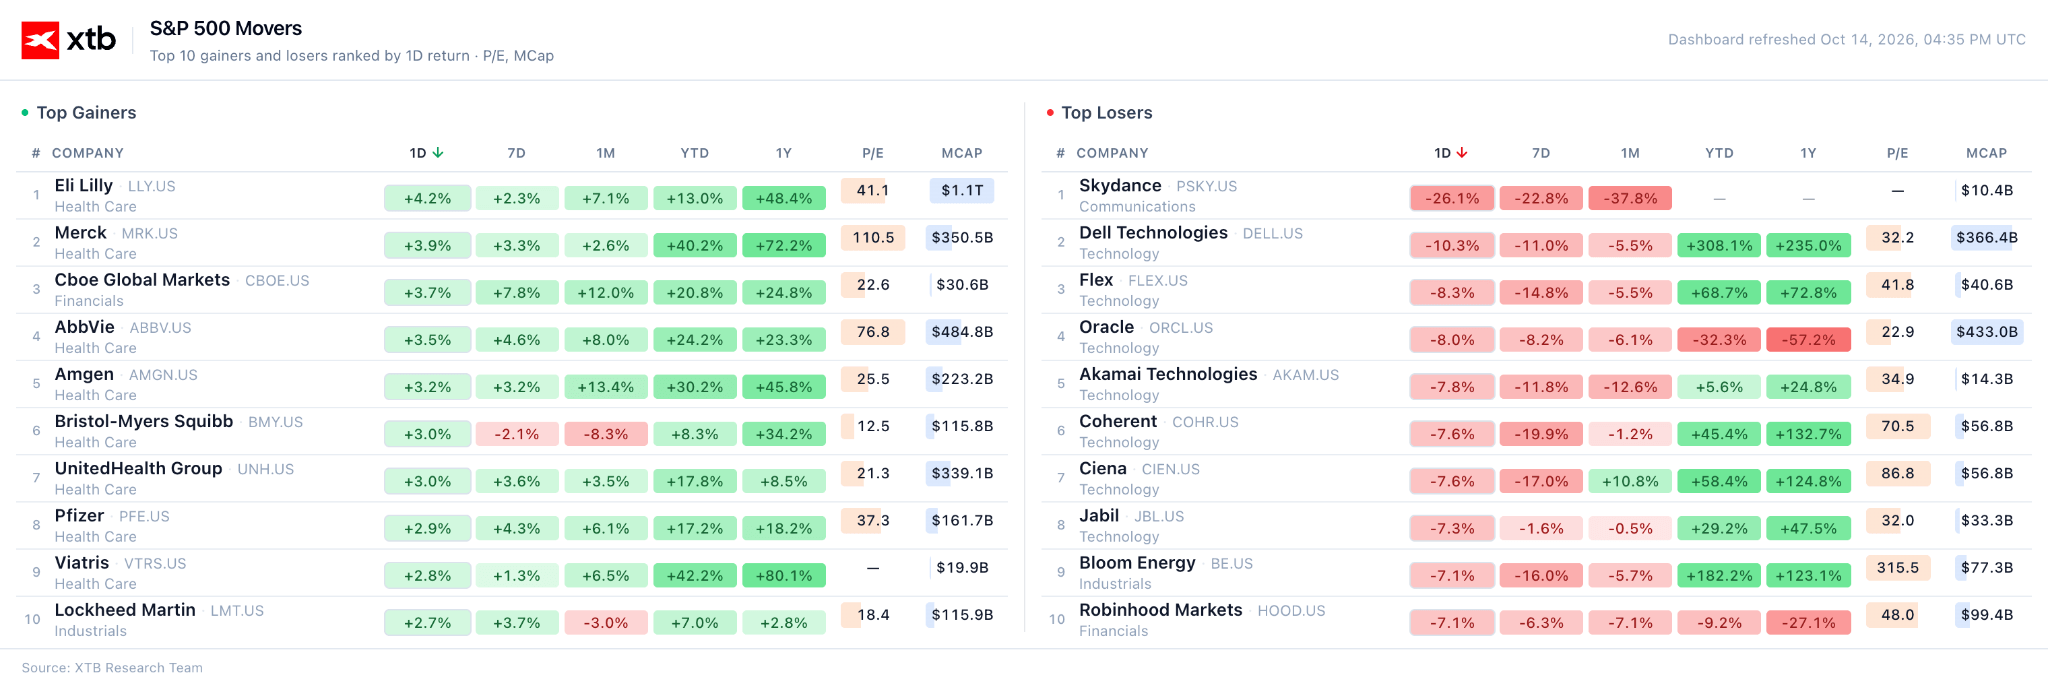
Alongside the CPI release, the ongoing sell-off in semiconductor stocks served as the second key theme of the trading session. The SOXX Index tumbled 4%, extending its 5-day decline to over 10%.
Investors are increasingly questioning the sustainability of the artificial intelligence investment boom, with elevated debt levels across the sector, higher interest rates, stretched valuations, and intensifying competition (including from Chinese competitor CXMT) causing concern.
Figure 6: Nasdaq 100 Gainers and Losers (14.10.2026)
 Source: XTB Research, 14.10.2026
A further potential catalyst for market sentiment will be Anthropic's meeting with selected investors in San Francisco later today, organised as part of preparations for its prospective IPO. Wall Street will be looking for guidance regarding revenue growth trajectory to better gauge market appetite for continued AI capital expenditure.
Figure 7: S&P 500 Gainers and Losers (14.10.2026)
 Source: XTB Research, 14.10.2026
Corporate News
Bank of America ($BAC.US)
Shares in the bank dropped over 5% today, putting the firm on track for its worst session on the spot market since April 2025. The sharp sell-off was primarily driven by lower-than-expected revenue reported in today's quarterly earnings release. Results in trading and fixed income fell short of analysts' expectations, whilst the institution also faced regulatory penalties related to anti-money laundering and sanctions compliance deficiencies.
Progressive ($PGR.US)
Shares in the insurer dropped 6% despite net written premiums for the third quarter meeting analysts' forecasts.
State Street ($STT.US)
Net revenue for the third quarter fell short of expectations, with the firm recording an unexpected cash outflow of $62bn. Shares fell 6.4%.
BlackRock ($BLK.US)
The world's largest asset manager posted modest gains today. The firm attracted $205bn in net new inflows during the third quarter, alongside acceleration in revenue growth.
—
Michał Jóźwiak, Financial Markets Analyst at XTB


Morning Briefing: Warsh's silence on interest rates. AI debt fears cooled sentiment, but a rebound is visible


Sell-off in the semiconductor market 📉🖥️


TSMC breaks records once again driven by the AI boom


Daily Summary: Rising inflation weighs on markets, semiconductors suffer most (14.10.2026)
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.