


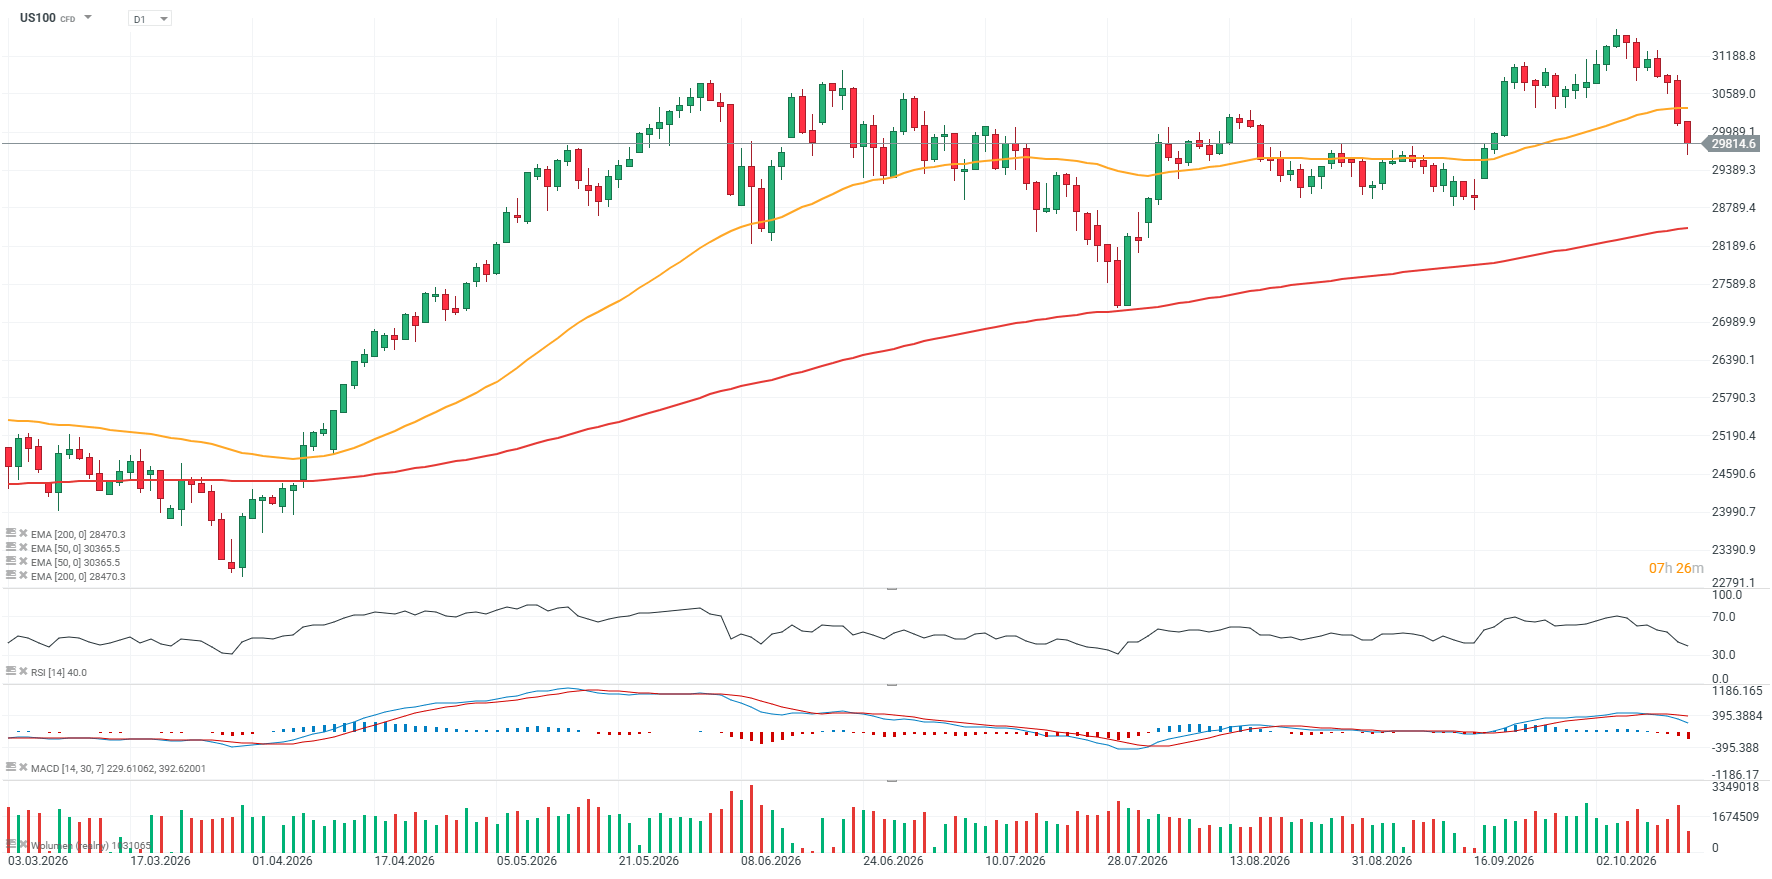
Wall Street remains under pressure today as investors grapple with growing concerns over the scale of artificial intelligence spending and further signs of persistent inflation in the US. The S&P 500 is down around 0.3%, while the Nasdaq 100 is falling 1.1%. The Dow Jones is showing relative strength, gaining around 0.4%. The heaviest pressure is concentrated in the technology sector, where investors are increasingly questioning the pace of monetization of the AI boom relative to very high capital expenditures and rising debt levels. At the same time, the stronger-than-expected PPI reading is reinforcing concerns that the Fed may be forced to maintain a more restrictive stance for longer than markets had previously assumed. Today’s session therefore points to a clear rotation out of technology and into more defensive and traditional market segments.
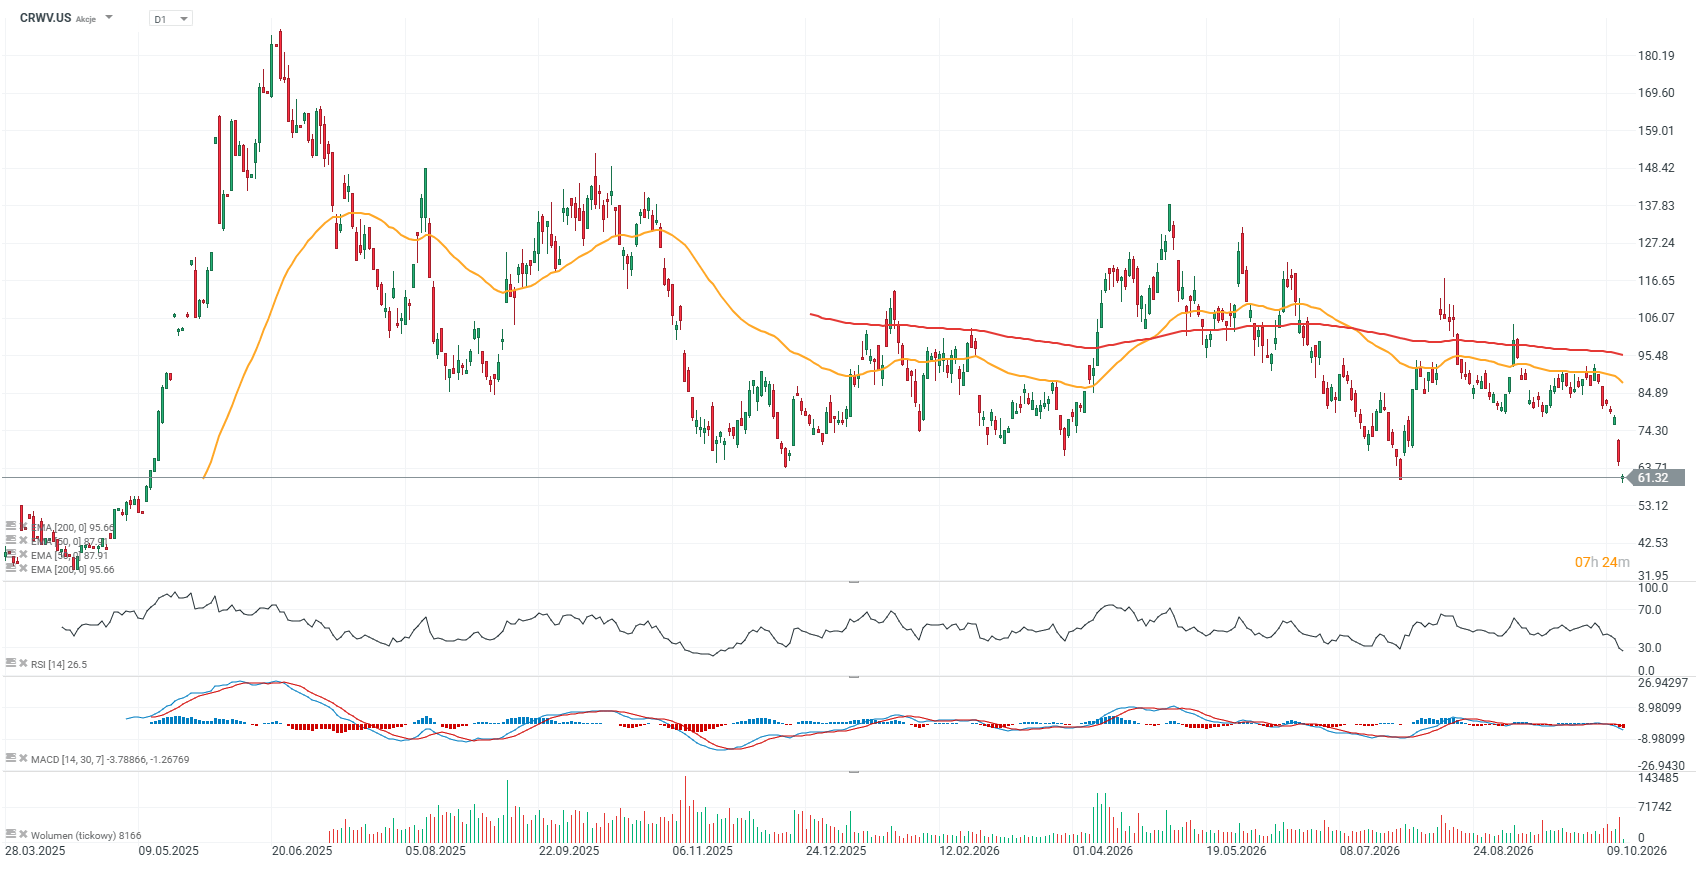
- CoreWeave is down around 8%, extending Wednesday’s sell-off, when the shares fell by more than 15%. Investors are increasingly concerned that the company is financing its AI infrastructure build-out too aggressively with debt, which is also reflected in the sharp rise in yields on its corporate bonds.
- Sentiment across the AI sector also deteriorated after reports that Anthropic’s revenue rose to $16.8 billion in the third quarter. Although the scale of the business continues to grow, some investors are beginning to question whether revenue growth is strong enough to justify the very high valuations of chipmakers and infrastructure providers.
- The sell-off has spread more broadly across the semiconductor and memory sectors. Micron Technology is down around 4%, AMD about 5%, Sandisk around 6%, while US-listed shares of SK Hynix are falling roughly 5%. Another sign of weakness came overnight in Asia, where South Korea’s Kospi index dropped by more than 7%.
- At the same time, the market is finding support outside the technology sector. Walmart is up around 4%, while Merck is gaining more than 3%, helping to limit losses across the major indices.
- September PPI rose 1.3% m/m and 6.3% y/y, marking the strongest monthly and annual increases since 2022. The figures came in well above consensus expectations of 0.6% and 5.5%, respectively.
- Today’s PPI report comes directly after a stronger-than-expected CPI reading, reinforcing the narrative that inflationary pressures are building again. High energy prices remain a particularly important factor, as they may continue to sustain cost pressures across the economy.
- For equities, this increases the risk that the Fed may have to tighten policy more aggressively before year-end, or at least maintain a restrictive stance for longer. Such a scenario is particularly unfavorable for highly valued technology stocks, whose valuations are especially sensitive to rising yields and a higher cost of capital.
US100 chart (D1 interval)
 Source: xStation5
Company news
- Rocket Lab — shares of the space company are down nearly 10% after it announced that the launch of its Neutron rocket has been delayed until 2027.
- Walmart — shares of the retailer are up more than 2% after Deutsche Bank upgraded the stock from “hold” to “buy.” The bank cited a positive outlook for 2027, expects incremental margins to improve, and believes the current inflation environment could help Walmart attract more price-sensitive consumers.
- CoreWeave — shares of the cloud infrastructure company are falling for a second consecutive session, dropping around 8% on Thursday. Investors are concerned that CoreWeave, like other technology companies, is increasing debt too aggressively to finance the expansion of AI-related infrastructure. The company has a market capitalization of around $38 billion and approximately $51 billion in debt, while it generated a net loss of around $2 billion over the past four quarters.
CoreWeave chart (D1 interval)
 Source: xStation5


Market wrap: European indices rebound 🔼 Defence stocks on the rise


TSMC in Talks with Elon Musk Over Terafab

Daily summary 📈 Precious metals and stock indices rebound as Treasury yields fall

U.S. indices attempt to rebound after recent losses
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.