


High energy prices remain one of the most important risk factors for the European economic outlook, even if their negative impact is not yet fully visible in current macroeconomic indicators. EURUSD is falling as the economic outlook has improved primarily for the US, even though final PMI readings from the euro area, including Germany, came in above forecasts. Rising fuel and energy costs in Europe are increasing pressure on households and businesses, particularly in transport and energy-intensive industries, weighing on real purchasing power and corporate margins. France remains another source of pressure for European assets.
- French 10-year government bond yields have risen sharply, while markets are becoming increasingly cautious about the country’s fiscal outlook. Unfortunately, the €54 billion fiscal plan failed to materially improve investor sentiment. At the same time, the spread between French and German government bond yields widened to its highest level since the sovereign debt crisis, highlighting a rising risk premium around France.
- Pressure on the euro is also being reinforced by high US Treasury yields and demand for the dollar amid a more defensive investor stance. Markets are clearly waiting for the next key US data releases.
- The United States wants the European Union to release around 120 million barrels of diesel from emergency reserves over the next six months. According to sources close to the talks, Washington has also reportedly pressured France and Germany to tap their diesel reserves, while signalling the possibility of restricting US exports of the fuel.
The dollar is the session’s clear winner: the US Challenger report showed layoffs falling by around 20% m/m, while investors are awaiting another low initial jobless claims reading at 14:30 CET.
- French manufacturing PMI came in at 50.6 points, compared with a forecast and previous reading of 50.3 points.
- Germany’s final manufacturing PMI rose to 53.9 points, above expectations of 53.8 and the previous reading of 53.8.
- The euro area’s final manufacturing PMI came in at 52.9 points, compared with a forecast of 52.7 and 52.7 previously.
- Italy’s unemployment rate rose to 6.2%, compared with a forecast of 5.75% and 5.8% previously.
- The yield on France’s 20-year government bond rose to 5.4% at auction from 4.74% previously, while the bid-to-cover ratio fell to 2.43 from 3.07.
- The yield on France’s 10-year government bond rose to 4.93% from 4.23% at the previous auction, with the bid-to-cover ratio falling to 2.0 from 2.28.
- The euro area unemployment rate came in at 6.4%, in line with both expectations and the previous reading.
If pressure on fuel markets persists for longer, it could gradually translate into weaker consumption, higher production and transport costs, and a further deterioration in the already questionable competitiveness of European industry. For now, this does not necessarily have to be clearly visible in economic activity data, as the transmission channel from energy prices typically works with a lag. In this respect, the United States appears much better positioned than Europe and remains a major exporter of both refined fuels and natural gas.
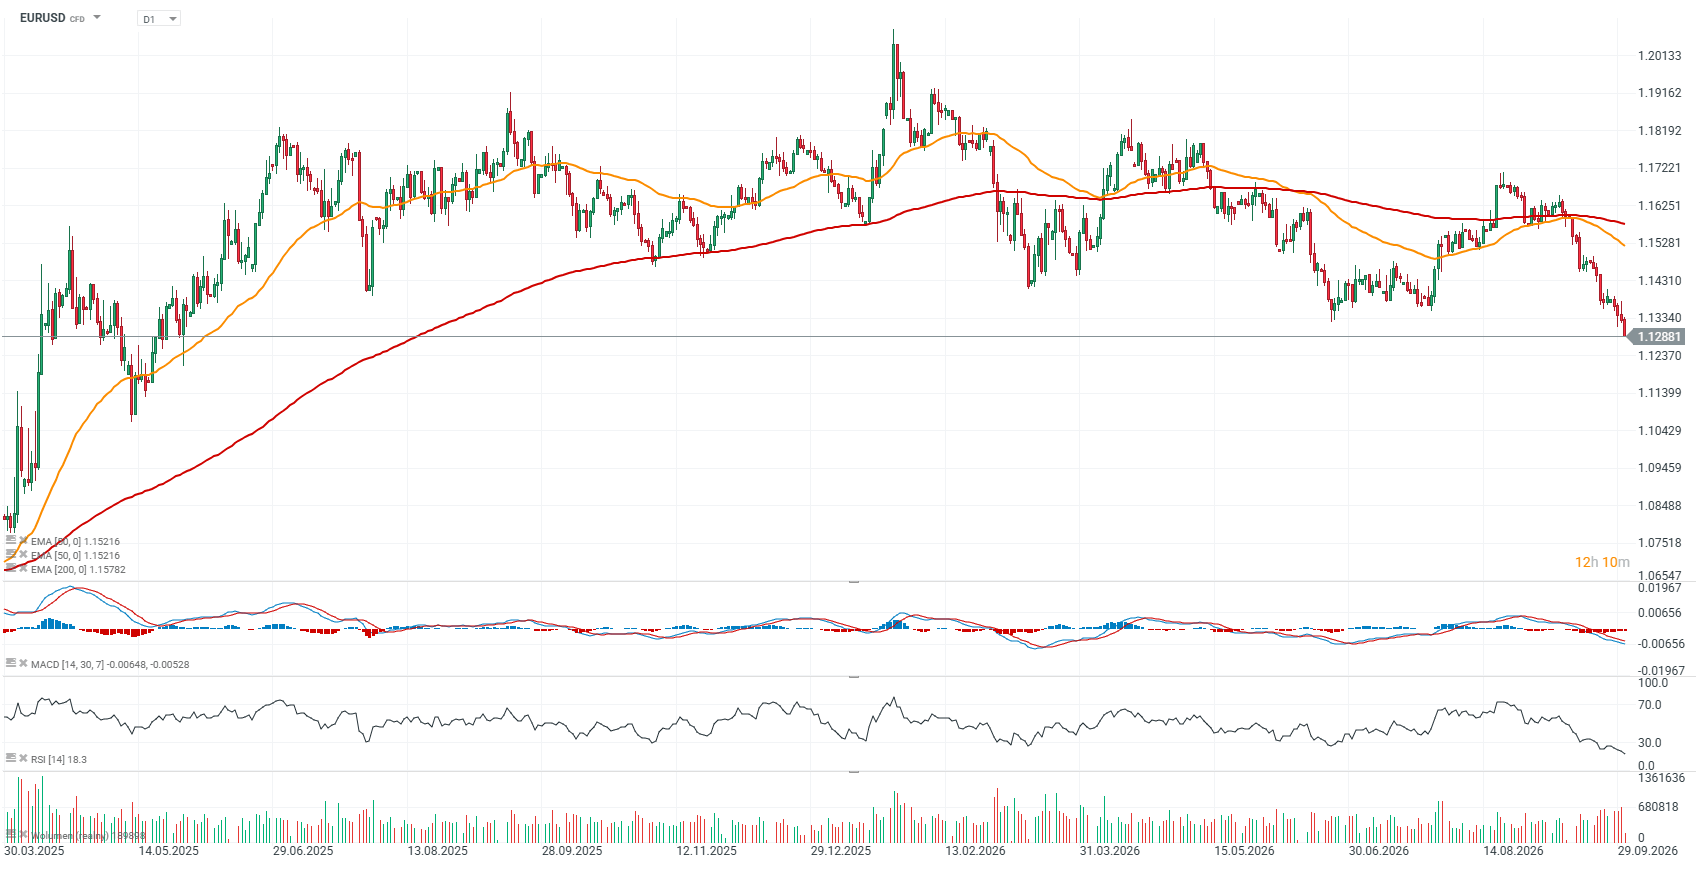
EURUSD chart (D1 interval)
EURUSD is falling today to its lowest level since late May and is heading for a fourth consecutive session of declines. The pair has failed to benefit even from a shift in expectations for US rate hikes, with futures now seeing December as more likely than October. This repricing followed yesterday’s weaker-than-expected PCE inflation data.
 Source: xStation5


Three Markets to Watch Next Week (09.10.2026)


Daily Summary: A Shallow Rebound Ahead of Earnings Season


US OPEN: Trump de-escalates, OpenAI supports Wall Street sentiment
🔼 Gold gains 1.2%
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.