


September PMI figures printed substantially above expectations:
- Composite PMI
- Print: 58.4
- Consensus: 55.3
- Previous month: 56.0
- Services PMI
- Print: 58.7
- Consensus: 55.8
- Previous month: 56.5
- Manufacturing PMI
- Print: 57
- Consensus: 53.7
- Previous month: 53.9
Figure 1: US PMIs (2023 - 2026)
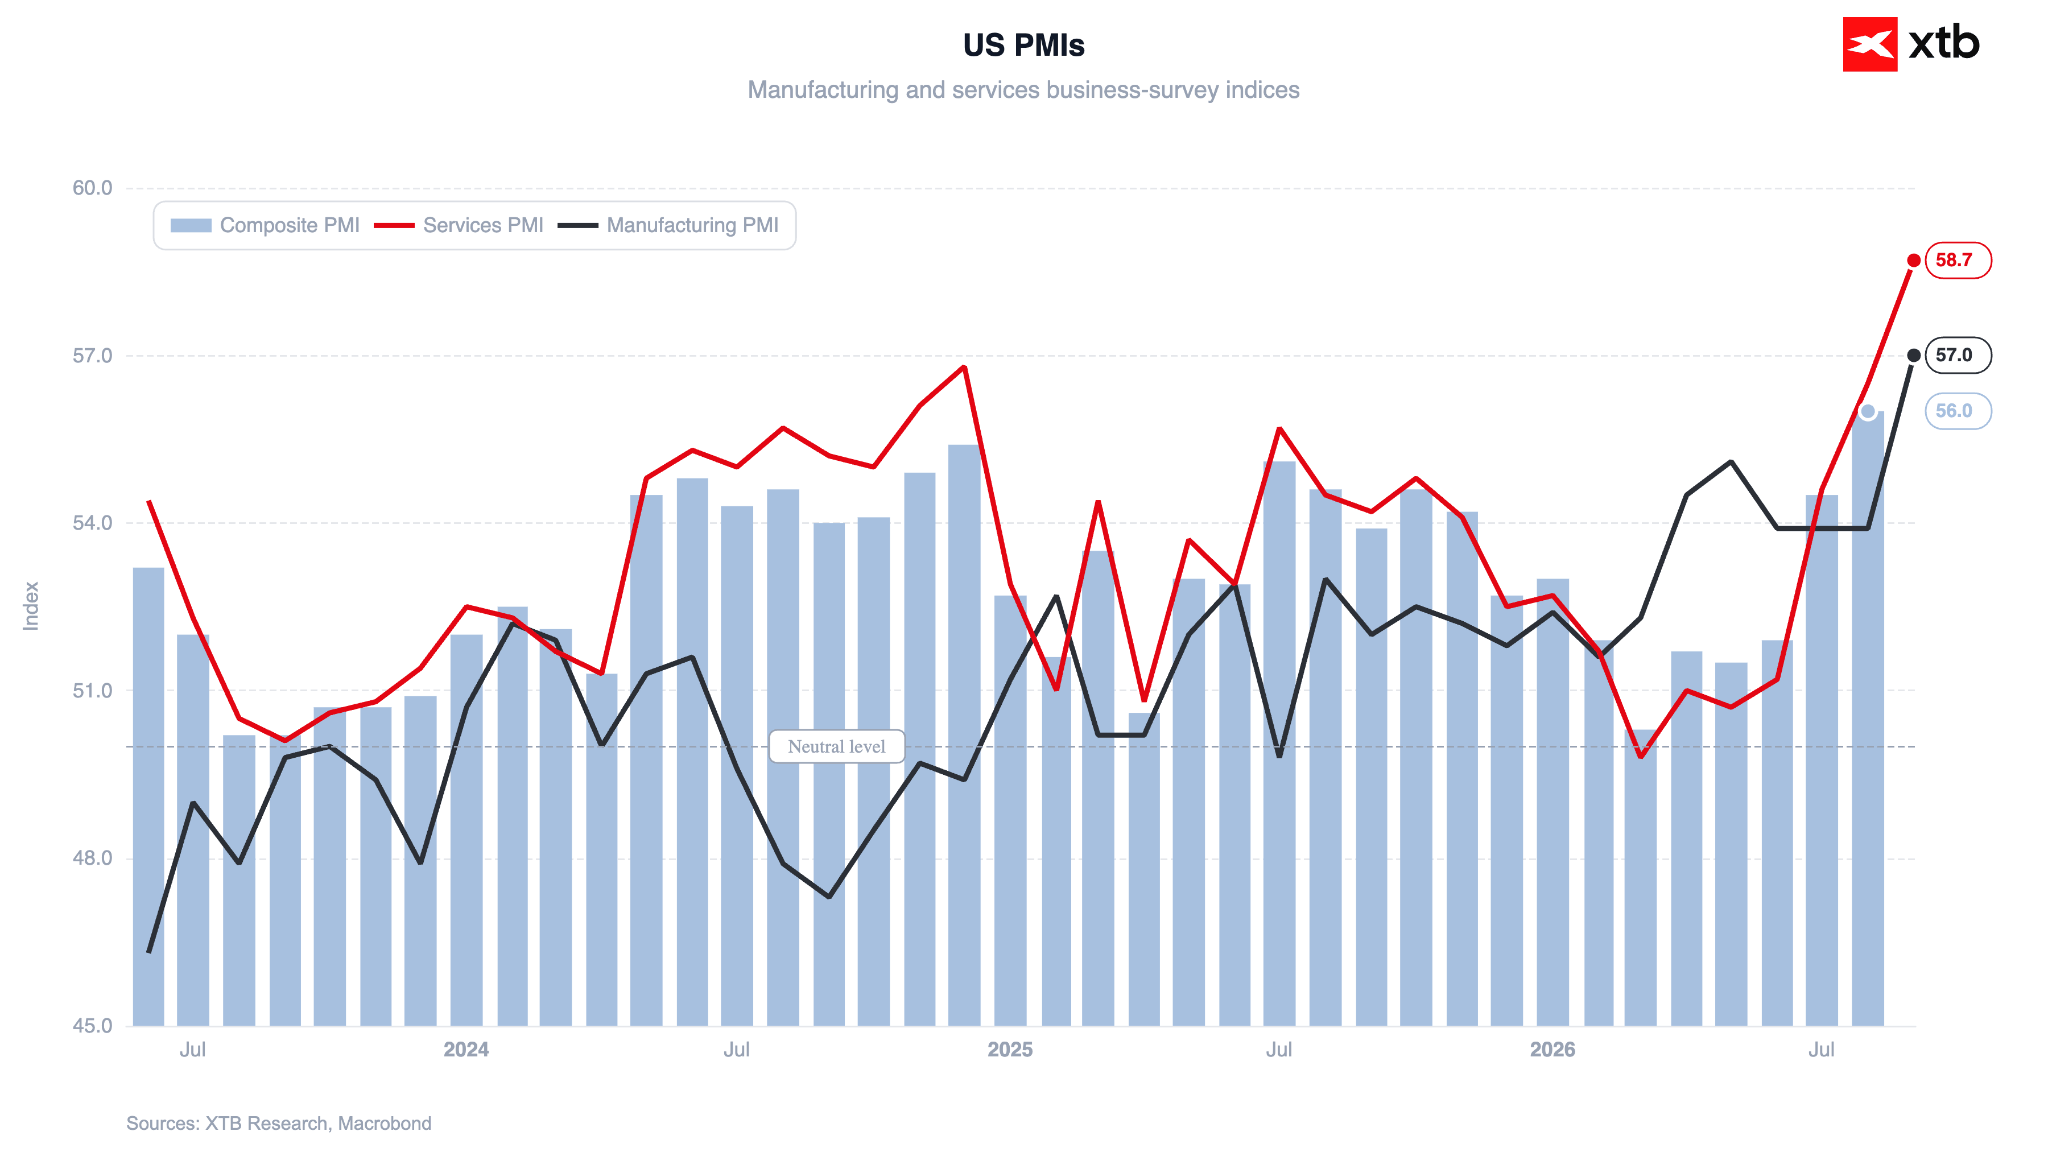 Source: XTB Research, 23.09.2026
Market reaction
The EURUSD pair continues its route downwards, dropping below the key psychological level of 1.14. The move earlier in the day has been supported by increasing bets for Fed rate hikes. Meanwhile, both S&P 500 and Nasdaq 100 are losing ground after today’s opening.
A closer look at data
Economic activity in the US accelerated for the fourth month running and was at its fastest pace since mid-2021, with a marked acceleration in both services and manufacturing. New orders rose in both sectors, with the rate of growth in services being the highest since March 2022 and in manufacturing since April 2022.
- Exports remained a weak spot: the inflow of new export orders declined, particularly in the services sector.
- The labour market improved markedly. Firms were increasing staff numbers at the fastest rate in over four years, in an attempt to clear the growing backlog of orders.
- Backlogs – that is, outstanding production and service orders – rose at their fastest rate since May 2022, indicating rising capacity utilisation.
- Cost pressures intensified once again: input costs rose at their fastest rate in four years, mainly due to higher fuel and transport costs.
- Companies were increasingly passing on higher costs to customers, which pushed up selling prices and worsened the short-term inflation picture.
- S&P Global estimates that the pace of growth in economic activity corresponds roughly to an annualised GDP growth rate of 5%, indicating a very strong start end to the third quarter of the year.

German Ifo stronger than expected but DE40 loses


Swiss SNB and Swedish Riksbank decided on interest rates 🍳 SEK and CHF react


Norges Bank raises intrest rates

Economic Calendar: Central Bank Decisions and Fed Officials’ Speeches in Focus
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.