


European indices are starting the week lower, and disappointing industrial data adds to the cautious mood. Eurozone industrial production for September contracted by 1.5% y/y, against a forecast decline of 0.2%. This confirms the weakness of European manufacturing and complicates the ECB’s position, as it is still considering further tightening. Germany’s DAX is down around 0.4%, Italy’s FTSE MIB around 0.5%, and the Euro Stoxx 50 around 0.5%, to near 6,380 points. France’s CAC 40 is flat, while the UK’s FTSE 100 is up around 0.2% and heading for a record close. Still, Europe remains a relatively safe haven for now, as Morgan Stanley forecasts European equities will gain around 15% by the end of 2027. Investors may treat European companies as an alternative to tech.
Weak data also came from Asia. In China, retail sales in October rose only 0.4% y/y (forecast: 0.8%), industrial production rose 4.8% y/y (forecast: 5.3%), and fixed-asset investment fell 8.1% y/y year to date, showing deepening weakness in demand and investment. In Japan, Q3 GDP slowed to 0.0% q/q versus the expected 0.1%, signalling a slowdown in private consumption. Against this backdrop, Taiwan’s Taiex fell around 6%, the most since July, and the Kospi fell around 3.6%, as chipmakers followed the losses of their US peers. For investors, weaker demand from China is a risk for commodities such as oil and copper, as well as for European companies heavily dependent on the Chinese consumer, for example in the luxury goods sector.
The weight of sentiment is also coming from the US. Nvidia lost more than $500 billion in market capitalisation last week after Jensen Huang stepped down as CEO. Today there are reports of a possible return for Huang, while Scott Bessent, the US Treasury Secretary, is demanding a “dramatic” change in the company’s leadership. Nasdaq 100 futures are down around 0.5%, while S&P 500 futures are flat. This morning the declines were still close to 1%. After the sharp selloff in bonds, the yield on US 10-year Treasuries stands at above 5.1%, and the market fully prices in a 25 bp Fed rate hike in December. That is why attention today will focus on Fed Chair Warsh’s speech at 6:00 p.m. (CET). A hawkish tone could deepen the pressure on bonds and tech stocks. A more cautious message would give the market room to breathe.
FX market
- EURUSD: The euro is weakening slightly (around 0.1%) and holding near 1.10, as the dollar remains supported by expectations of further Fed rate hikes.
- GBPUSD: The pound is losing around 0.2% and slipping toward 1.319. The pressure on sterling comes despite the good condition of London’s index.
- USDJPY: The rate is practically unchanged, near 1596. Weak data from Japan does not change the picture.
- USDPLN: The zloty is losing around 0.2%, and the dollar costs around 4.00 PLN. Behind the weaker PLN is investor caution ahead of Warsh and the US data.
Commodities market
- Crude oil: Brent is falling around 1%, to around $95, and WTI is falling by more than 1%, to around $88. Prices are weighed down by weak data from China and Goldman Sachs’ warning that the market faces a “sizable surplus” next year. Support comes from tension in the Middle East, as Iran has targeted Bahrain for the second time in three days.
- Natural gas: In Europe (NATGAS.EU) the commodity is down around 3.5%, to around €86/MWh, and in the US (NATGAS) it is down around 2.6%, to around $3.15. Pressure on the price comes from record US LNG exports.
- Precious metals: Gold is retreating around 0.3%, to around $3,870 per ounce, and silver is falling more than 1%, to around $47.6. The strong dollar and high bond yields weigh on both metals.
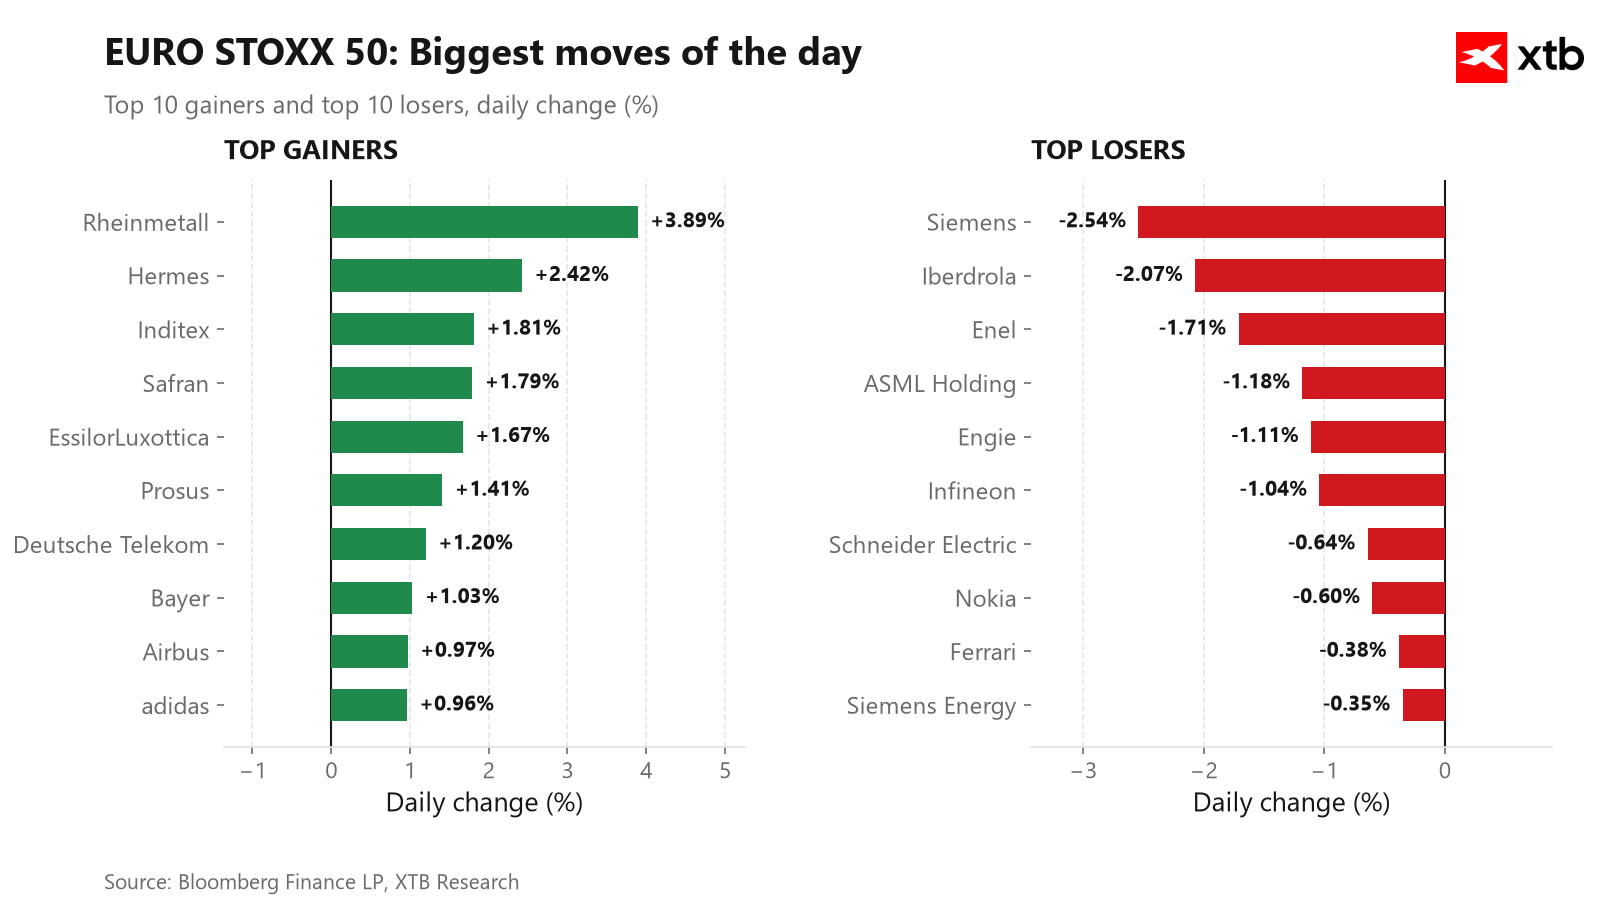
Chart 1 shows the biggest moves among the companies in the Euro Stoxx 50 index.
Company news
Top gainers:
- Rheinmetall (RHM.DE): The share price is rebounding after Friday’s new 52-week low (around €742). The stock is still around 60% below its January peak, after an earlier guidance cut due to delays in ammunition deliveries and Bundeswehr projects. Investors are also looking ahead to the capital markets day on 26 November. (up around 3.7%)
- Hermès (RMS.FR): The company is gaining amid a rebound in the consumer goods sector, which was among the leaders of the European market this morning. Improved sentiment after Morgan Stanley’s forecast also helps. (up nearly 2%)
- Inditex (ITX.ES): The Spanish retailer is holding near record levels, above €60. The market is waiting for nine-month results on 2 December. (up around 1.4%)
Top decliners:
- Siemens (SIE.DE): The company is under pressure after last week’s results, despite record orders and raised medium-term targets. The market is taking profits and reacting to the selloff in AI-related stocks ahead of Nvidia’s results. (down around 2.5%)
- Iberdrola (IBE1.ES): The utilities sector is among the weakest in Europe today. Defensive stocks are losing amid rising bond yields and expectations of rate hikes in the US and the eurozone. (down nearly 2%)
- Enel (ENEL.IT): The Italian group is following the entire utilities sector, which is reacting to the same factors as Iberdrola. (down around 1.2%)



Daily Summary: Tech Stock Selloff Weighs on Markets, Fed Outlines AI Scenarios
European gas drops 6% and tests key support


US OPEN: Tech selloff continues ahead of Nvidia earnings and Anthropic’s debut


⚪Chart of the Day: Silver. The market tests yearly lows, while fundamentals worsen.
The material on this page does not constitute as financial advice and does not take into account your level of understanding, investment objectives, financial situation or any other particular needs.
All the information provided, including opinions, market research, mathematical results and technical analyses published on the website or transmitted to you by other means is provided for information purposes only and should in no event be interpreted as an offer of, or solicitation for, a transaction in any financial instrument, nor should the information provided be construed as advice of legal or fiscal nature.
Any investment decisions you make shall be based exclusively on your level of understanding, investment objectives, financial situation or any other particular needs. Any decision to act on information published on the website or transmitted to you by other means is entirely at your own risk. You are solely responsible for such decisions.
If you are in doubt or are not sure that you understand a particular product, instrument, service, or transaction, you should seek professional or legal advice before trading.
Investing in OTC Derivatives carries a high degree of risk, as they are leveraged based products and often small movements in the market could lead to much larger movements in the value of your investment and this could work against you or for you. Please ensure that you fully understand the risks involved, taking into account your investments objectives and level of experience, before trading, and if necessary, seek independent advice.