


The Hong Kong stock market reopened after the holiday break with a sharp sell-off, with the Hang Seng (HK.cash) falling as much as 3%, marking its weakest session since March 23. Investors are also reacting negatively to Beijing’s latest stimulus measures, which so far have failed to materially improve expectations for economic growth, while elevated US Treasury yields are adding further pressure to sentiment.
- Selling pressure is concentrated primarily in the financial sector: HSBC is down around 5.5%, AIA is falling 4.2%, while Hong Kong Exchanges and Clearing is lower by 1.5%.
- Major technology stocks are also under pressure. Alibaba opened around 2.3% lower, Tencent fell 2.1%, Baidu 3%, Xiaomi 2.5%, JD.com 2.6%, and Meituan around 2%. JD Health is the weakest blue chip, with shares down about 6.9%.
- New World Development stands out against the broader sell-off, rising nearly 10% in early trading. The company announced that it will terminate the contract for the 11 SKIES project ahead of schedule and return the project to the Hong Kong Airport Authority on April 1 next year.
- Another factor weighing on the market is the closure of mainland Chinese exchanges for the holiday period, which limits a potential source of domestic buying support. Higher US Treasury yields are also tightening financial conditions for risk assets and putting additional pressure on valuations across the region.
Beijing fails to convince the market: weak demand, property and technology deepen the pressure
Beijing’s latest package of policy measures has failed to materially improve investor sentiment. Authorities announced additional credit support, measures aimed at the property market and small businesses, as well as infrastructure investment, while the People’s Bank of China cut the one-year pledged supplementary lending rate to 1.5%. The problem is that markets view the measures as too limited to significantly alter the growth outlook or restore confidence in Chinese assets.
The pressure is broad-based. Weak domestic demand remains one of the key problems facing the economy, while the property sector continues to weigh on activity. The CSI 300 Real Estate Index fell as much as 9%, showing that investors remain unconvinced that the new measures will be enough to produce a durable recovery in housing sales and improve conditions for developers. At the same time, the package did not include fresh direct support for equities, limiting its immediate impact on sentiment.
The sell-off has also spread to technology, which had previously been one of the main drivers of China’s equity rally. The CSI Semiconductor Index fell more than 2% and is heading for a quarterly decline of around 32%, while the CSI AI Index dropped 1.2% and is on track for a quarterly loss of roughly 25%. In addition, investor activity is weakening ahead of the week-long holiday break, with combined turnover on the Shanghai and Shenzhen exchanges falling to its lowest level since July 2025.
The sell-off spreads beyond Hong Kong: Chinese stocks fall to a one-year low
In mainland China, the CSI 300 fell as much as 2.4%, dropping to its lowest level in around a year. Chinese chipmakers and optical-component companies also suffered sharp declines. Cambricon Technologies, GigaDevice Semiconductor, Zhongji Innolight and Eoptolink all fell by at least 5%, with concerns over competition and technology geopolitics acting as the immediate catalyst. Reports that Beijing may allow domestic companies to purchase Nvidia’s latest chips have increased pressure on local semiconductor manufacturers, which are already facing intense competition. At the same time, proposed US restrictions targeting Chinese optical companies have further weakened sentiment toward the sector.
Investors also remain disappointed with the outcome of the latest US-China talks. Although the trade truce was extended, the meeting failed to deliver the kind of breakthrough some market participants had hoped for. As a result, weakness is now affecting both Hong Kong and onshore Chinese equities, increasing the risk of a further deterioration in market breadth if pressure on the technology sector persists.
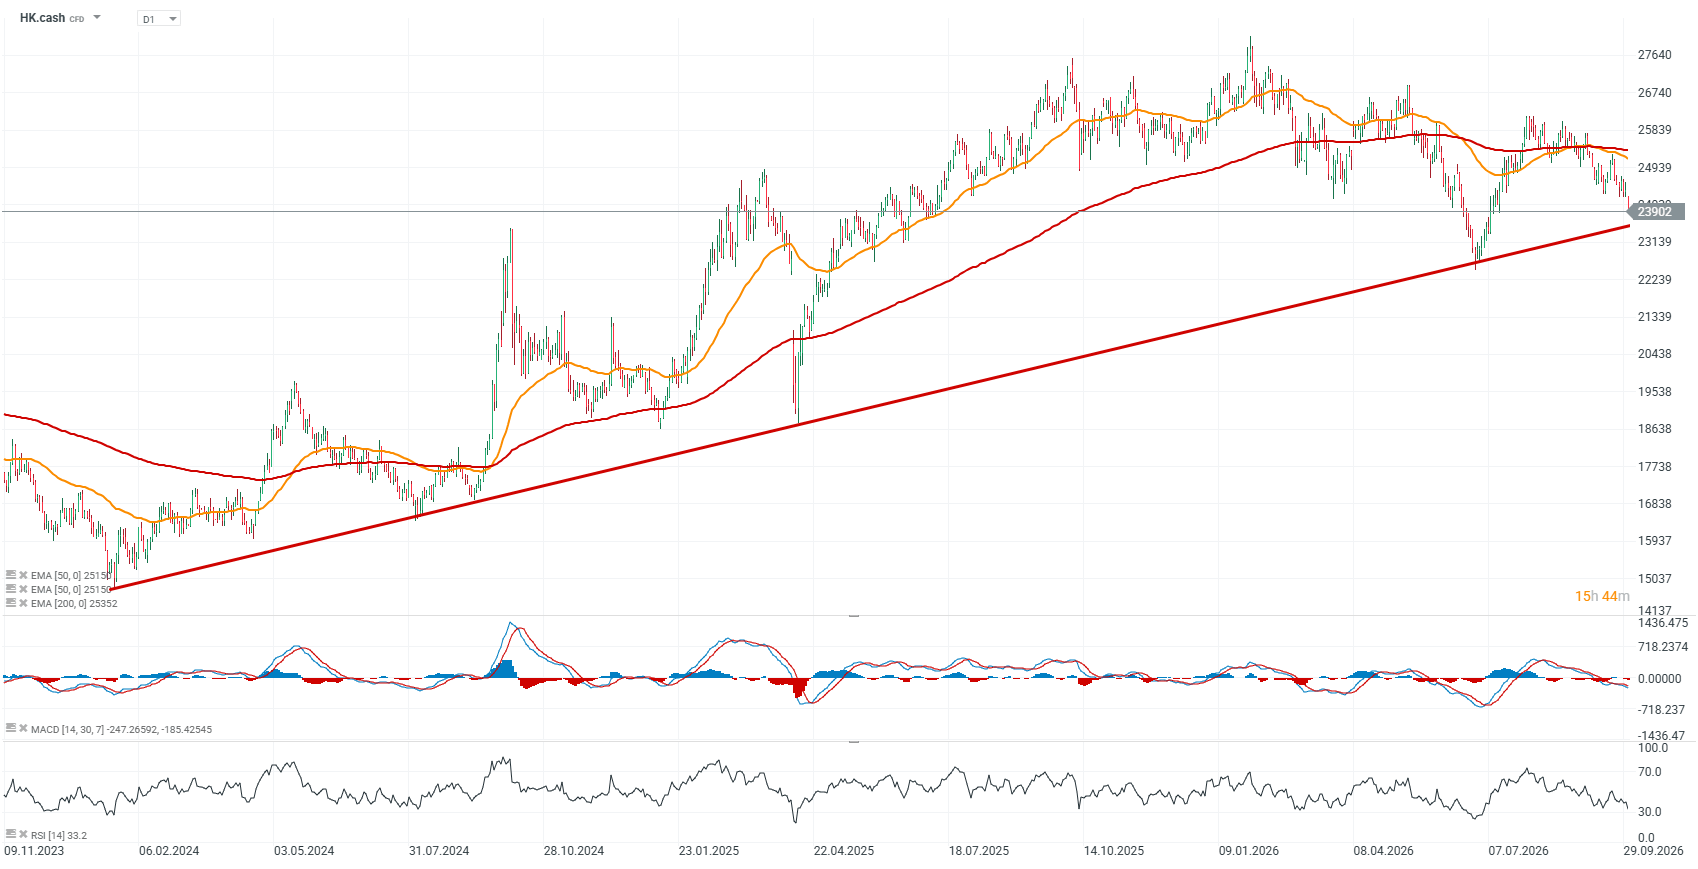
HK.cash chart (D1 interval)
The index has fallen back below the EMA200 (red line) and has continued to extend its losses since then. The key support area now appears to be around 23,500 points, near the trend line, while the first important resistance is located around 24,500 points, where the current downward impulse began. The RSI (14) is approaching near-oversold territory around the 30 level.
 Source: xStation5


Morning wrap: Strong Wall Street, weak Europe and Asia 🚩 NFP to test equity strength



Daily Summary: Wall Street Recovers as Micron Shines and Oil Prices Rise Again
The US has a Diesel problem. Now Europe is being asked to open its reserves


BREAKING: U.S. ISM Manufacturing Data Misses Expectations. Dollar Reacts Sharply
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.