


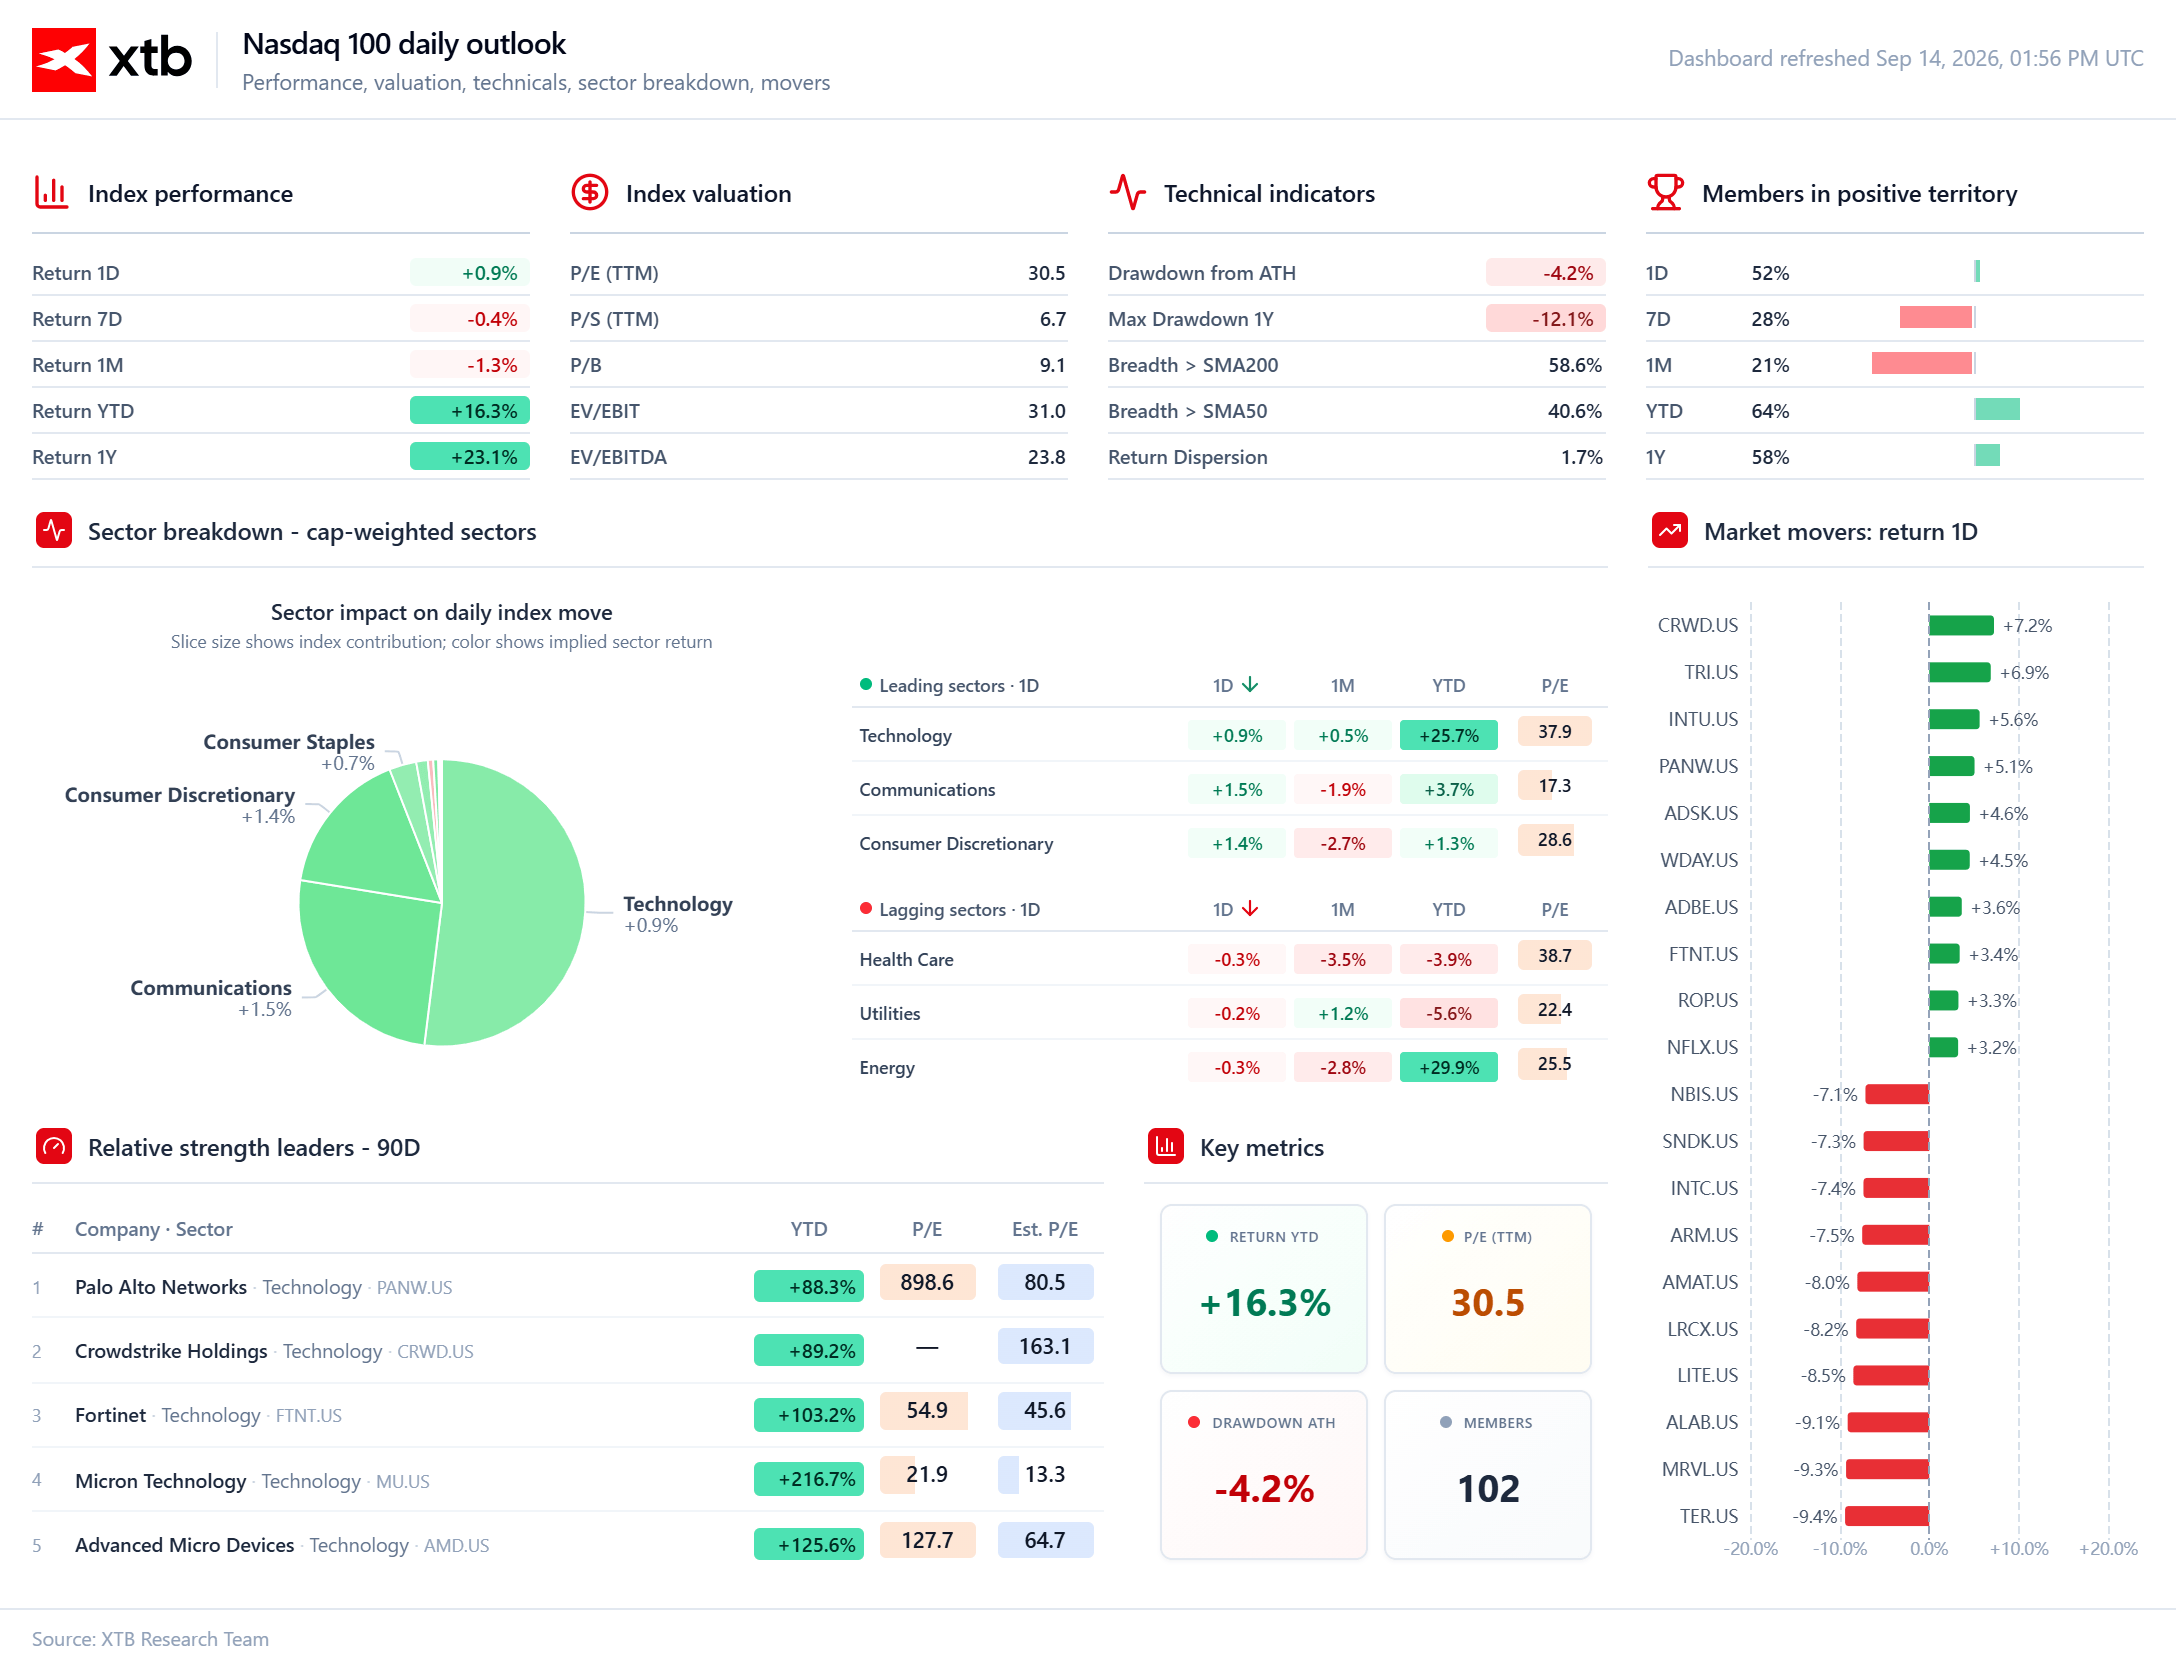
US equity indices begin the first session of the week with a clear selling bias, though it is heavily concentrated in technology. Futures on the tech index are down about 1.3% at the open. US500, US30, and US2000 futures are holding up better, with declines limited to around 0.5%.
- The sharp move focused on tech stocks was driven mainly by a series of comments and declarations from AI industry leaders, including representatives of OpenAI, Anthropic, and Elon Musk. The communication between the parties revolved around the idea of “adjusting the pace” of AI development.
- This was not said explicitly or directly, but the context clearly suggested that the largest AI companies are pushing for an industry-wide “slowdown” in the development of models and agents so that audit, monitoring, and cybersecurity methods can keep up.
- Markets also face a number of fleeting yet highly important scenarios to price ahead of the upcoming Fed meeting. Wednesday’s press conference could either dispel doubts or deepen investors’ concerns about the future path of monetary policy. Given persistent pressure from energy prices, inflation, and a relatively strong labor market, the market is currently pricing in about a 90% probability of a 25 bp rate hike.
- After a brief pullback in oil, prices resumed their rise, reaching around USD 108 per barrel near the open. European gas is also up sharply, reaching around EUR 83. Yemen’s Houthis reportedly seized a significant part of the Red Sea coastline, which could threaten commercial shipping in the region. There are currently no confirmed cases of attacks or attempts to halt traffic there, but Saudi Arabia confirmed damage to the East-West pipeline over the weekend. Initial estimates suggest repairs will take several weeks, while facilities and storage on the Red Sea side reportedly have supplies for a few days of exports.
Company news
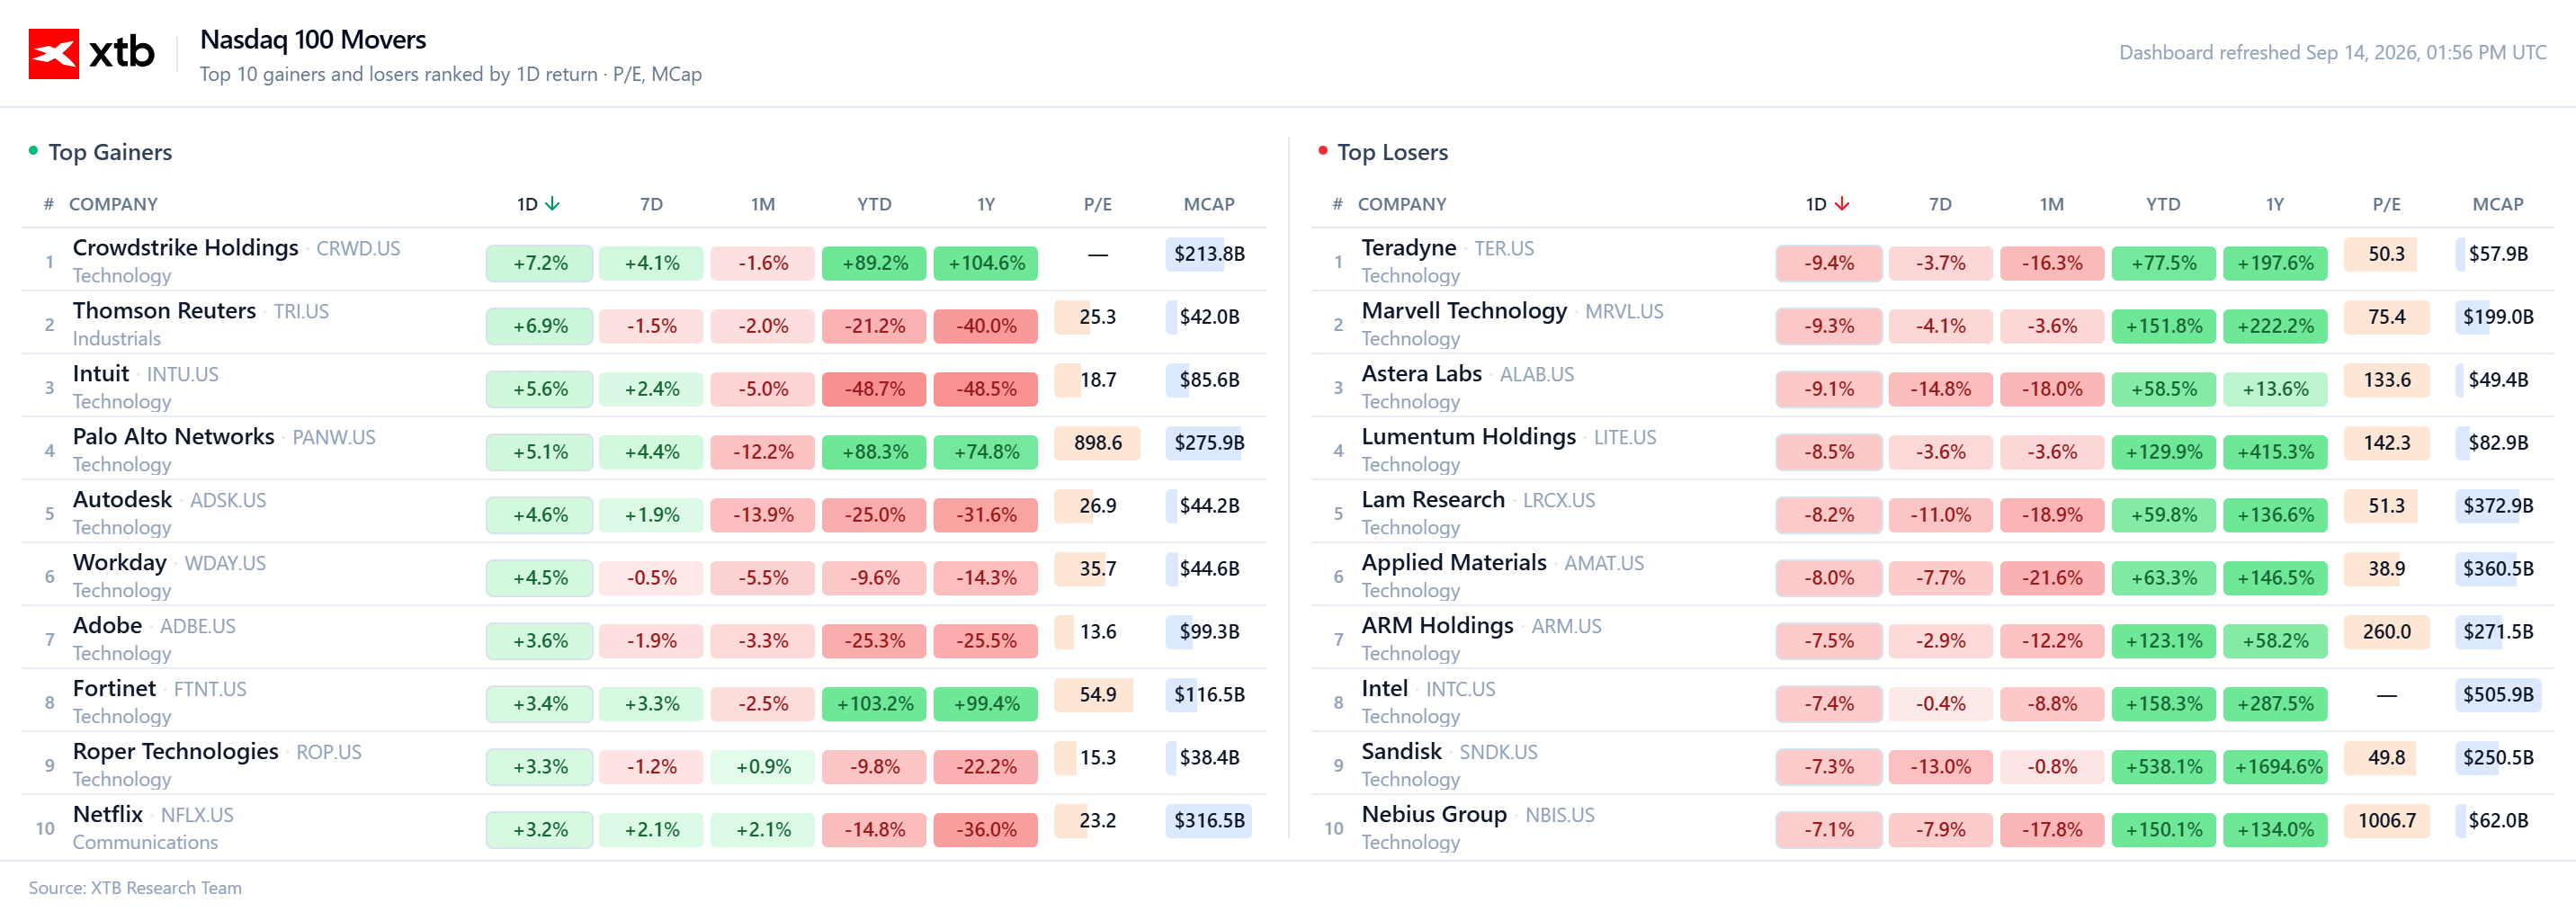
- Semiconductors and AI: Statements from representatives of Anthropic, OpenAI, and xAI triggered a sharp correction in assets linked to AI growth. Neo cloud companies are down about 6% to 8%, and memory and semiconductor names are down about 5%. Hyperscalers do not appear to be reacting to the news.
- Baldwin Insurance (BWIN.US): The Financial Times reports that Michael Dell is said to be nearing the completion of a deal to acquire the company. Shares are up about 7%.
- Palo Alto (PANW.US): Cybersecurity stocks are rising on the back of a perceived reduction in pressure from the AI sector. The company and the broader SaaS sector are up about 5% to 6% at today’s open.
- HP (HPQ.US): The computer components maker is extending losses versus the rest of the sector due to an additional negative catalyst, a publication by an investment firm. Shares are down about 10%.
- Rumble (RUM.US): The stock is up by more than a dozen percent at the open after announcing a computing power contract with Anthropic. The AI lab signed a contract with the company worth USD 13.7 billion.
- Oracle (ORCL.US): The company’s CEO, Larry Ellison, reportedly withdrew plans to sell 50 million shares, according to Bloomberg.
- Meta (META.US): The stock is up about 2% after launching its AI agent called “Muse.” Several investment banks reiterate their optimistic stance on the shares and highlight the strategic significance of a modest breakthrough in the company’s position in the AI race.
Technical analysis: US100 (D1)
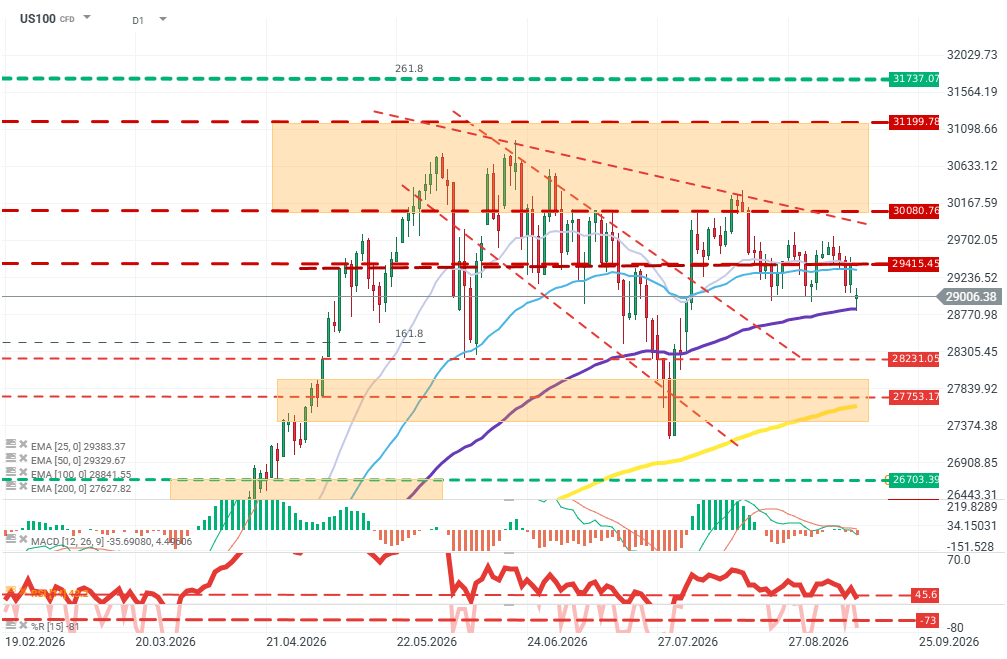
Price is currently testing the lower boundary of a tight consolidation between roughly 29,000 and 30,100. The EMA100 continues to act as a strong support zone, as seen in today’s session. The short-term downtrend is gaining momentum, but the long-term outlook remains bullish in terms of EMA200 momentum. The RSI (14) is currently below the midpoint, around 45. This is not yet an oversold level, but a sharp sell-off from here could bring an equally sharp rebound. Source: xStation5
Macroeconomic data
- Canada released a set of inflation data that may have limited market impact but can provide valuable insight into the economic situation, including in the US.
- CPI inflation held at 3% year over year.
- Core inflation rose to 2.4% year over year.
- Manufacturing sales fell 0.4% in July.



🔴Daily summary: Wall Street ignores hawkish inflation, oil falls sharply despite geopolitical tensions
Breaking: Time for a tough call for Fed as monthly hotter Core CPI tests market expectations

🟡Gold Rebounces Ahead of CPI
Oil continues to rise
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.