


The major U.S. indices are gaining today, while expectations for the Fed have clearly eased. First came a better-than-expected PCE reading, which failed to confirm concerns about inflation reaccelerating. A few days later, weaker NFP data showed that the U.S. labor market is also beginning to lose momentum. Bets on a rate hike at the next meeting have almost completely disappeared from the market.
This is particularly good news for companies whose valuations are most sensitive to the cost of money. With technology stocks trading at high multiples, another rate hike would have been an additional burden. That scenario is now moving further into the background. The Fed can wait for more data and assess whether the weaker labor market is indeed signaling a broader economic slowdown.
Oil prices have also stopped adding to the pressure. Brent crude has fallen below $100 a barrel, giving back part of its earlier gains. If this move continues, it will provide another argument for a more cautious approach from the Fed. Lower energy prices mean less pressure on consumer prices and, consequently, a lower risk that the central bank will have to return to rate hikes.
High Treasury yields, however, continue to hang over Wall Street. Ten-year yields remain at levels that can weigh on equity valuations and provide an attractive alternative for some investors. For today's session, however, this is not enough to stop the gains. The market has received a clear signal that another rate hike is not currently the base-case scenario.
The third-quarter earnings season is only beginning to pick up pace, and corporate results will soon have a greater say in market direction again. For now, Wall Street is benefiting from a straightforward setup: inflation is not giving the Fed a new reason to act, the labor market is weakening, and oil prices have stopped rising. Under these conditions, equities have significantly more room to move higher than they did just a few weeks ago.
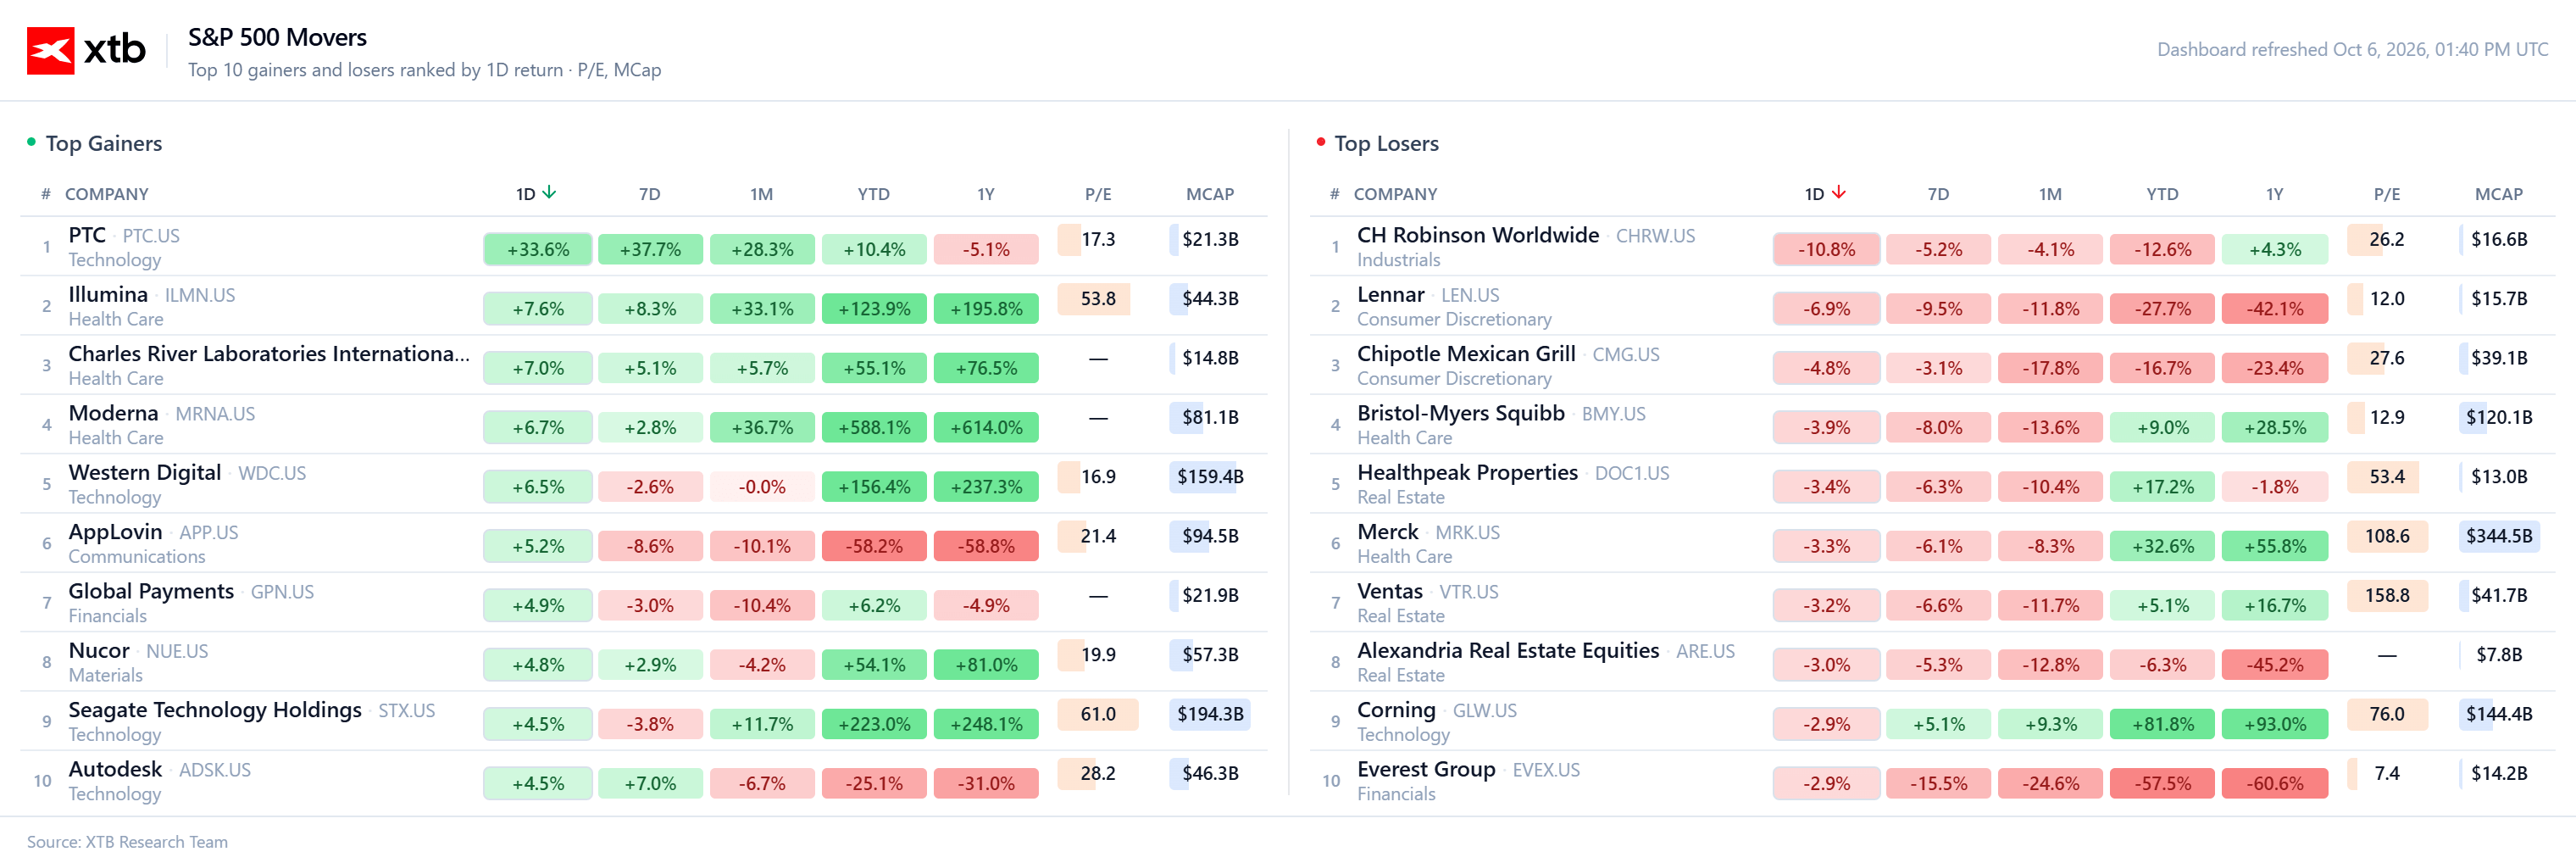
Source: XTB Research
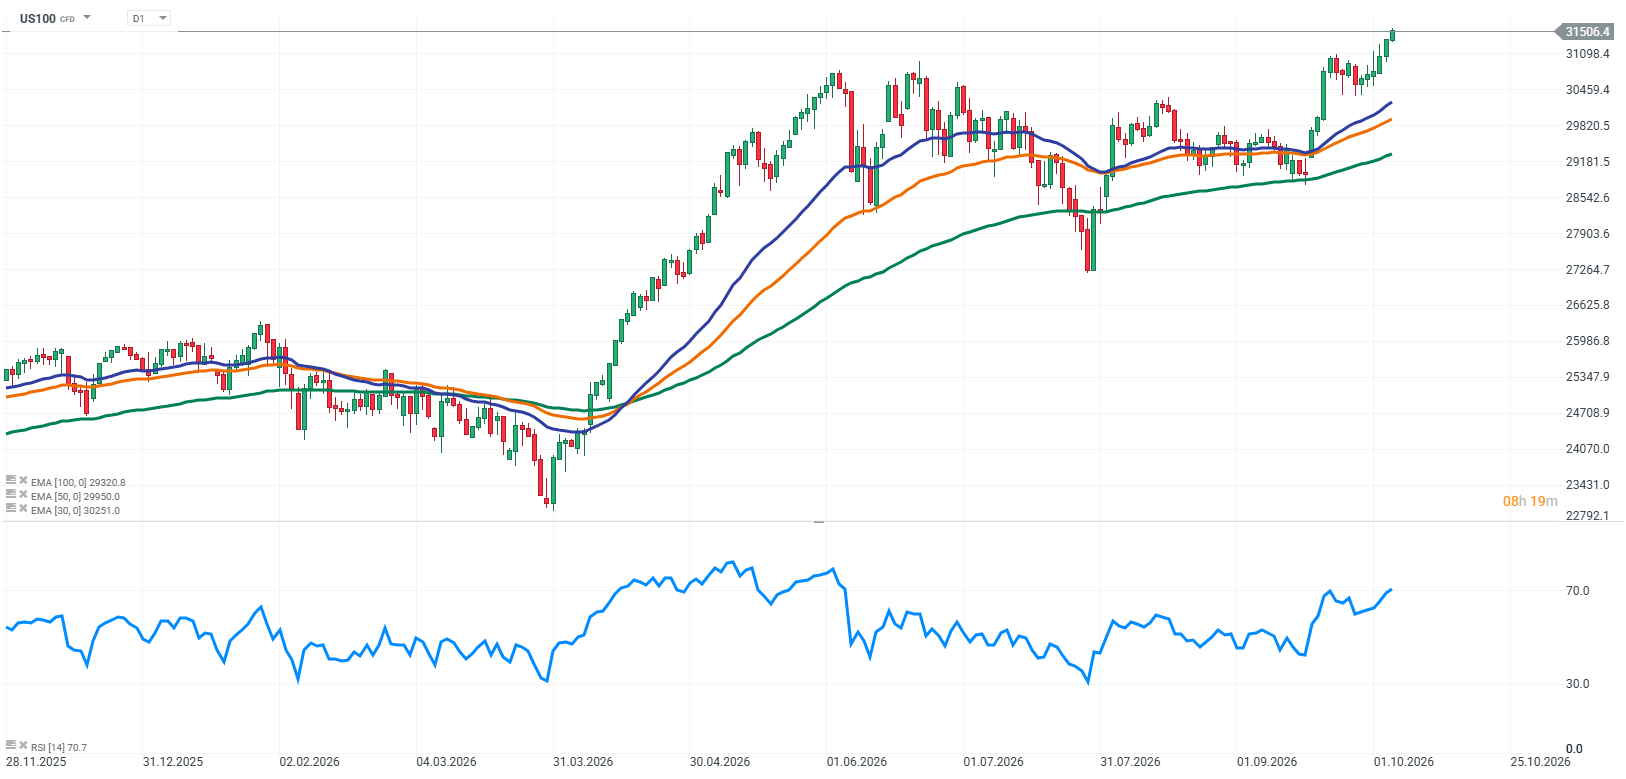
S&P 500 (US500) futures are gaining slightly today, as the market is increasingly less concerned about another Fed rate hike at the October meeting. Expectations for rates to remain unchanged have risen following weaker U.S. labor market data, supporting sentiment on Wall Street.
Source: XTB Research
Company News:
Micron (MU.US) is trading lower today, with shares under pressure following a strong rally in the memory sector at the beginning of the month. Investors are taking some profits and remain cautious ahead of results from Asian memory manufacturers, although positive recommendations continue to support the long-term outlook for the company.
AMD (AMD.US) is gaining around 2% today, outperforming parts of the semiconductor sector. The stock is being supported by plans to increase chip supply in 2027, which should allow the company to better meet rapidly growing AI-related demand.
Sandisk (SNDK.US) is also trading under pressure today, in line with the broader memory segment. The decline comes after a strong rally in the shares and amid a more cautious approach from investors toward the sector, despite recent improvements in recommendations and favorable prospects for the NAND market.
Uber (UBER.US) is gaining after announcing the $2.3 billion acquisition of ezCater. The deal strengthens Uber's delivery and business services segment, while the company also expects to improve margins through the high value of orders handled by the catering platform.
ServiceNow (NOW.US) remains in focus today following a recent downgrade, primarily related to the company's high valuation. At the same time, the shares are benefiting from broader demand for technology stocks, while investors continue to see potential in the development of automation and agentic AI.

Marvell: Memory-market problems and opportunities

US trade deficit larger than expected 🗽 US indices hit all-time high



Oil falls below $100🚨
Morning Wrap: Stock Indices Rise as Bonds Extend Their Losing Streak (06.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.