


We are facing the most anticipated central bank meeting of 2026. On Wednesday, the Federal Reserve will announce its decision on interest rates. The market currently seems almost convinced that the statement, scheduled for release at 7:00 PM, will mention a 25 basis point rate increase, the first since July 2023.
What does the data say?
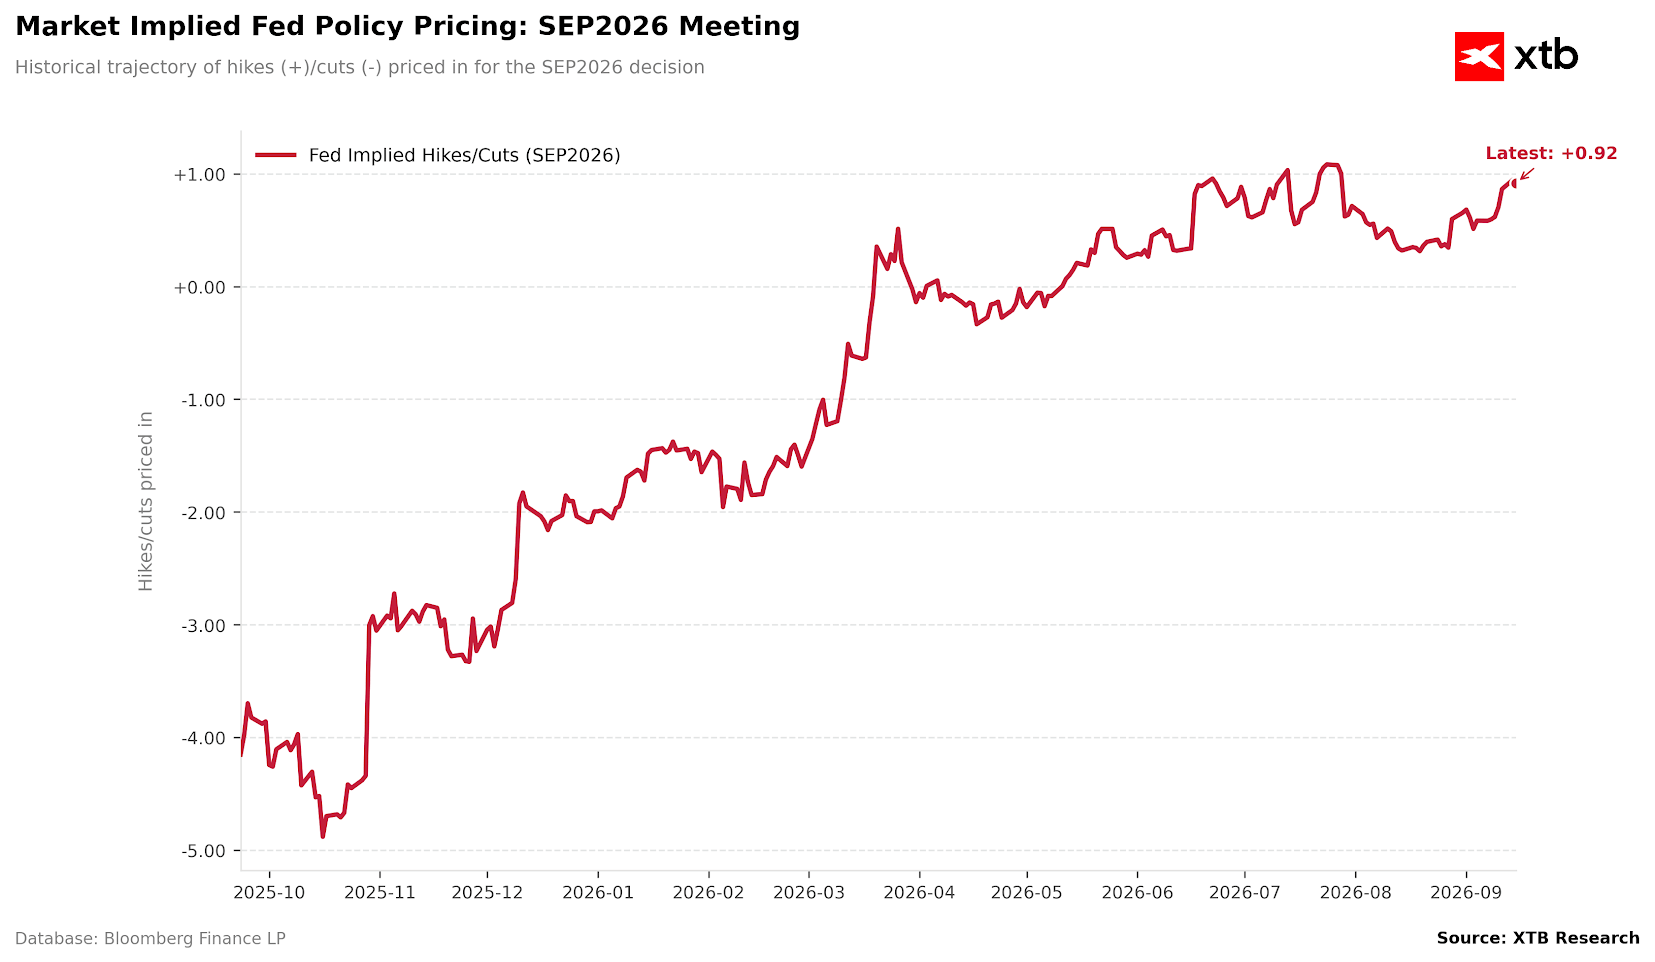
The rise in bets on a rate hike has been very dynamic in recent days, which appears somewhat surprising given that fundamentals have largely remained unchanged.
Figure 1: Change in Market-Implied Probability of the September Fed Rate Hike (2025 - 2026)
 Source: XTB Research, 15.09.2026
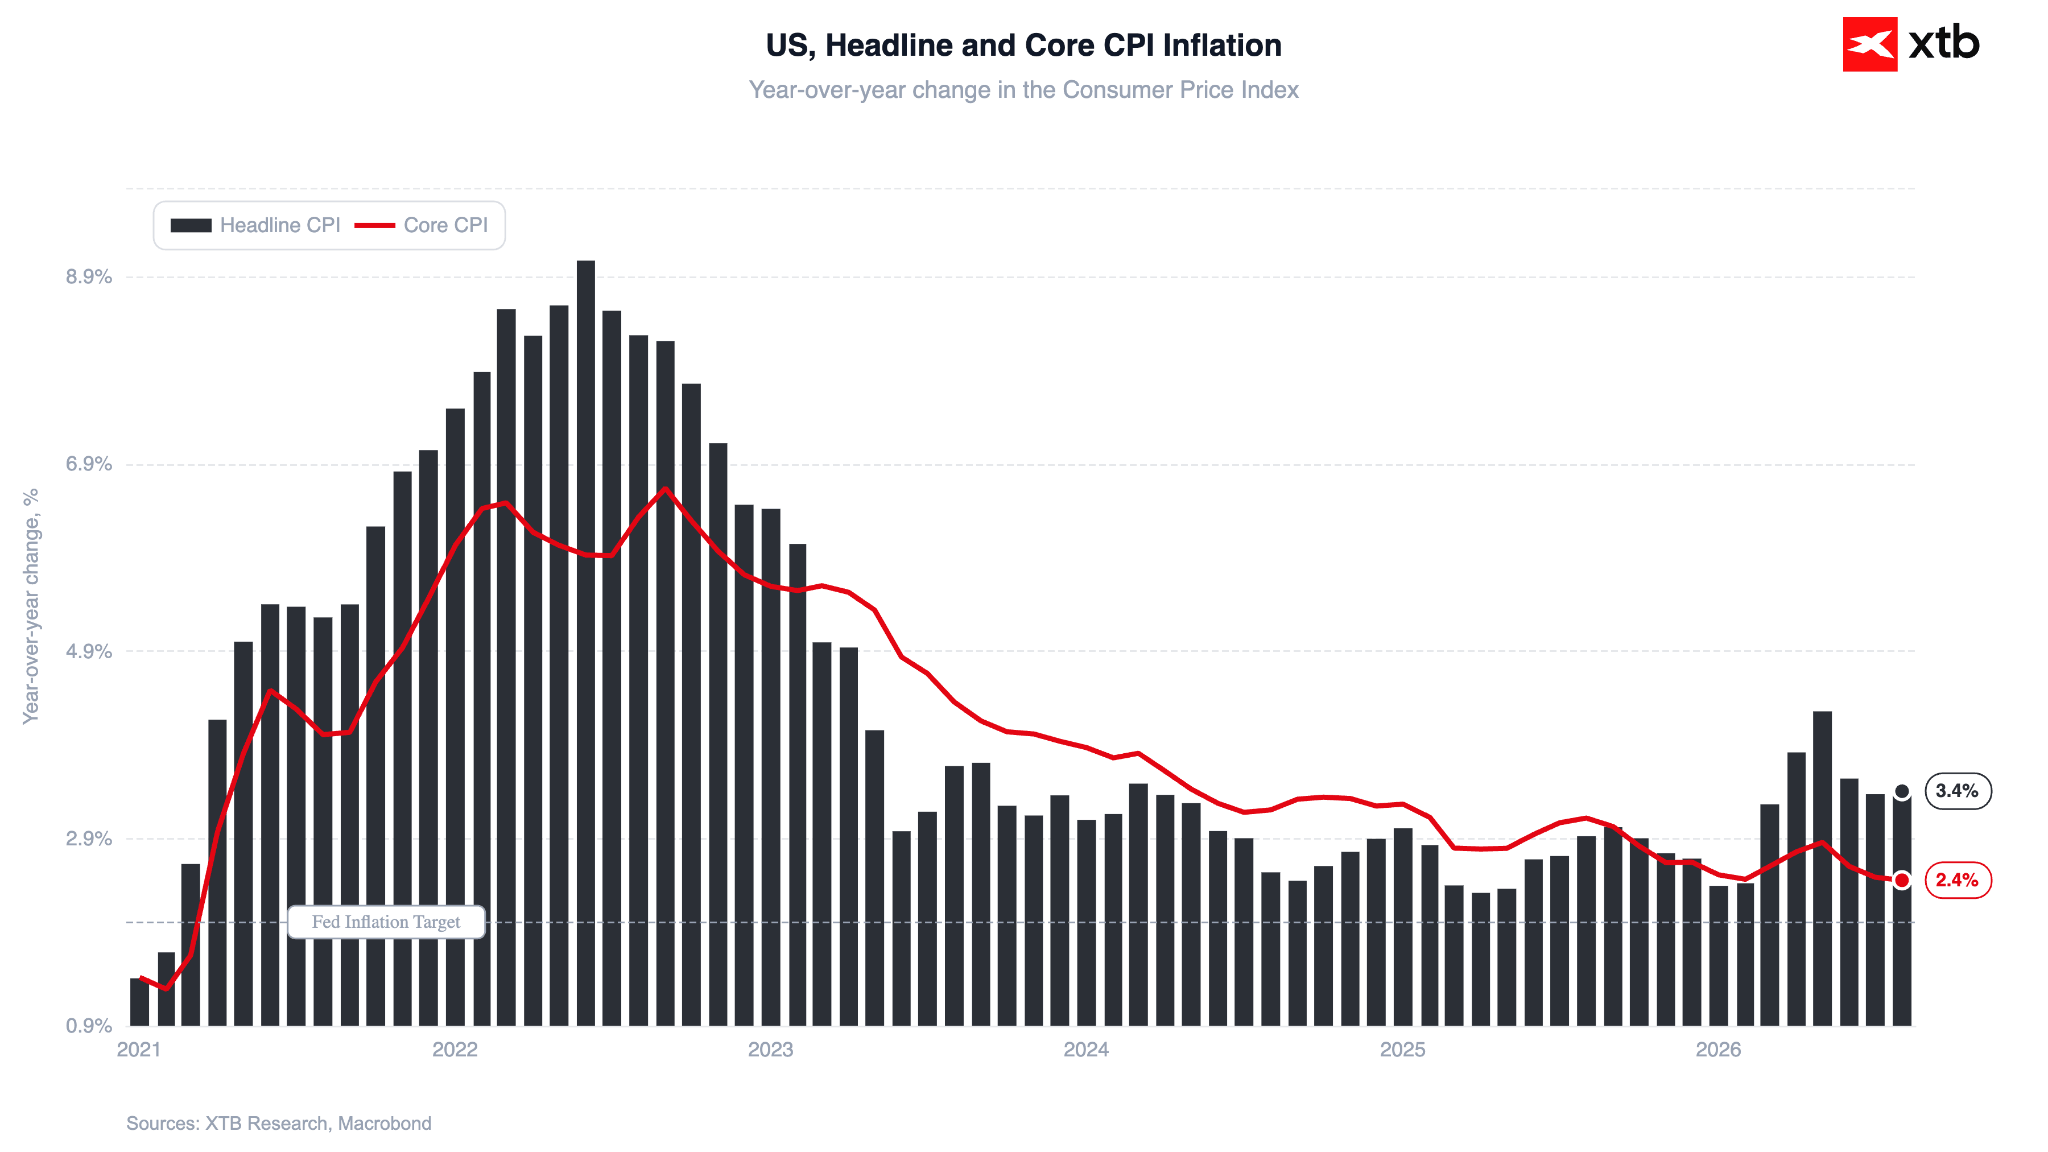
Last week's inflation reading, which according to Christopher Waller was supposed to tip the scales one way or another, did not provide a definitive answer, showing a decline in core inflation to 2.4% year-on-year. Markets focused on the slightly higher-than-expected monthly rise (0.3%), though in our view this is insufficient to prove the necessity of a rate hike.
Figure 2: CPI Inflation in the United States (2026 - 2027)
 Source: XTB Research, 15.09.2026
Arguments for monetary tightening can be found in elevated services sector inflation (3.1%), but here too momentum is not overly concerning. According to the Fed Wage Growth Tracker, wage growth is accelerating (4.1% in August), which could stimulate consumption in the coming months, though current levels (less than 1% in real terms) do not seem poised to fundamentally alter the outlook. This is particularly true given that American consumer spending in recent months (and indeed quarters) has relied heavily on dwindling savings that will sooner or later need to be rebuilt.
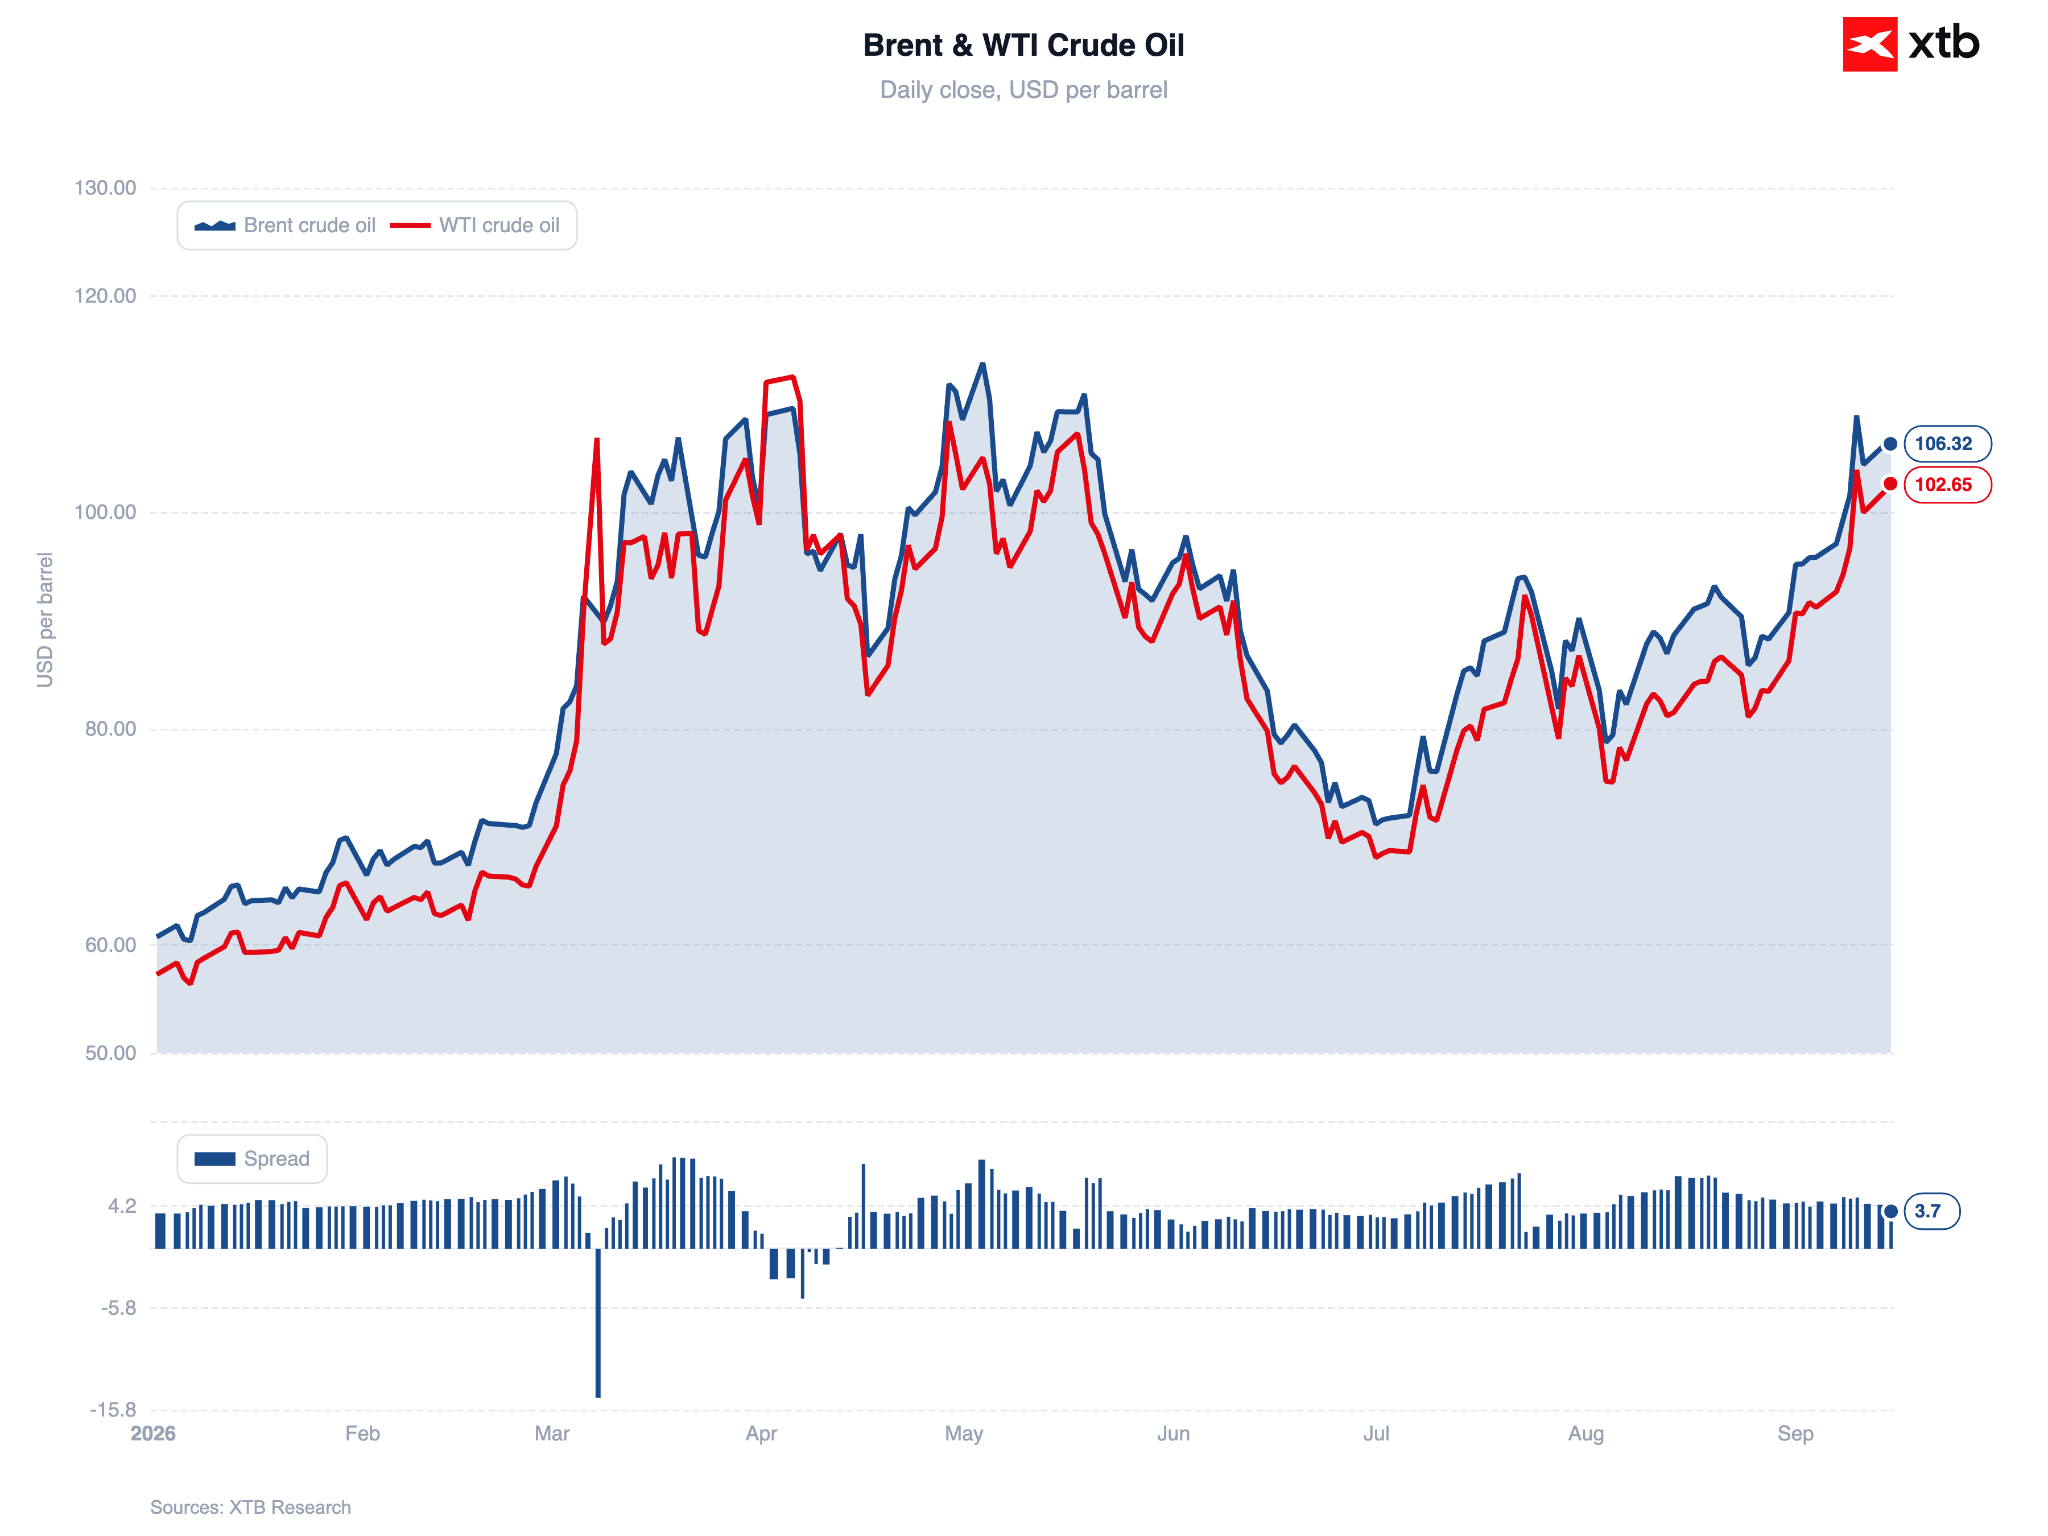
This does not mean, of course, that a rate increase is unwarranted or macroeconomically irrational. It can be justified in many ways. A key factor that could explain an upward move is the tight situation in energy commodity markets. High prices for crude oil and LNG have not yet spilled over into the broader US economy to a significant degree, but an intensification of this process in the coming months cannot be ruled out.
The Fed could certainly opt for a hike as a form of front-loading, acting proactively to prevent the potential need for much sharper tightening in the future. If the Fed indeed decides on such a move on Wednesday, it may raise questions as to why it did not hike in July, as macroeconomic data published since then have offered little additional support for the tightening thesis. Front-loading was, in fact, the argument presented at the time by policymakers who broke consensus and voted for a hike.
Figure 3: Brent and WTI Crude Oil Prices (2026)
 Source: XTB Research, 15.09.2026
The decision will be perceived as politicised under any scenario
From a macroeconomic perspective, the decision can be viewed through various lenses across a broad range of data. However, the discourse surrounding the meeting, inflamed by recent comments from President Trump and the White House's chief economic advisor, Kevin Hassett, means that under any scenario the move will be seen as politicised. Crucial in this context, of course, are the upcoming mid-term elections.
Although Hassett stressed that President Trump "100% respects Warsh's independence" and gives him "100% support", he also noted that the President would not be "very happy" if a rate hike actually occurred. Markets remember well the pressure faced during the final months of his term by former Fed Chair Jerome Powell, who in Trump's view kept interest rates insufficiently low. It is also impossible to ignore the context surrounding Lisa Cook, who was "fired" by President Trump. Quotation marks are deliberate here: the ruling was later overturned by the Supreme Court, and Cook remains an FOMC member participating in Wednesday's deliberations.
If a rate hike does happen, as many indicators currently suggest, we can expect another tirade from the US President. An intriguing question is how Warsh himself would be treated by Trump.
It is worth recalling that despite his hawkish past (during his tenure on the FOMC from 2006 to 2011, he advocated for higher interest rates despite the Global Financial Crisis), Warsh often signalled support for rate cuts before taking office. Just over a year ago, he openly aligned himself with the President, stating on FOX News that Trump's frustration with Powell's handling of monetary policy was fully justified. At the time, he criticized the institution for reducing rates too slowly and relying excessively on backward-looking economic data.
For the Fed and Warsh himself, raising rates is the lesser of two evils
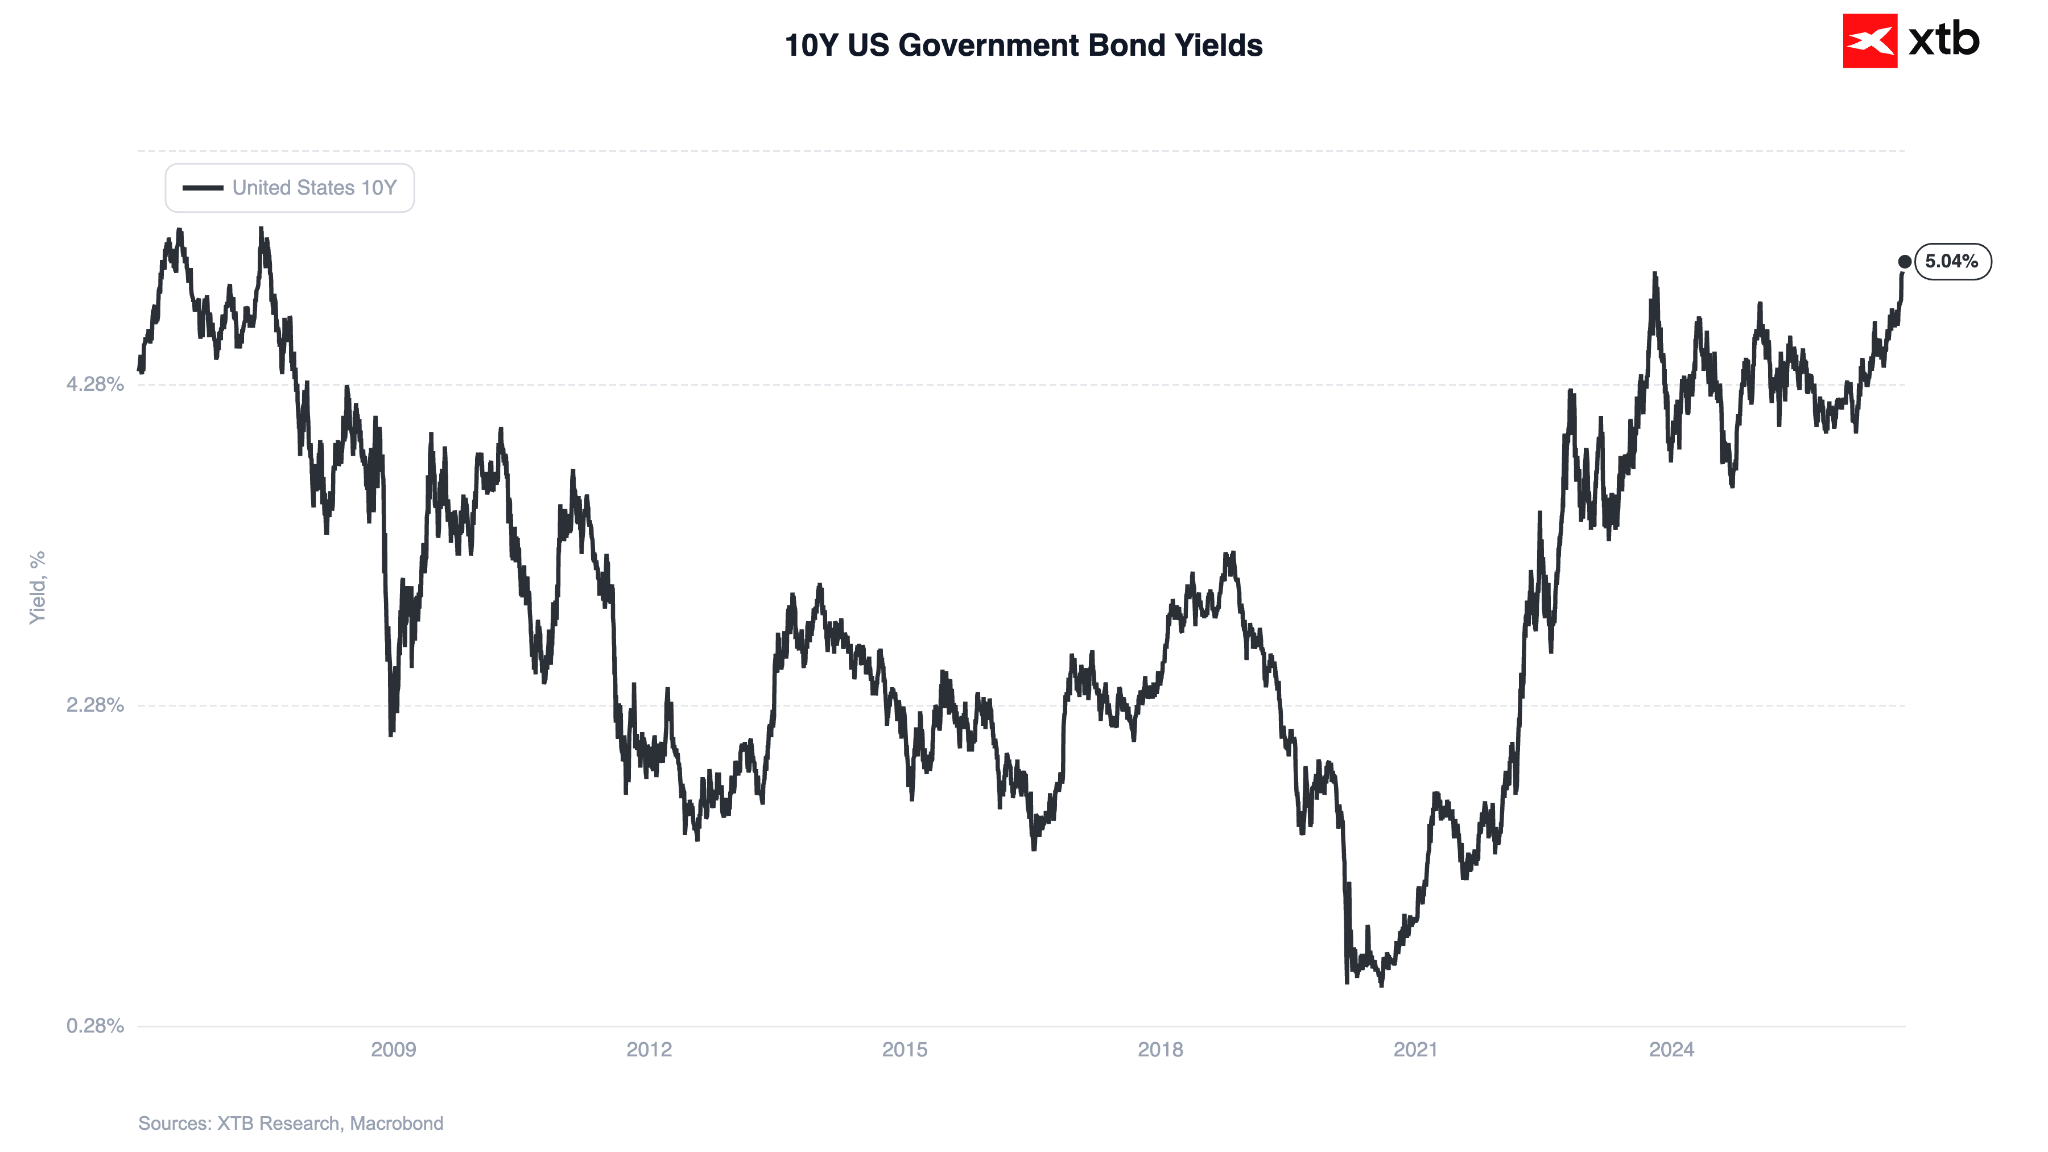
A pause could be interpreted by markets as the Fed caving to pressure from Donald Trump, signalling a loss of independence for the world's most critical financial institution. This would result in a further rise in long-term bond yields (with 10-year Treasury yields reaching their highest level since 2007 today) and a revival of the debasement trade, a strategy involving a shift away from fiat currencies towards hard assets with limited supply, such as precious metals and Bitcoin.
Figure 4: US 10-Year Treasury Yields (2006 - 2026)
 Source: XTB Research, 15.09.2026
A rate hike does not necessarily mean a stronger dollar
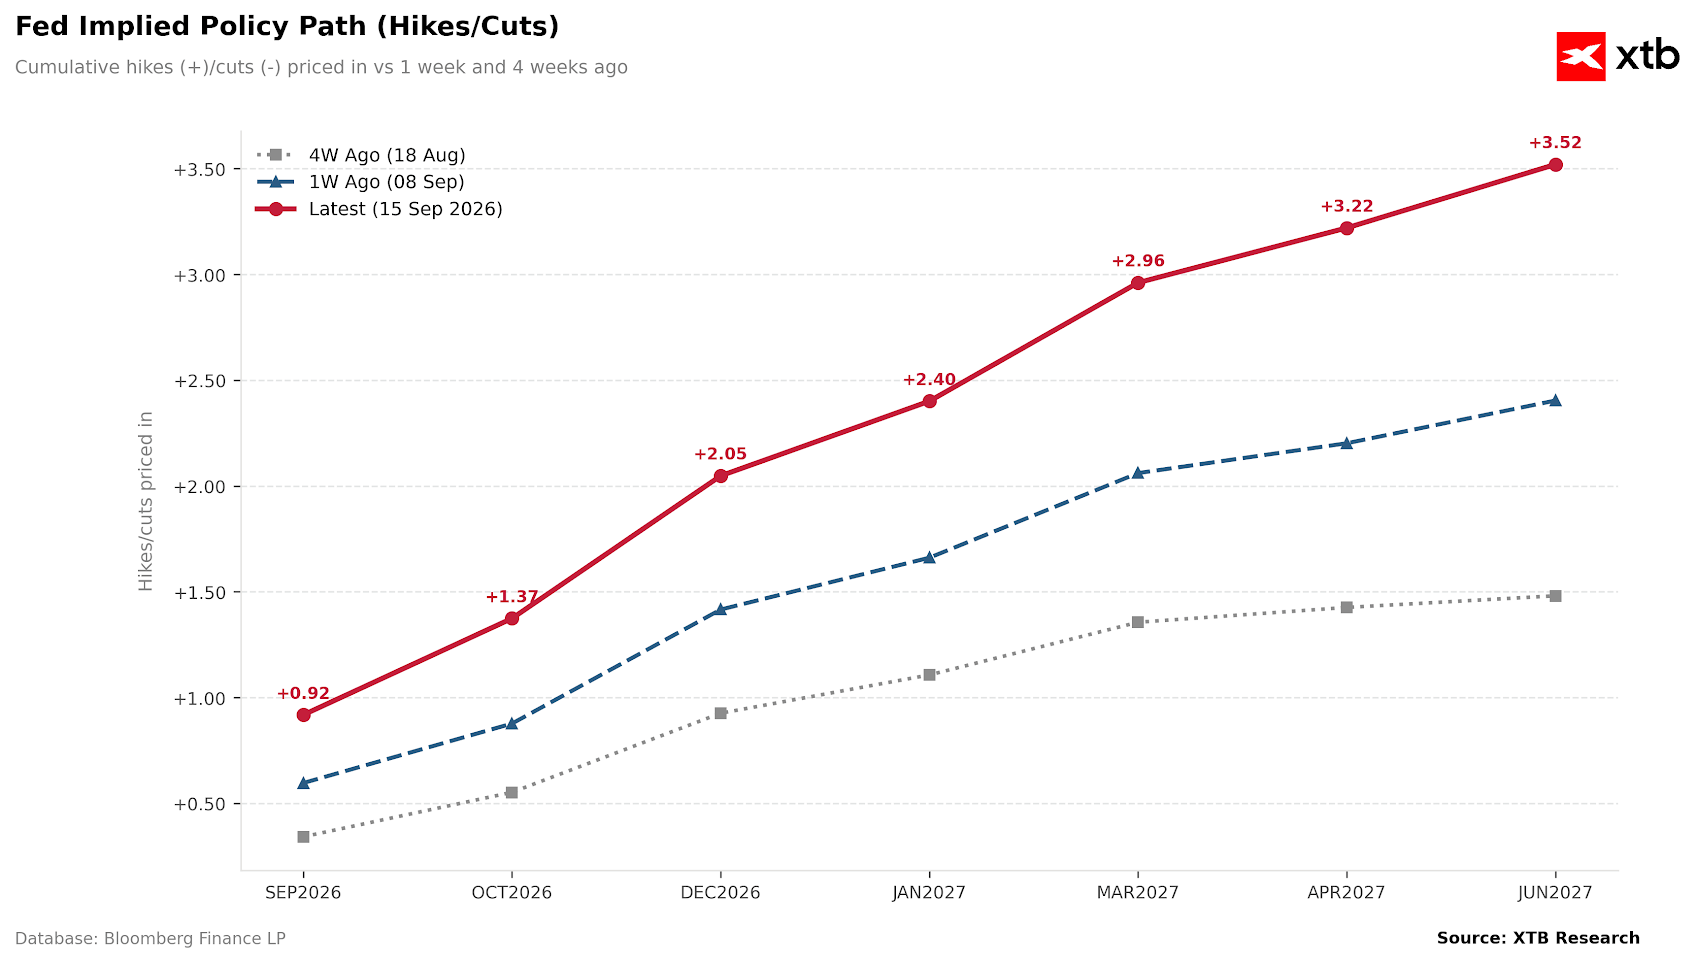
Raising rates does not automatically guarantee an appreciation of the American currency. Given that such a move is almost fully priced in, a relatively hawkish and, above all, credible narrative is also required. If Warsh, as in July, fails to convince the markets, bets on further rate hikes could fall, putting pressure on the US dollar.
Figure 5: Market-Implied Fed Rate Path (2026 - 2027)
 Source: XTB Research, 15.09.2026
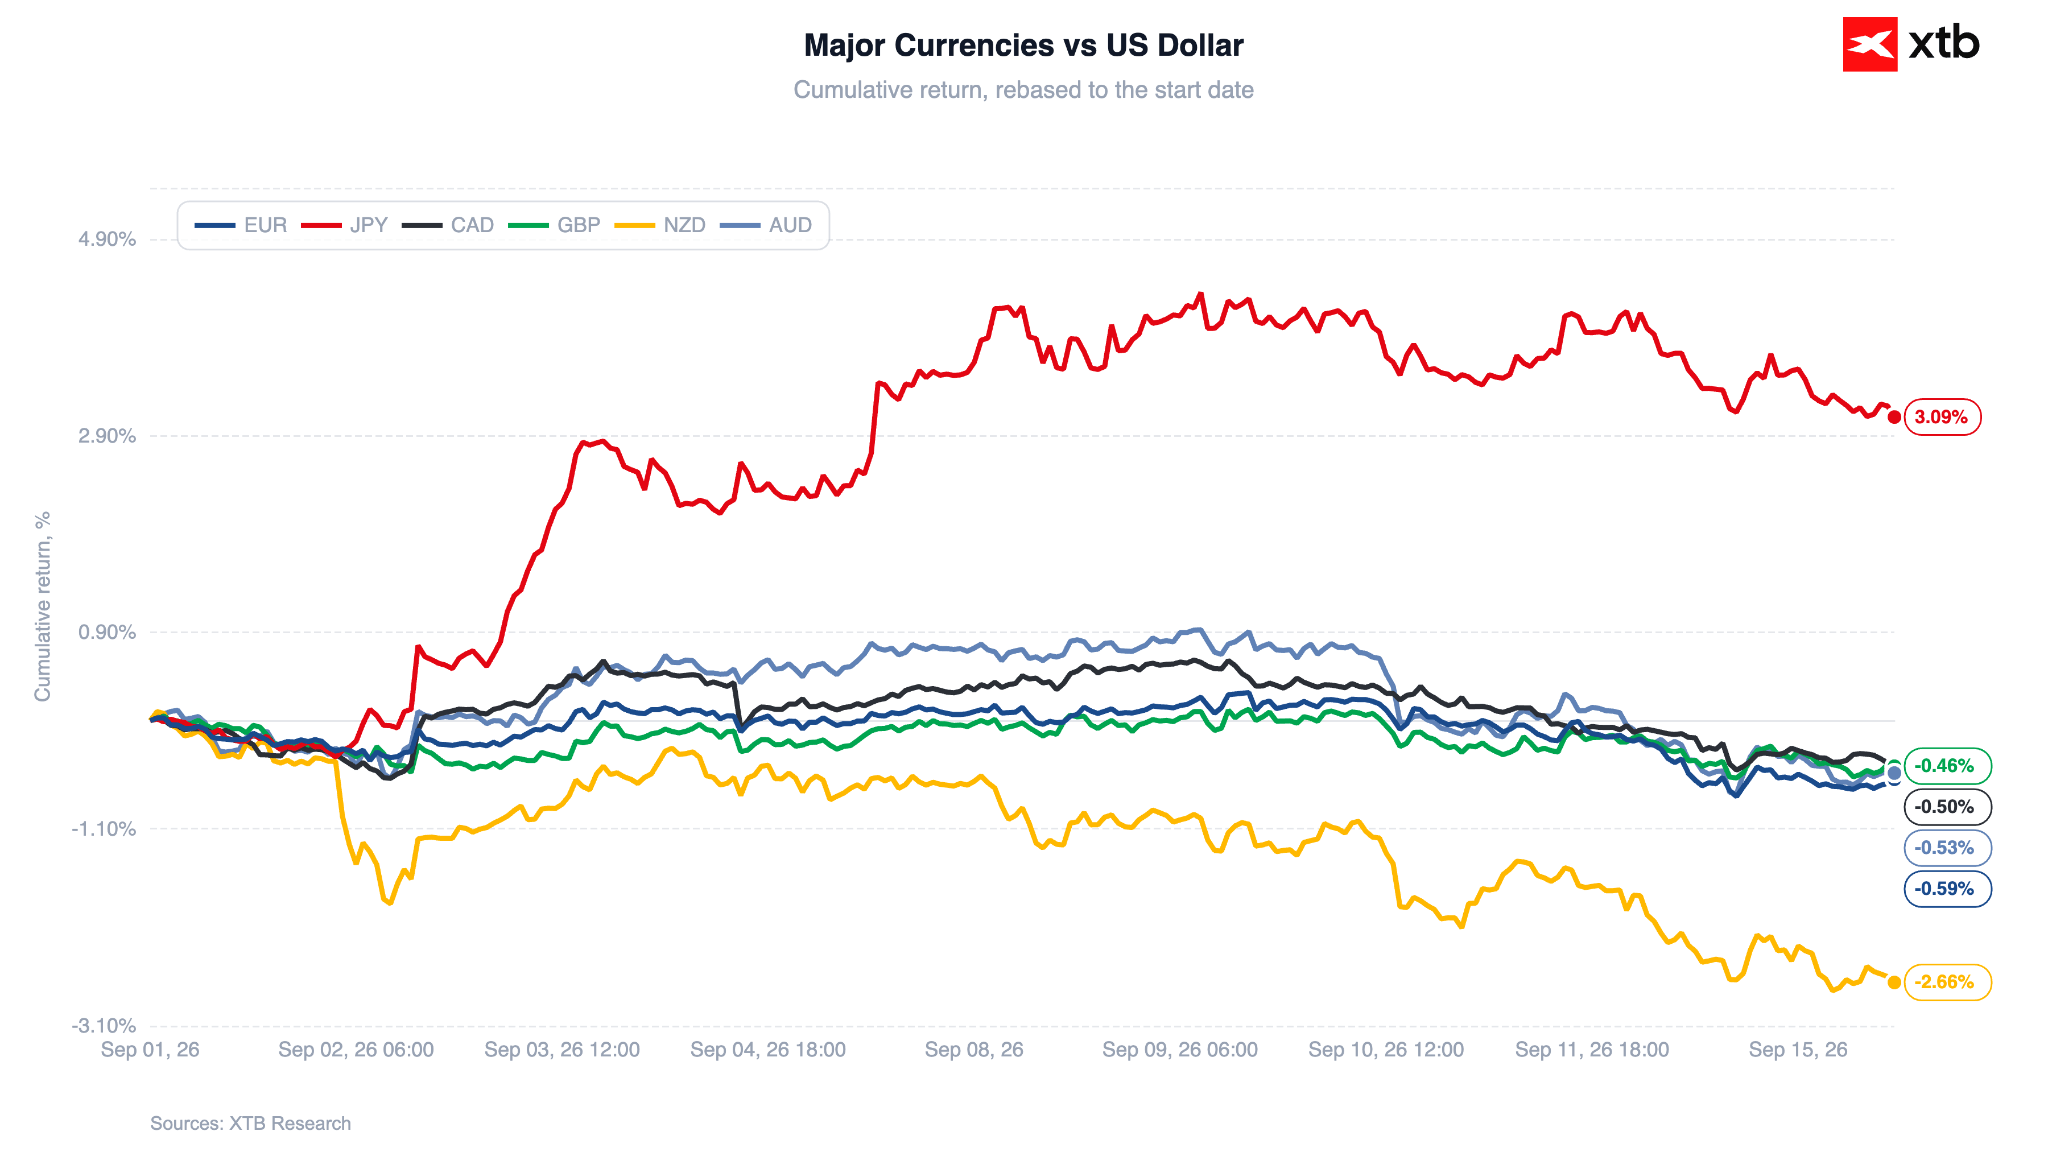
This seems plausible. The hawkish repricing seen recently was, in our view, overly aggressive. We do not expect the market baseline scenario of four Fed rate hikes before the end of the first half of 2027 to actually materialise. A retreat in rate hike expectations would naturally not be good news for the dollar.
Figure 6: Major Currency Performance Against the US Dollar (01.09.2026 - 15.09.2026)
 Source: XTB Research, 15.09.2026
—
Michał Jóźwiak, Financial Markets Analyst, XTB


🟡⬇️Gold loses ahead of Fed decision

Chart of the Day: Gold at five-week lows - what stands behind the decline? (15.09.2026)



Economic Calendar: Market awaits Fed and BoE decisions (15.09.2026)


Morning Wrap: Brent at $107, AI sell-off (15.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.