



Airbnb shares (ABNB.US) are up 12% following the release of Q3 2026 results, with the company recording its fastest revenue growth in more than three years. Revenue increased 19% year-over-year to $4.9 billion, while Gross Booking Value (GBV) climbed 21% to $27.7 billion, confirming accelerating demand for the platform's services.
Importantly, growth was broad-based across all operating regions, including mature North American markets, where nights booked increased at their fastest pace in four years. Airbnb is also increasingly leveraging artificial intelligence to reduce customer support costs and develop new features without proportionally increasing operating expenses.
The positive outlook is further supported by upgraded full-year guidance and a new share repurchase authorization of up to $12 billion.
Airbnb: Key Financial Results for Q3 2026
-
Revenue: $4.9 billion, up 19% year-over-year, marking the fastest growth in more than three years.
-
Gross Booking Value (GBV): $27.7 billion, up 21% year-over-year, supported by higher booking volumes and a moderate increase in Average Daily Rates (ADR).
-
Nights and Seats Booked: increased 16% year-over-year.
-
Net income: $1.9 billion, representing a net profit margin of approximately 39%.
-
Adjusted EBITDA: $2.5 billion, up 22% year-over-year.
-
Adjusted EBITDA margin: 52%, highlighting exceptionally strong profitability during the seasonally important quarter.
-
New users: first-time bookers increased 13% year-over-year, the fastest growth since early 2022.
-
Share buybacks: management authorized an additional share repurchase program of up to $12 billion.
Airbnb Guidance for Q4 and Full-Year 2026
-
Q4 revenue: $3.22–3.28 billion, representing expected year-over-year growth of 16–18%. The company also raised its full-year outlook, now expecting revenue growth in the high teens.
-
Gross Booking Value (GBV): expected to grow at a mid-teens percentage rate year-over-year.
-
Booking volumes: expected to increase by at least a low double-digit percentage year-over-year, alongside a moderate rise in Average Daily Rates.
-
Q4 adjusted EBITDA: expected to increase year-over-year, although the EBITDA margin may decline slightly compared with Q4 2025, partly due to the timing of marketing expenditures.
-
Full-year 2026 adjusted EBITDA margin: approximately 36%, implying an improvement in profitability compared with the previous year.
-
Currency impact: favorable foreign exchange movements are expected to contribute approximately 2 percentage points to fourth-quarter revenue growth, after accounting for the company's hedging program.
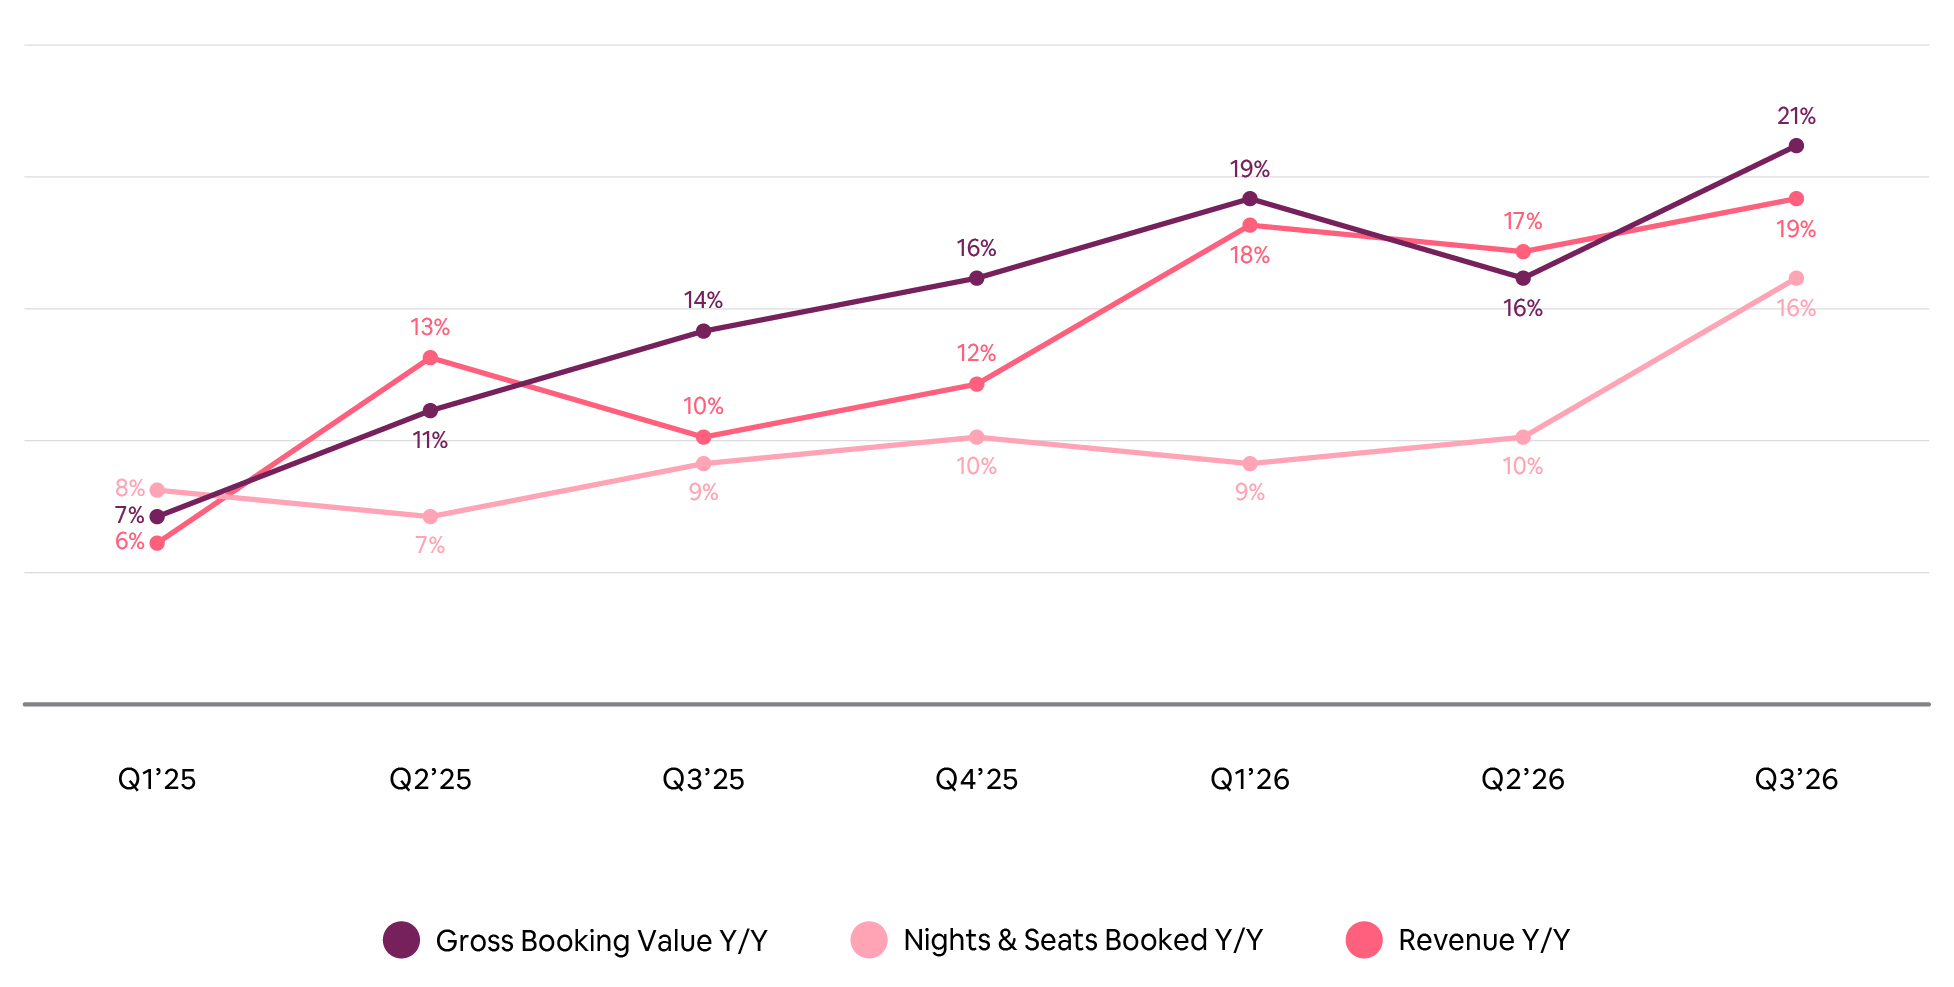
The chart below highlights the clear acceleration in Airbnb's business momentum in Q3 2026, with Gross Booking Value (GBV) increasing 21% year-over-year, revenue rising 19%, and Nights and Seats Booked growing 16%. Particularly notable is the acceleration in booking volume growth from 10% in the previous quarter to 16%. This suggests that improving results are being driven not only by higher prices but, more importantly, by increasing user activity. At the same time, GBV growth outpacing booking volume growth points to a higher average booking value, confirming improvements in both business scale and the value of transactions processed through the platform.
Source: Airbnb
Airbnb Returns to Strong Growth. Are Mature Markets Attracting Customers Again?
The most important takeaway from Airbnb's results is the acceleration in growth despite the company's enormous scale and the maturity of its largest markets. Nights booked increased at double-digit rates across all regions, while the company's five core markets—the US, France, the UK, Canada, and Australia—recorded accelerating booking growth. Particularly significant is the improvement in North America, where nights booked grew at their fastest pace in four years. This demonstrates that Airbnb's expansion is no longer driven solely by geographic expansion, but also by renewed demand growth in countries where the platform is already well established.
Another important development is the growing number of first-time users, particularly among Gen Z, which is showing the fastest growth in activity on the platform. From a long-term perspective, this is significant for Airbnb because acquiring new customers can translate into recurring bookings over many years, without requiring equally high marketing expenditure for every subsequent transaction. Nevertheless, the company remains sensitive to consumer spending, travel costs, and broader economic conditions, particularly in Europe. For investors, the key question will be whether Airbnb can sustain strong booking growth beyond the traditionally busy summer season.
Artificial Intelligence Is Reducing Costs. Will Airbnb Build Its Own AI Agent?
Airbnb is increasingly leveraging artificial intelligence not only to improve the user experience but also to enhance operational efficiency. In Q3, approximately 40% of all customer support issues were resolved without human intervention, compared with around one-third in the previous quarter. Meanwhile, customer support costs per booking declined by more than 17% year-over-year, demonstrating that AI implementation is already delivering measurable financial benefits. During Q3 alone, the company introduced more than 50 new products and features, nearly 70% more than a year earlier.
The next stage of development will involve Airbnb's proprietary AI agent, which is expected to begin rolling out to users in the first half of 2027. Rather than introducing a traditional chatbot, Airbnb intends to develop an interactive system that helps travelers plan trips, compare accommodation options, manage reservations, and access additional services. The company's strategic advantage could come from combining extensive data on user behavior with the ability to complete transactions directly within its platform. Over the longer term, such a solution could improve booking conversion rates and reduce support costs, although its success will depend on recommendation quality and customers' willingness to adopt AI-powered tools.
Hotels, New Services, and a $12 Billion Share Buyback Program
Airbnb is gradually expanding its business model beyond short-term rentals of apartments and houses. The platform now offers thousands of independent and boutique hotels across more than 60 popular travel destinations, although hotels still account for a single-digit share of total nights booked. Interestingly, approximately 35% of customers whose first Airbnb booking is a hotel subsequently return to the platform to book a house or apartment. This suggests that hotel offerings can serve as an additional customer acquisition channel rather than simply competing with Airbnb's core business.
Airbnb is also expanding into car rentals, grocery delivery, laundry services, and additional travel-related amenities. Its partnership with American Express will make more than one million Airbnb listings available through the Amex Travel platform, potentially expanding the company's distribution reach. Meanwhile, the new share repurchase authorization of up to $12 billion signals management's confidence in Airbnb's financial outlook, although execution will take place over time and is not guaranteed. For shareholders, the most important consideration will be whether these new services generate additional revenue and higher earnings per share without significantly increasing operating costs.
Airbnb Stock Chart (D1 Timeframe)
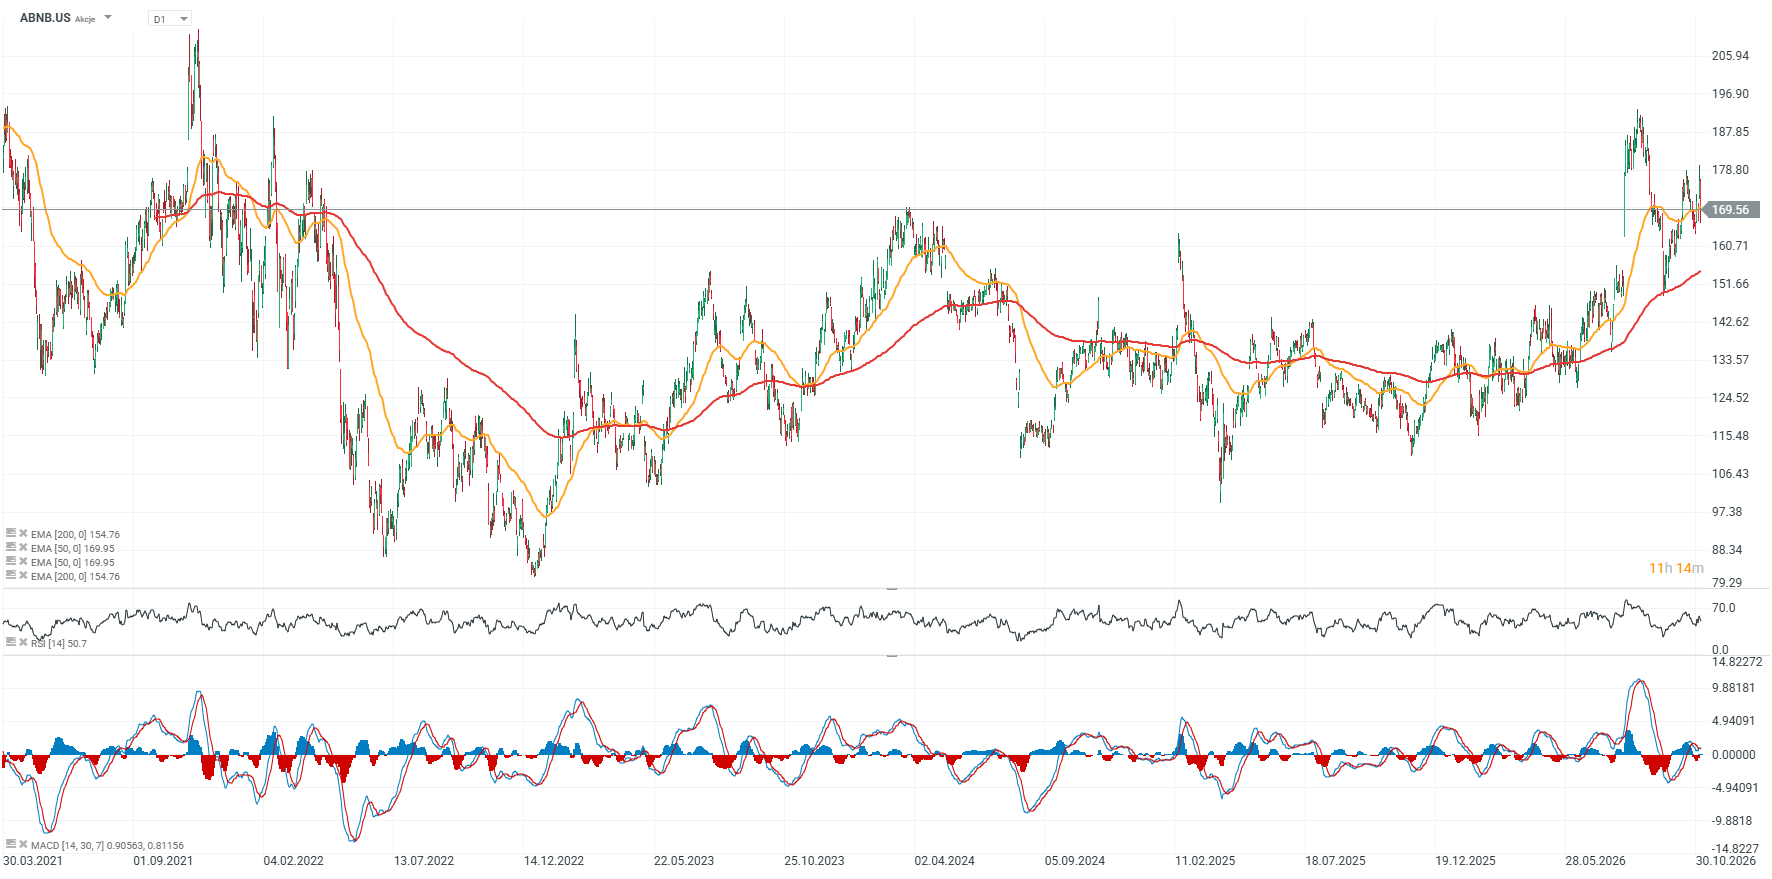
Airbnb shares recently halted their decline around the 200-day exponential moving average (EMA200, red line), while the market's reaction to the earnings report suggests that a rebound toward the recent highs of approximately $185–187 per share is possible. Interestingly, the stock has demonstrated relative resilience despite the extremely weak sentiment on Wall Street in recent sessions. A key support level is located around $190, and a breakout above this level could potentially push the stock toward its 2021 highs near $210 per share.
 Source: xStation5

Quantum Computers are becoming a scarce commodity. IonQ has sold out its entire 2027 capacity


US Open: Wall Street’s post-election rally loses steam as reality sets in

Qualcomm Earnings: Smartphone Setback


Market Wrap: European Gas Rebounds as Rheinmetall Plunges
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.