


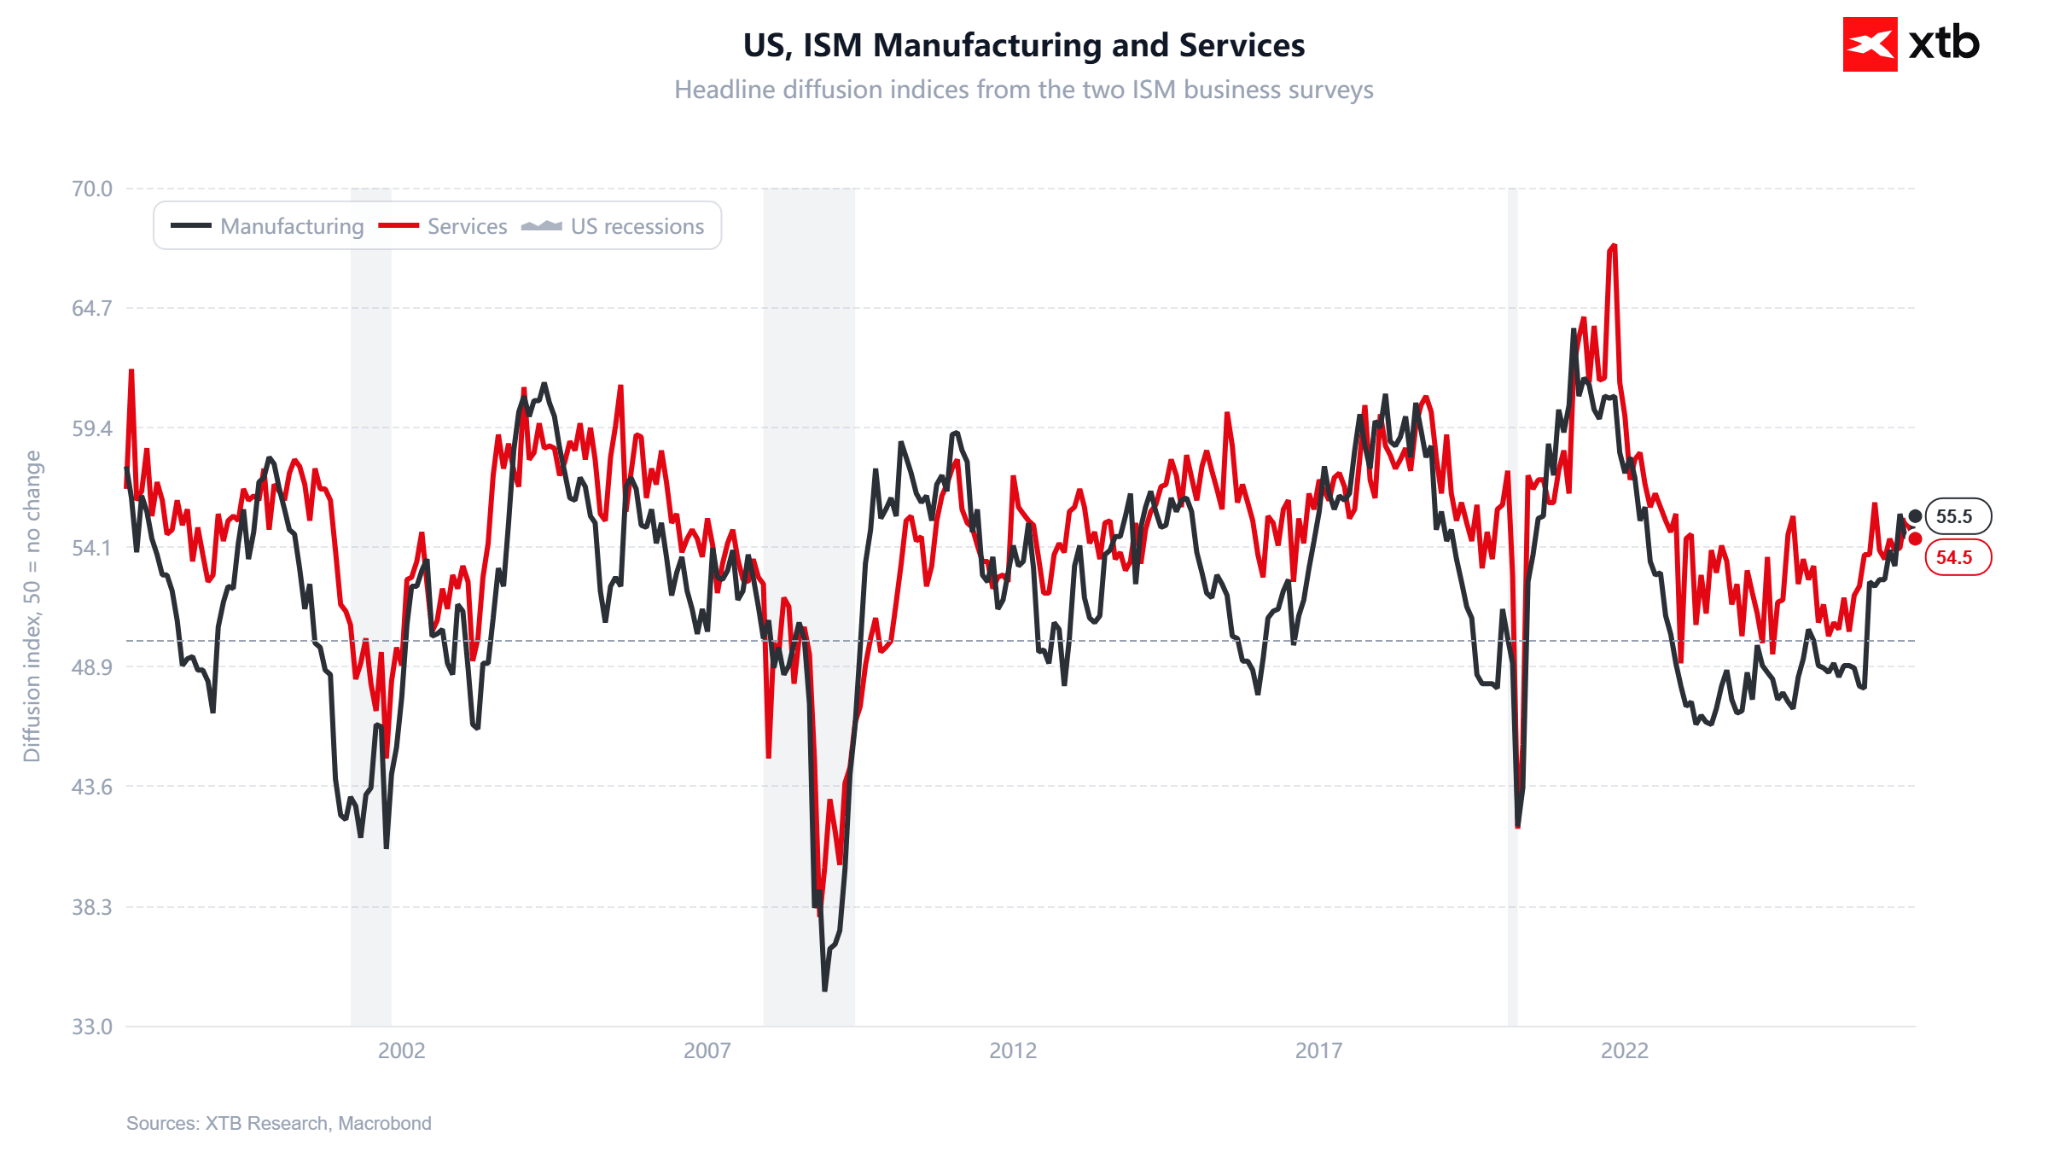
- ISM services index fell to 54.5 in October, recording its slowest expansion in 3 months.
- Prices paid sub-index rose to 73.0, signaling persistent inflationary pressure in the US services sector.
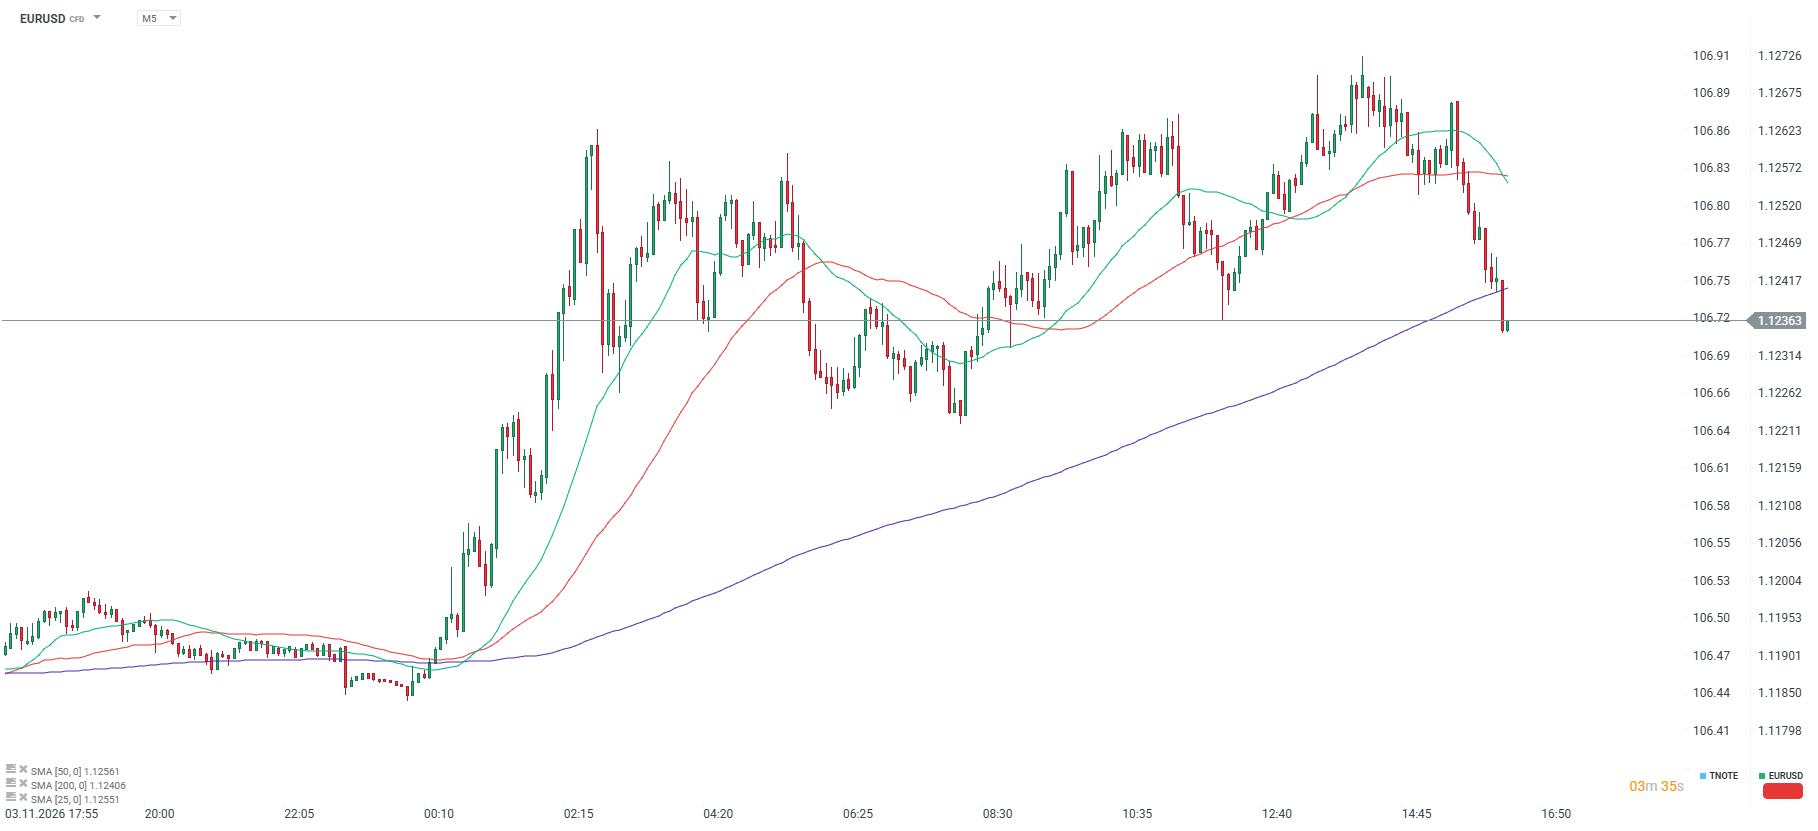
- EURUSD dropped to 1.1236 as strong cost data limited the appetite for dollar sell-offs.

- ISM services index fell to 54.5 in October, recording its slowest expansion in 3 months.
- Prices paid sub-index rose to 73.0, signaling persistent inflationary pressure in the US services sector.
- EURUSD dropped to 1.1236 as strong cost data limited the appetite for dollar sell-offs.
The US services sector recorded its slowest expansion in three months in October, with companies increasingly feeling rising costs and delivery delays. It is worth noting that there is a divergence between the manufacturing and services sectors. However, both sectors still point to expansion.
- ISM services index fell by 0.4 pts to 54.5 (expected 54.8–54.9)
- New orders fell to 55.9 from 59.8 in September, which is the lowest level in four months, though still clearly in growth territory
- Prices paid sub-index came in at 73.0. This is the second highest reading since mid-2022, despite a drop from 74.0
- Supplier delivery times lengthened the most since April
- Services employment surprised to the upside, at 51.4 vs 50.1 in the previous month, the highest since February, which along with a strong ADP bodes well ahead of Friday's NFP report
- 15 out of 18 industries reported growth (vs 13 in September), while construction and healthcare registered contraction
ISM head Steve Miller points out that tariffs and higher fuel costs remain the most frequently cited problems in supply chains, and many companies signal that they have not yet fully passed cost increases on to customers, predicting further price pressure unless the situation in the oil market and trade normalizes. Additionally, this is an important signal for the Federal Reserve, which despite prospects for a calm energy situation, may still plan regular rate hikes.
Despite the slowdown in the headline index, the data does not look like a warning sign for the economy: demand remains solid, order backlogs are the highest since 2022, and the services labor market visibly accelerated. This fits into the "higher inflation with still resilient growth" narrative that the Fed has been emphasizing for weeks.
The reaction in the FX market is visible, though moderate. EURUSD continues the pullback initiated at the open of the European session, dropping from morning highs near 1.1268 to the current 1.1236. The pair is giving back part of its post-election gains, and a higher-than-expected ISM prices paid reading—suggesting that US inflationary pressure is not weakening as fast as hoped—limits the appetite for further dollar sell-offs ahead of Friday's labor market report.


BREAKING: US Labor Market Stronger Than Expected. ADP Report Surprises Ahead of Government Data


Market Wrap: European Stocks Rise Following US Elections

Spain Is Back on Its Feet 🚀 Trump's Nemesis Makes a Comeback After the Midterm Elections 📈


BREAKING: Democrats take both chambers of Congress🗽
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.