

- European natural gas prices reached 95.41 EUR/MWh, hitting the highest level since 2022.
- European gas storage levels stand at 75% capacity, marking the lowest seasonal point since 2009.
- Norwegian supply outages and geopolitical tensions in the Middle East are restricting fuel flows to Europe.

- European natural gas prices reached 95.41 EUR/MWh, hitting the highest level since 2022.
- European gas storage levels stand at 75% capacity, marking the lowest seasonal point since 2009.
- Norwegian supply outages and geopolitical tensions in the Middle East are restricting fuel flows to Europe.
European natural gas (NATGAS.EU, a contract based on Dutch TTF) is trading today at 95.41 EUR/MWh, and in early trading the price reached as high as 97.5 EUR/MWh, the highest level since 2022. This is a continuation of one of the most dynamic price rallies in commodity markets this year: +8.78% weekly, +35.51% month-on-month, +231.28% year-to-date, and +205.21% year-on-year. By comparison, US Henry Hub (NATGAS) is behaving completely opposite, losing 7.09% monthly over the same period and showing levels around 3 USD/MMBtu after the latest rollover, while the November contract fell to 2.5 USD, theoretically the lowest since 2024. The divergence between both sides of the Atlantic has reached sizes rarely seen in the history of both markets.
Bullish fundamentals: lowest seasonal inventories since 2009
At the core of the current move is the storage situation. European gas inventories as of October 24 stand at around 75% capacity (some readings indicate 74.6%), which is the lowest seasonal level since GIE record-keeping began in 2009, compared to a five-year seasonal norm of around 90%. Germany, the continent's largest market, has inventories at just around 61%, although in volume terms the level rose slightly in the last week (152.07 TWh vs 151.63 TWh previously). France records 108.00 TWh vs 107.82 TWh earlier.
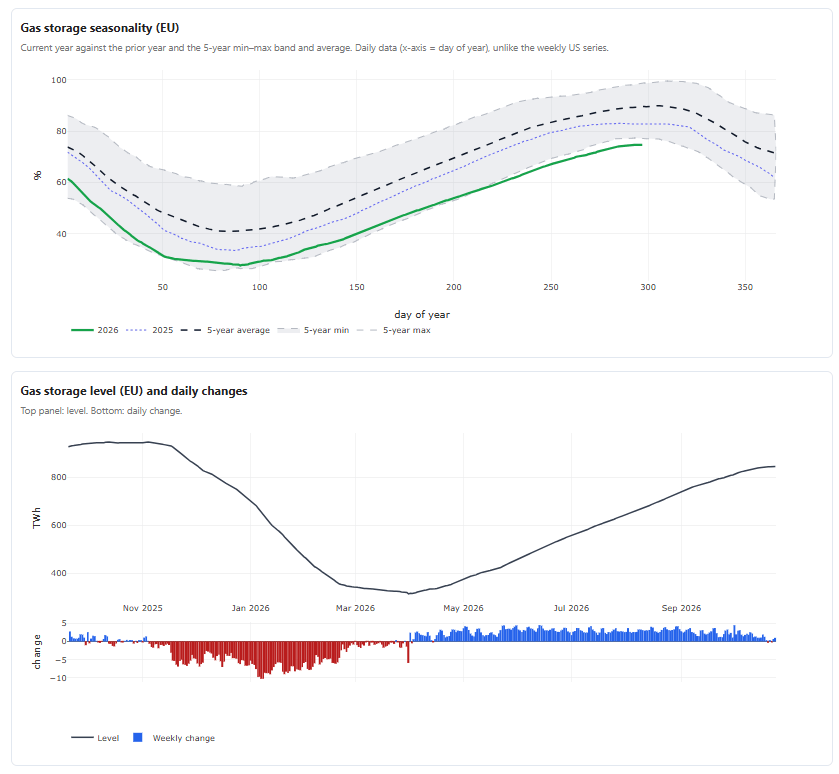 It is worth noting that in recent days there were situations where inventories did not grow, showing that the start of the heating season could lead to stronger price moves. Source: GIE, XTB
Added to this is a series of outages on the Norwegian supply side, which right now, at a crucial moment of the season, is limiting flows to the continent. Gassco reports restrictions at the Oseberg field (7.7 mcm/d from October 26), Troll (6.1 mcm/d from October 25), and KárstØ (7.6 mcm/d from October 25), and earlier at Nyhamna (up to 19.8 mcm/d), Åsgard, and Ormen Lange. On top of that, there is a technical issue at the UK's St. Fergus terminal (Serica Energy), where flow is expected to be restricted through Friday.
On top of all this comes geopolitics. LNG shipments from the Middle East to Europe remain down by approx. 80% year-on-year due to shipping disruptions in the Strait of Hormuz, and the market fears that the United States might decide to strike Iran around the mid-term elections date in early November. Trump is reported to have said that a "time of decision" regarding Iran is approaching.
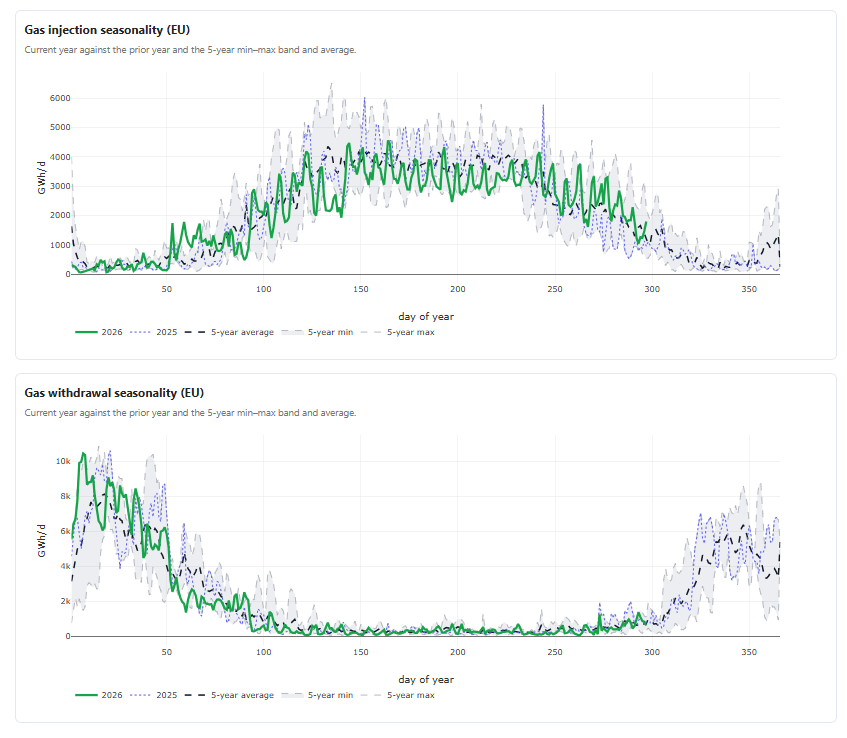 Gas injection into storage is slowing in line with seasonality, but key will be the behavior over the next 2-3 weeks. Source: GIE, XTB
The Asian LNG benchmark (JKM) is trading near four-year highs above 30 USD/MMBtu (December contract +2.6% to 31.42 USD, January +4% to 31.54 USD), meaning Europe is physically losing the competition for LNG tanker cargoes to Asian buyers.
European LNG imports in October fell below the five-year seasonal norm for the first time since August, despite seasonal expectations for growth.
Technical analysis
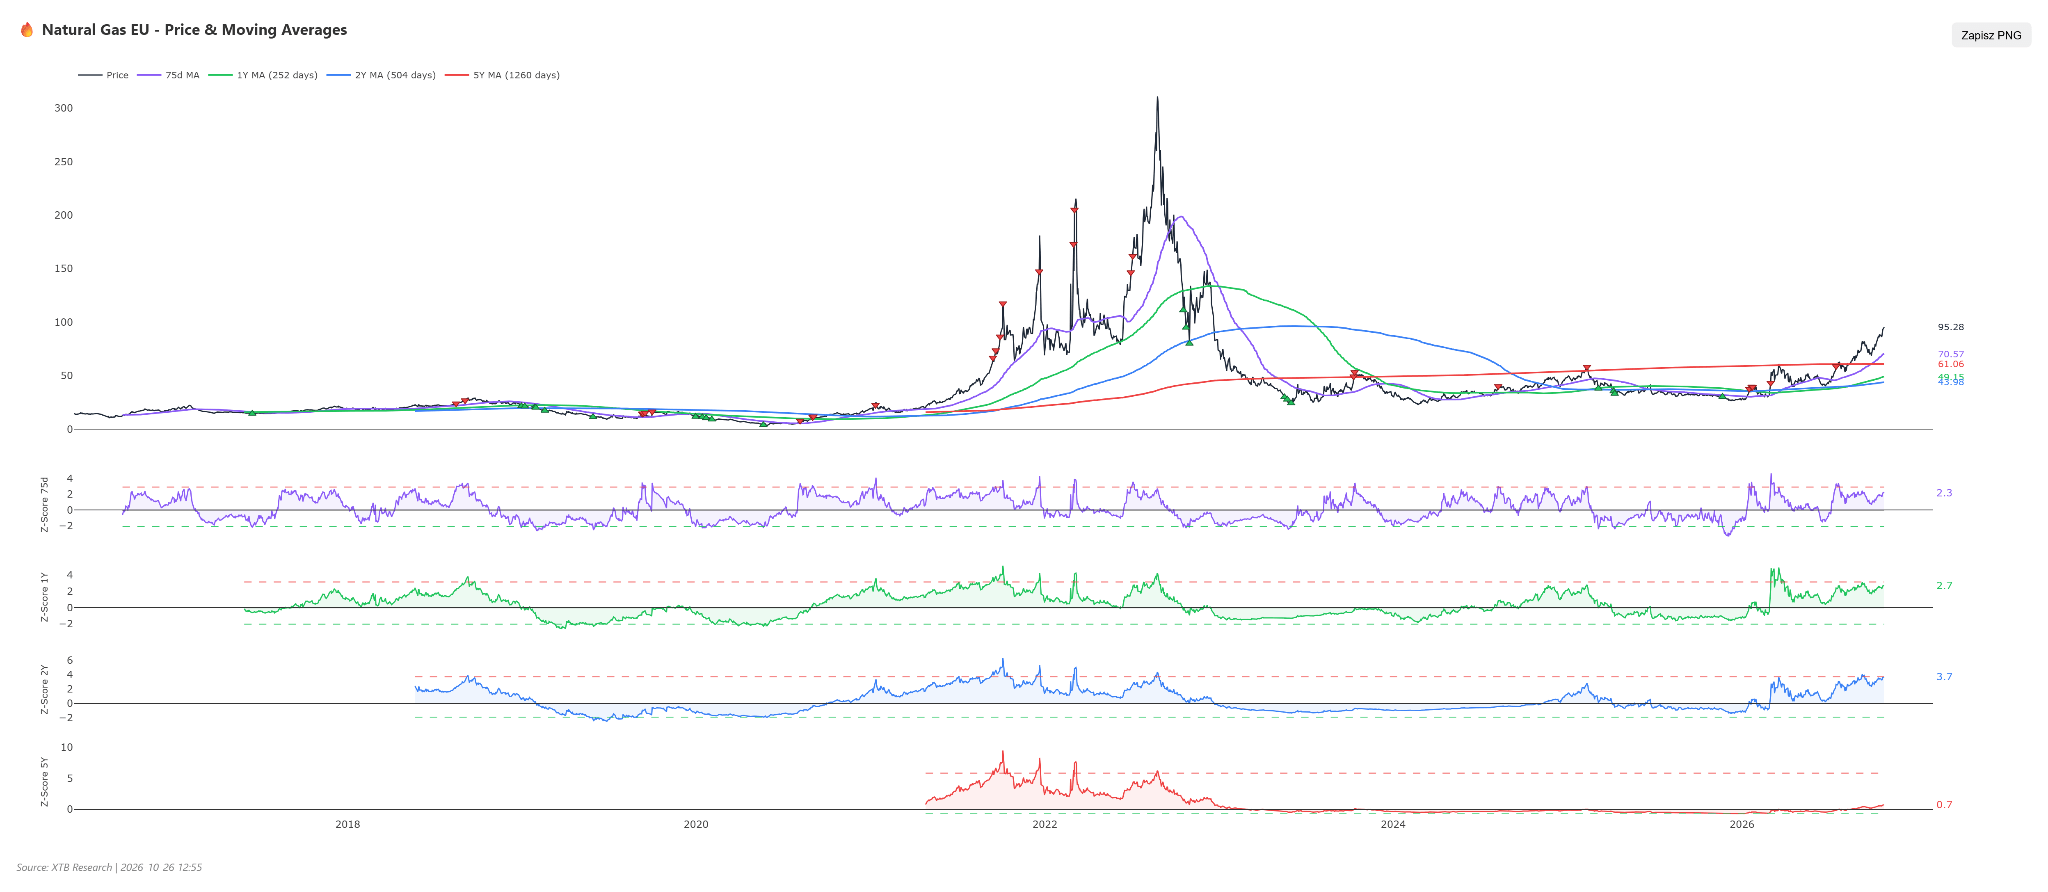
The NATGAS.EU daily chart shows a textbook example of a strong uptrend built on two consecutive impulse waves, separated by a correction around June.
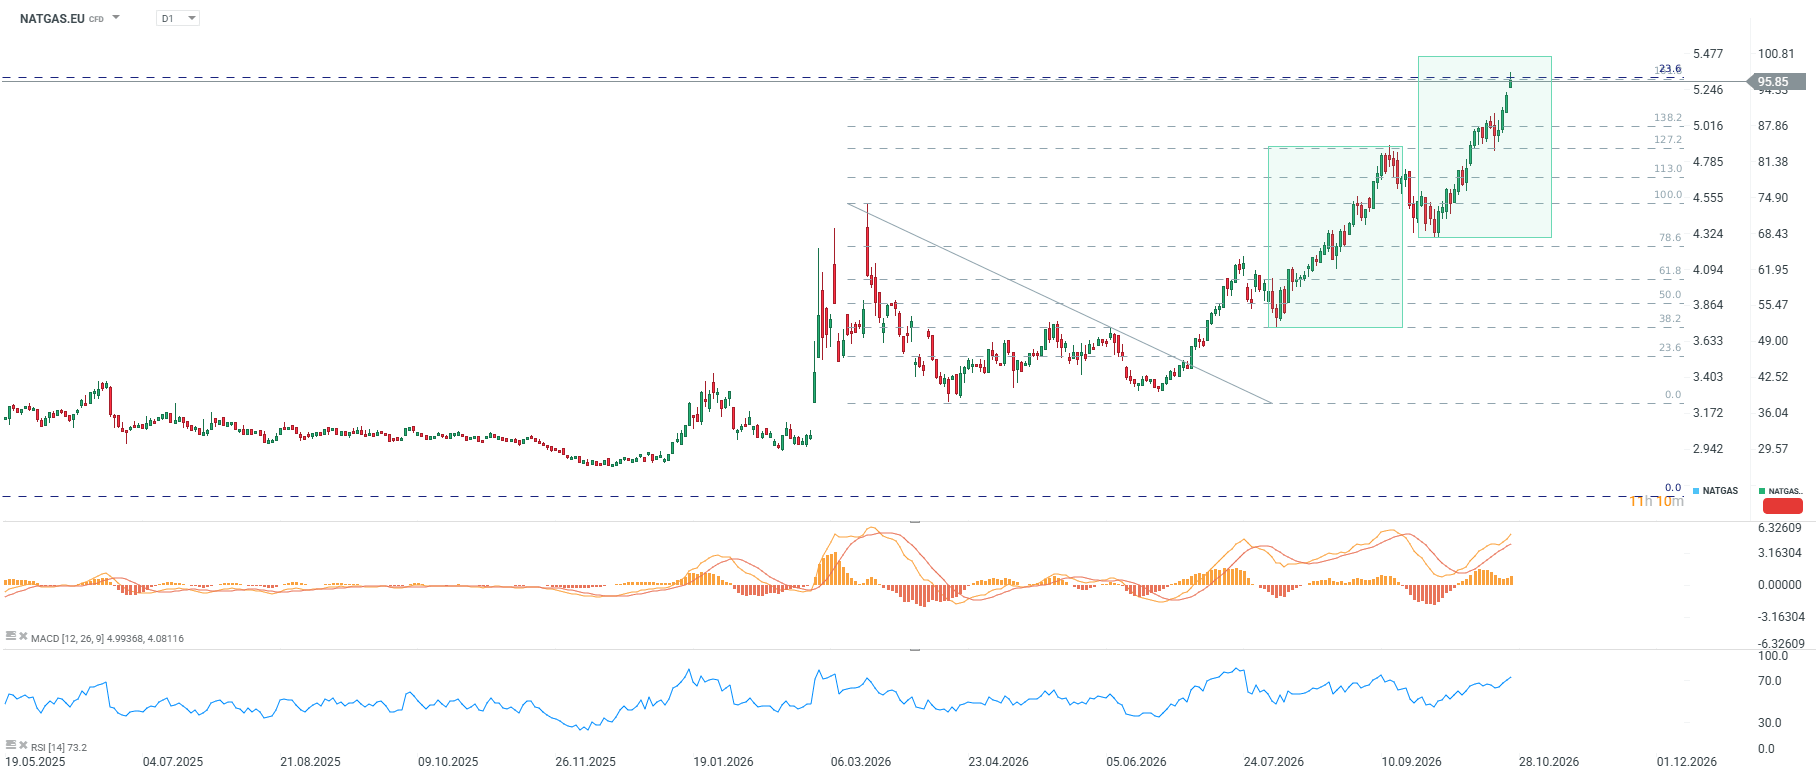
In the current upward impulse since June, we are witnessing the third wave. Comparing it to the second larger one, the range of movement points to a potential for 100 EUR/MWh. At the same time, however, we observe a reaction to the 161.8 retracement of the downward impulse after March and the 23.6 retracement, representing the entire large downward impulse at the end of 2022.
Momentum indicators confirm the strength of the move, but also signal clear overbought conditions. RSI(14) stands at 73.3, deep in overbought territory (above 70), which historically preceded at least short-term corrections or consolidations. MACD remains in a bullish structure with a rising histogram and signal lines above zero, although it is worth noting that during the first upward wave in August, the MACD histogram reached significantly higher values than currently at a similar price level. This can be interpreted as an early signal of weakening momentum (divergence), although so far unconfirmed by price action. The price sits 24.59% above the 50-day SMA, an extreme deviation that in itself increases the probability of a technical correction bringing the price closer to the moving average, regardless of fundamentals.
Z-score confirms the scale of overvaluation in historical terms: the 1-year Z-score is +2.73, 2-year reaches as high as +3.71, and even the 5-year, which was negative (-0.34) six months ago, climbed to +0.75. This indicates that the current price is a statistically rare event against the backdrop of the past two years of trading.
Scenarios
Bullish scenario. Further escalation around the Strait of Hormuz, actual US military actions against Iran, and a continued Middle Eastern LNG deficit, coupled with colder weather arriving in Europe, would push prices through the 100 EUR barrier towards 112–118 EUR/MWh. The market still needs to replenish record-low inventories, so any demand impulse will translate into aggressive bidding for cargoes against Asian buyers.
Bearish scenario. De-escalation of tensions in the Middle East, resumption of safe passage through Hormuz, and mild early winter temperatures would remove the threat of physical shortages and trigger profit-taking after the strong rally. Under this setup, price could fall to support at 88.00 EUR, with potential to deepen declines to 75.50 EUR/MWh, especially given the extreme overbought levels according to RSI and Z-score.
Summary
The European gas market finds itself in a rare situation where extremely tight fundamentals (lowest seasonal inventories since 2009, a series of Norwegian outages, competition for LNG cargoes with Asia) coincide with an equally extreme technical picture (RSI above 73, 1-year Z-score over +2.7, price 24.6% above SMA50). This combination justifies a further march toward 100 EUR in the event of bad news from the Middle East or weather fronts, while simultaneously making the market exceptionally vulnerable to a sharp correction at the first sign of de-escalation.


Economic Calendar - German Ifo index, Middle East escalation, and Wall Street giants' earnings



Elections in Brazil: Lula returns to power, markets react with panic. Brazilian ETF loses nearly 15% in Tokyo. What about USDBRL, soybeans, sugar, BRAComp, and ETFs?


🟢Morning Wrap: Lack of escalation lowers oil prices. Unexpected Lula victory hurts Brazilian stock market

Daily Summary: Oil at five-month highs, indices under pressure (23.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.