

- Nikkei 225 futures rose 1.83 percent driven by strong semiconductor stocks following Micron earnings.
- European and US indices declined as rising oil prices and interest rate pressures weighed on markets.
- The Bank of Japan faces less pressure for urgent rate hikes due to the latest Tankan business sentiment survey.
- Nikkei 225 trades near 68 269 points, sitting between key Fibonacci retracement levels of 67 168 and 68 731.
- Buyers maintain control while the index holds above 67 168, though a close above 68 731 is needed to confirm strength.
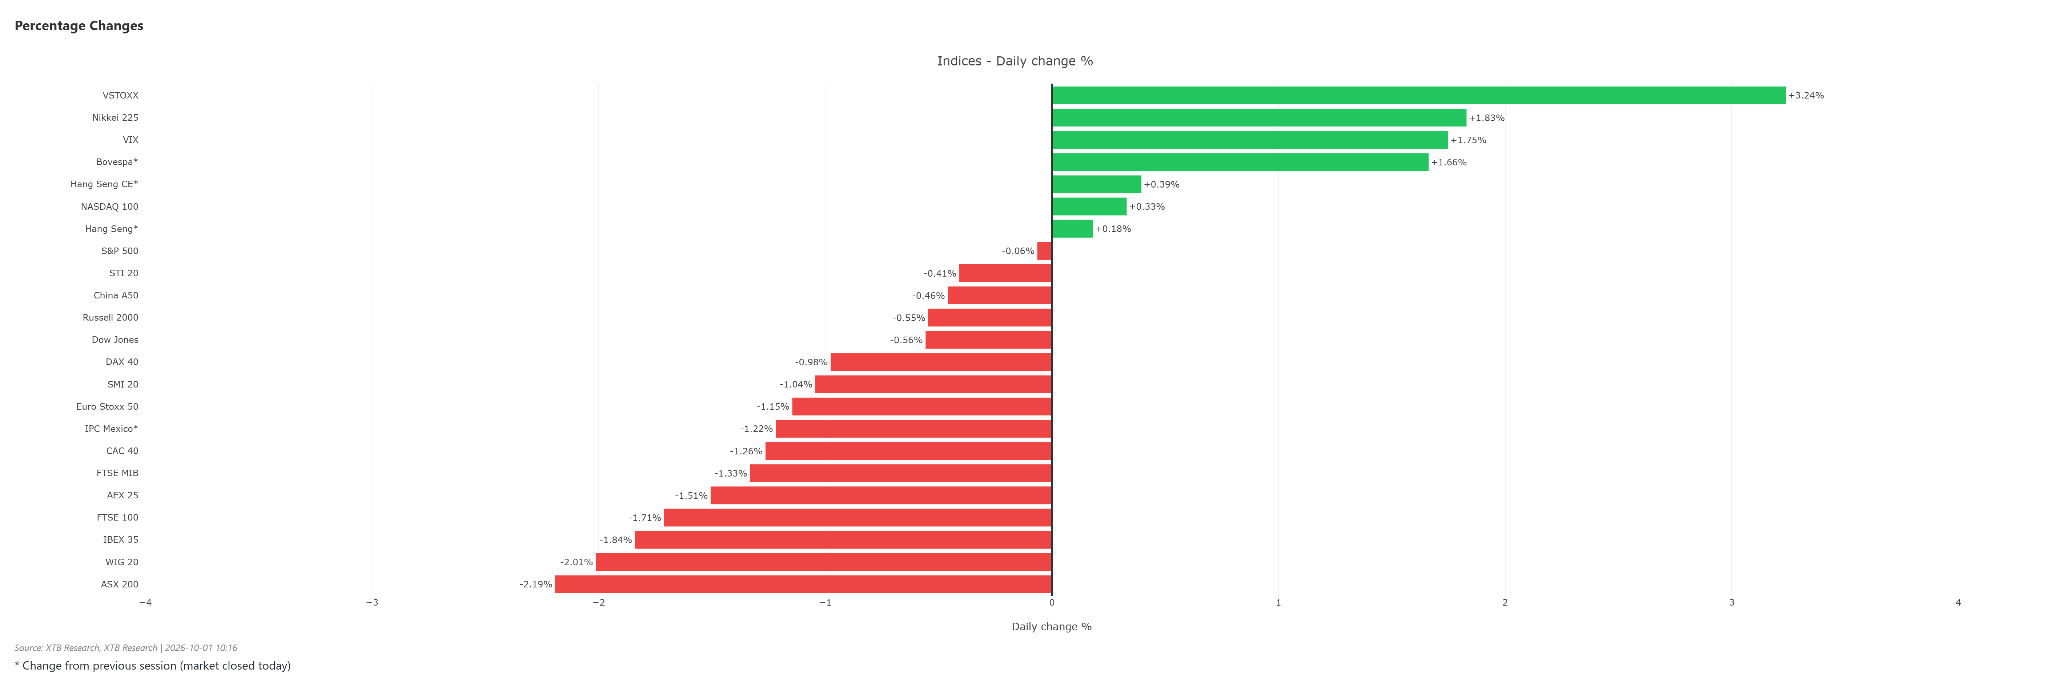
Today's session looks very intriguing, although even before the European open it seemed that all indices would play the same tune. Nikkei 225 futures are up 1.83% and are the second strongest instrument among all indices, behind only the European volatility index VSTOXX. At the same time, almost all of Europe is in the red: WIG20 is down 2.01%, IBEX 1.84%, FTSE 100 1.71%, AEX 1.51%, DAX 0.98%. US index futures are giving back earlier gains, with the S&P 500 down slightly and the Dow Jones down 0.56%.
Why is Japan rising while the rest is falling?
This is composed of three separate stories that happened to coincide in time.
Semiconductors are pulling the Nikkei up. This is the main driver of today's movement. The Japanese index has a structurally different composition than European benchmarks. Under price-weighting, a few high-value tech stocks account for a disproportionately large share of the index's move. Advantest, Tokyo Electron, SoftBank Group, and Screen Holdings can single-handedly generate most of the Nikkei's daily movement. When the semiconductor cycle receives a positive impulse (yesterday's Micron earnings), the Japanese index responds much more strongly than the DAX or CAC 40, which practically lack this tech sector.
Tankan took the pressure off the Bank of Japan. The quarterly business sentiment survey release weakens the arguments for an urgent rate hike. For the Japanese stock market, this is a directly favorable setup: a weaker yen improves exporters' results, while postponing tightening removes pressure from valuations. This is the exact opposite of what Europe is experiencing, where the ECB returned to rate hikes in September. For October, an 18% probability of a hike is priced in, while December is fully priced in.
Europe and the US are paying the bill for oil. Article headlines in today's press explicitly attribute the declines to a renewed rebound in oil prices. December Brent is rising close to 100 USD, and WTI is already above 92 USD. Japan imports virtually all of its energy, so theoretically it should suffer the most, but today the sectoral boost from tech prevailed.
Valuations: things are getting uncomfortable
The long-term Z-score chart requires attention, as it puts today's move into a broader perspective.
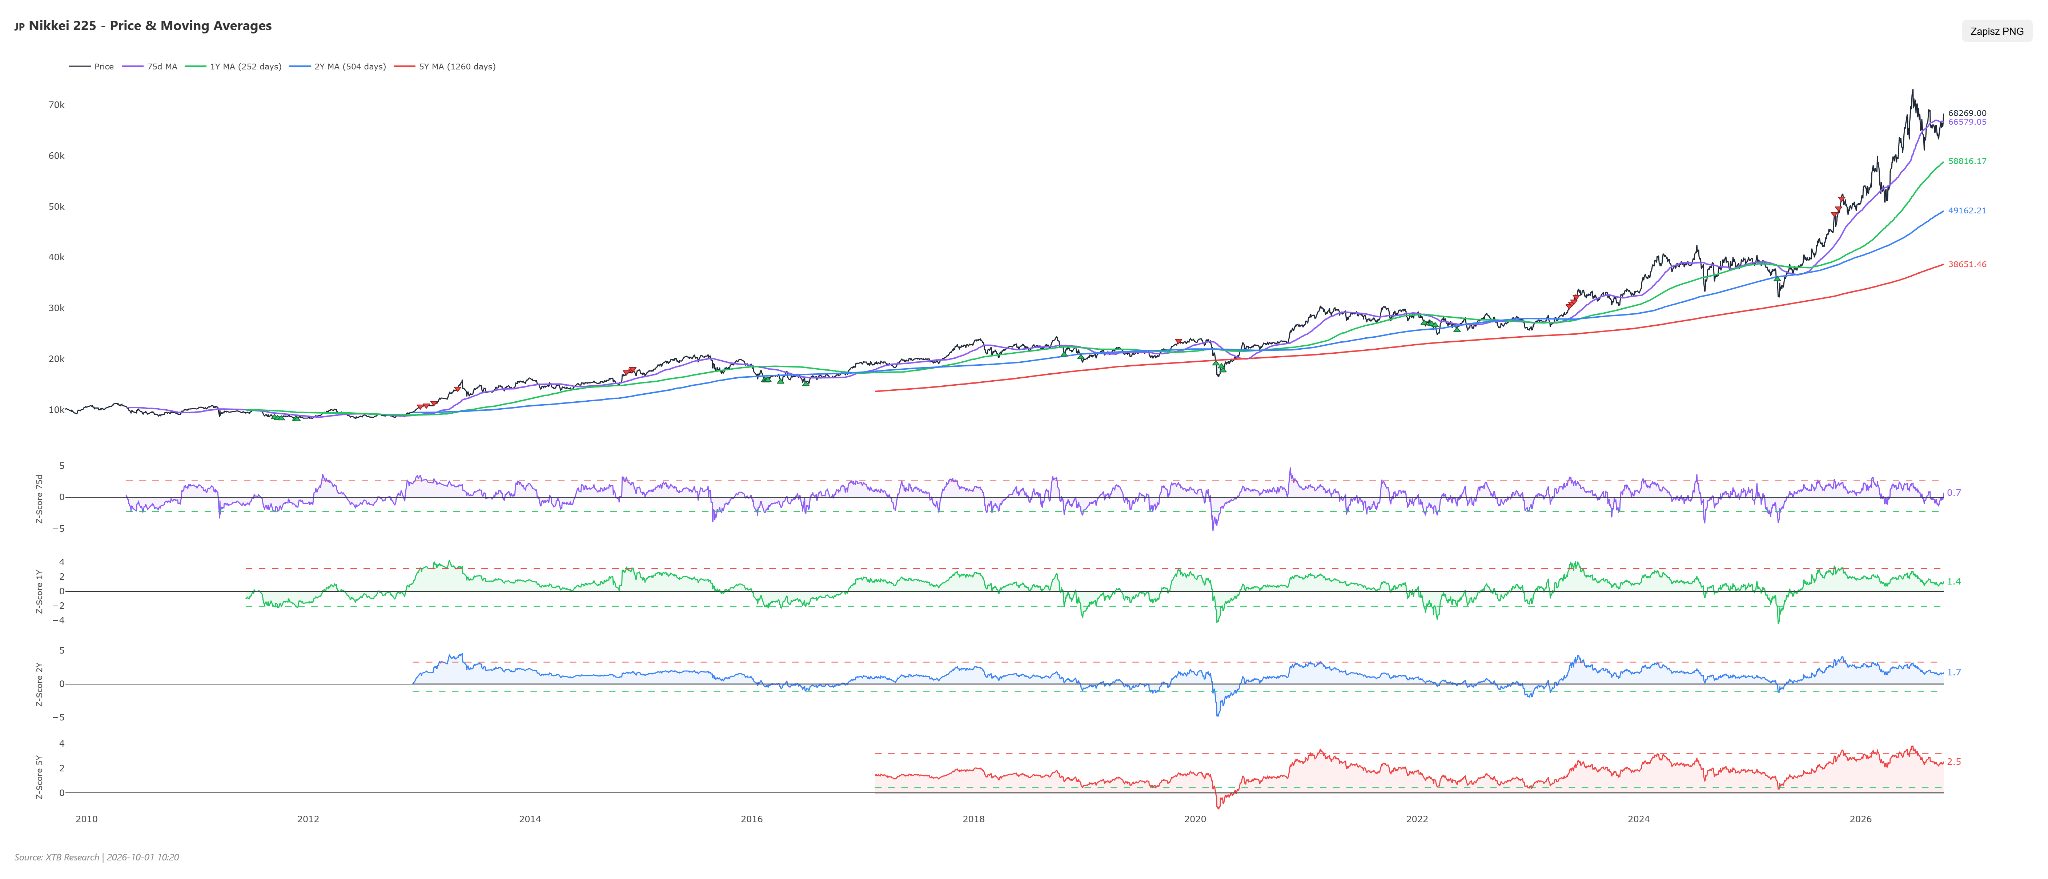
With the Nikkei at 68,269 points, it stands 2.5 standard deviations above its five-year moving average of 38,651. The two-year Z-score is 1.7, the one-year is 1.4, and the 75-day is 0.7. The gap between the price and the 5-year moving average is currently around 76%, a degree of stretch unseen in the market's recent history. This is not a sell signal. The Z-score speaks to position relative to history, not direction. However, it implies that any prospective correction has much more room to fall than a short-term chart would suggest, and current levels offer no safety buffer. Significantly, the 75-day Z-score at 0.7 shows that the index is not overbought in the short term. The issue is structural, not tactical.
Technical analysis of JP225 on the daily timeframe
The JP225 daily chart shows a clear structure following the July peak. The market reached a high of 73,791 in early July before dropping to 60,545 in the first half of August. The current Fibonacci retracement is plotted over this swing, defining all key levels.
After the August trough, a bounce ensued toward the 70,956 area, the 78.6% retracement, where supply took over. A September leg down brought the index back to around 62,500, from which the market has been building another rebound, reaching 68,284 today.
The current location is key. Price sits right between the 50% retracement at 67,168 and the 61.8% at 68,731. These 500 points above the current price present the first real resistance hurdle.
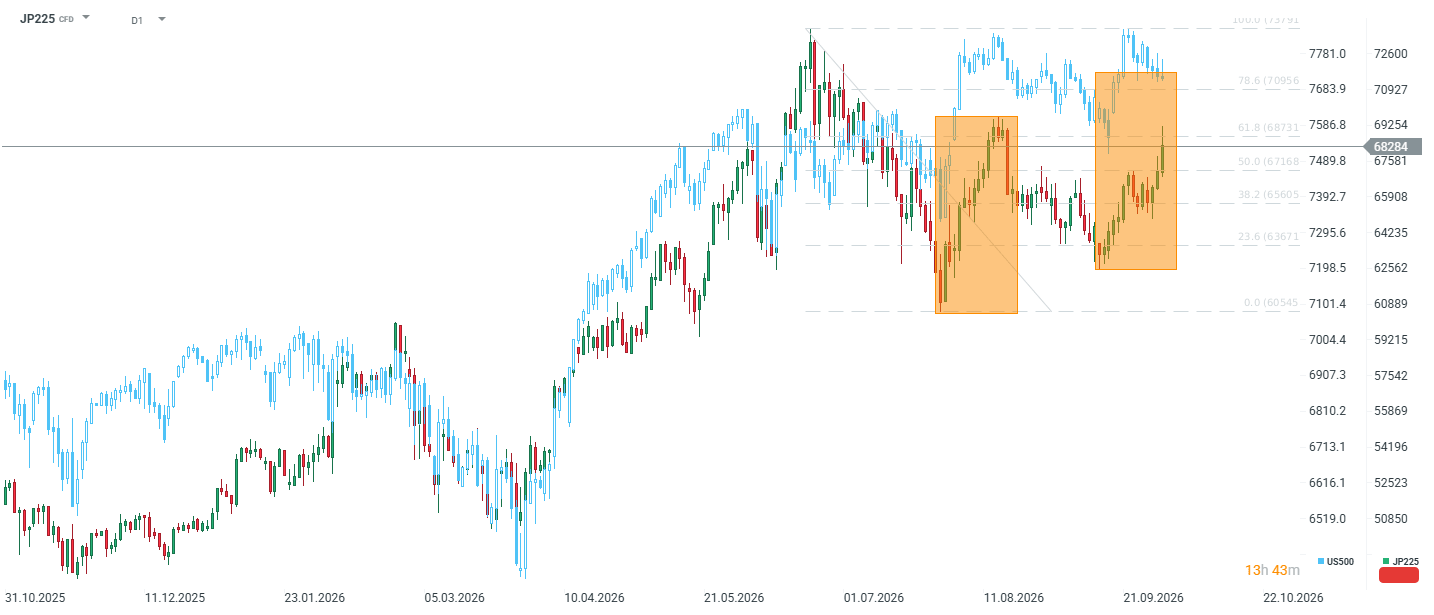
Base scenario. As long as price holds above 67,168, buyers retain the initiative, and the higher-low structure since August remains intact. The market has made two attempts at the 68,500 to 69,000 zone, both rejected, making this third test of the area a decisive moment.
What to watch? Today's rally is narrow sectorally and accompanied by rising volatility in other markets. Such a combination often precedes a reversal. Confirmation of strength would be a close above 68,731 alongside a calming of the VIX and VSTOXX. If volatility indices keep rising while the Nikkei fails to sustain current levels, we have a classic bull trap breakout and a move back toward 65,600.


Morning Wrap: Tech Rally in Asia Following Micron Results and Weakening Yen Despite Hawkish BoJ


Record after record: Micron smashes Q4 results, server overload crashes website, stock surges post-market



📊Daily Summary: PCE inflation slowdown brings relief to Wall Street, but oil continues gains despite return of supply


Morning Wrap: AI drives Nikkei 225 gains, oil prices decline (30.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.