


Market returns to tech after worst week since June
On Monday, the broad Nasdaq Composite index gained 1.11%, closing the session at 26,430 pts, while the Semiconductor Index (SOX) snapped an eight-session losing streak (-15.7% total, the longest since October 2008) with a 1.6% rise. Investors returned to buying discounted chip and AI stocks after the S&P 500 and Nasdaq posted their largest weekly declines since late June last week. The Nasdaq lost 4.5% then, and the tech sector dropped over 6%, the most since April 2025. As Wall Street commentators pointed out: “nothing bad happened over the weekend,” and the market was oversold enough that a rebound was only a matter of time. On the other hand, some compared the current period to Black Monday in the late 1980s, though the session ultimately ended with strong gains.
Under the hood of the rebound, however, selectivity is apparent. Intel gained 2.4% following an upgrade by J.P. Morgan, AMD +1.8%, Micron +3%. On the flip side, CoreWeave—the epicenter of last week's panic over $50 billion in debt—ended the session in the red (-0.4%) despite an upgrade to "buy" by Goldman Sachs, with its CDS levels indicating serious issues. Fund managers warn that the narrative around the "resilience of the AI trade to rate hikes" is changing: the market is starting to assess more selectively whether companies will actually generate a return justifying the debt being taken on. Certainly, the current earnings season could set a new narrative for the market.
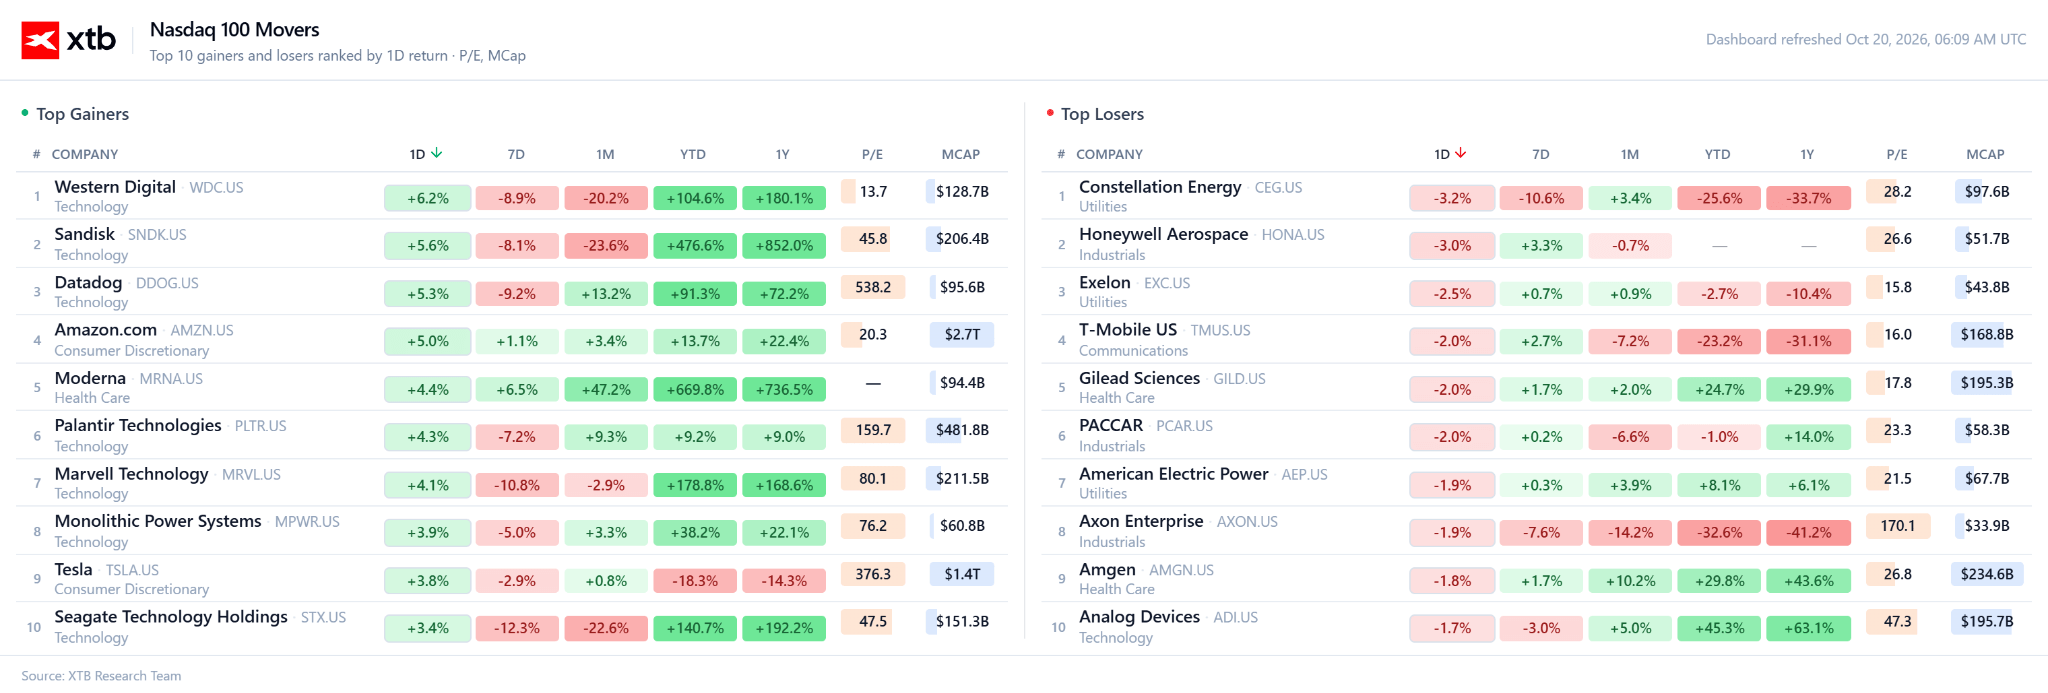
An additional catalyst for optimism comes from reports that Nscale is negotiating the sale of computing power to Anthropic for around $45 billion, while Citigroup estimates that the AI sector will account for nearly 70% of global corporate earnings growth next year.
This week, the key test for sentiment will be earnings from Meta and Tesla (Wednesday) and SpaceX (Tuesday), with Tesla and SpaceX reporting amid growing speculation about a potential merger between Musk's two companies. In the background, geopolitical tensions persist (attacks on energy infrastructure in Russia and the Middle East) along with elevated oil prices, keeping bond yields high.
US100 Technical Analysis
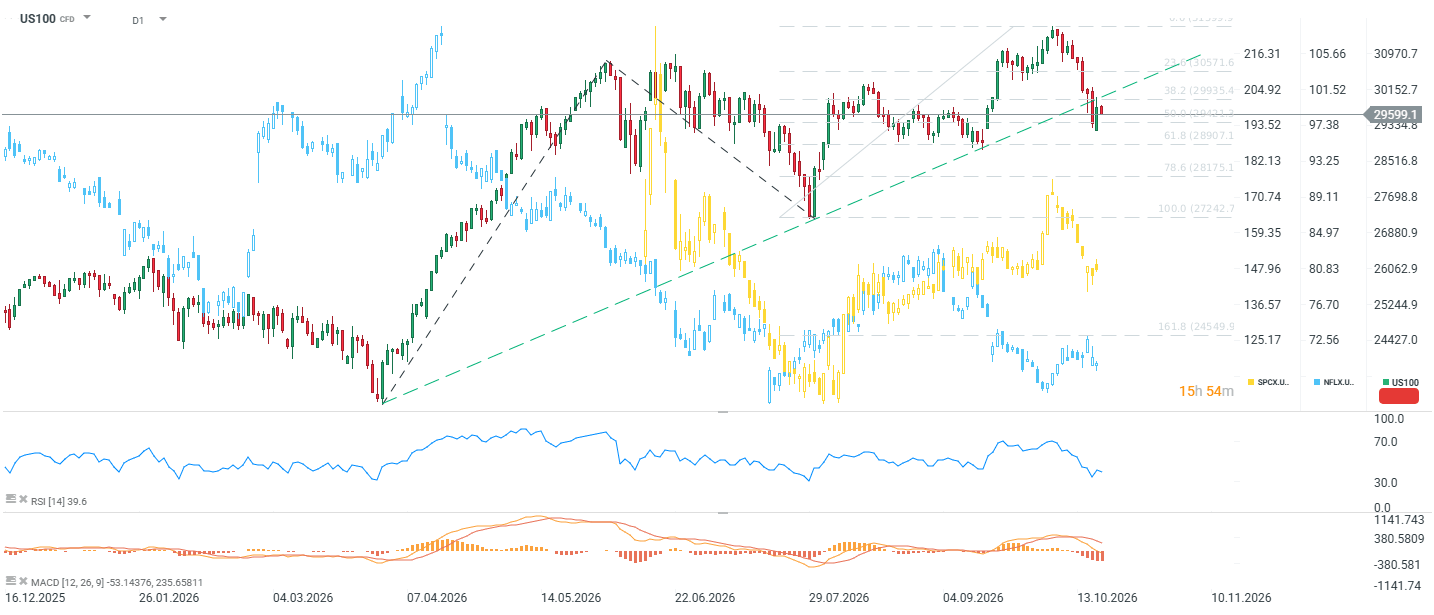
The Nasdaq 100 contract is currently trading below 25,600 pts, well below its October record high (~31,600 pts) and below the upward trendline originating from the April low (~22,400 pts), which price broke in recent sessions. This marks an important shift in market structure compared to previous weeks, when this line acted as dynamic support. On the other hand, this could still be treated as a "false" breakout.
Price currently resides in the 38.2–50.0% Fibonacci retracement zone (29,935–30,421 pts), suggesting that the correction of the recent upward move is already advanced. The RSI(14) at 39.6 is approaching the oversold zone but has not reached it yet, meaning the market potentially still has room for a continued decline before technical indications for a bounce appear. The MACD is distinctly negative (MACD line -53.1, signal line -235.7, with the histogram remaining below zero since mid-September), confirming the dominance of supply in recent weeks, though it is worth noting that the negative histogram has recently been shrinking slightly. This is a signal of weakening downside momentum, but not yet a trend reversal.
Key levels:
- Resistance: 29,935 (38.2% retracement), 30,421–30,572 (50.0–23.6%), 31,600 (ATH / 0.0)
- Support: 28,907 (61.8%), 28,175 (78.6%), 27,243 (100.0% - August low)
The breach of the upward trendline and the drop in RSI below 40 serve as warning signals for the continuation of the 2026 bull run. Unless the price firmly defends above 29,935–30,000, the risk of a further slide toward the 28,900–28,200 zone remains elevated. Only a return above 30,570 (the vicinity of the former resistance line, now potentially being tested from below) would negate the weak signal and open the door for a renewed attempt at the highs.
Conclusion
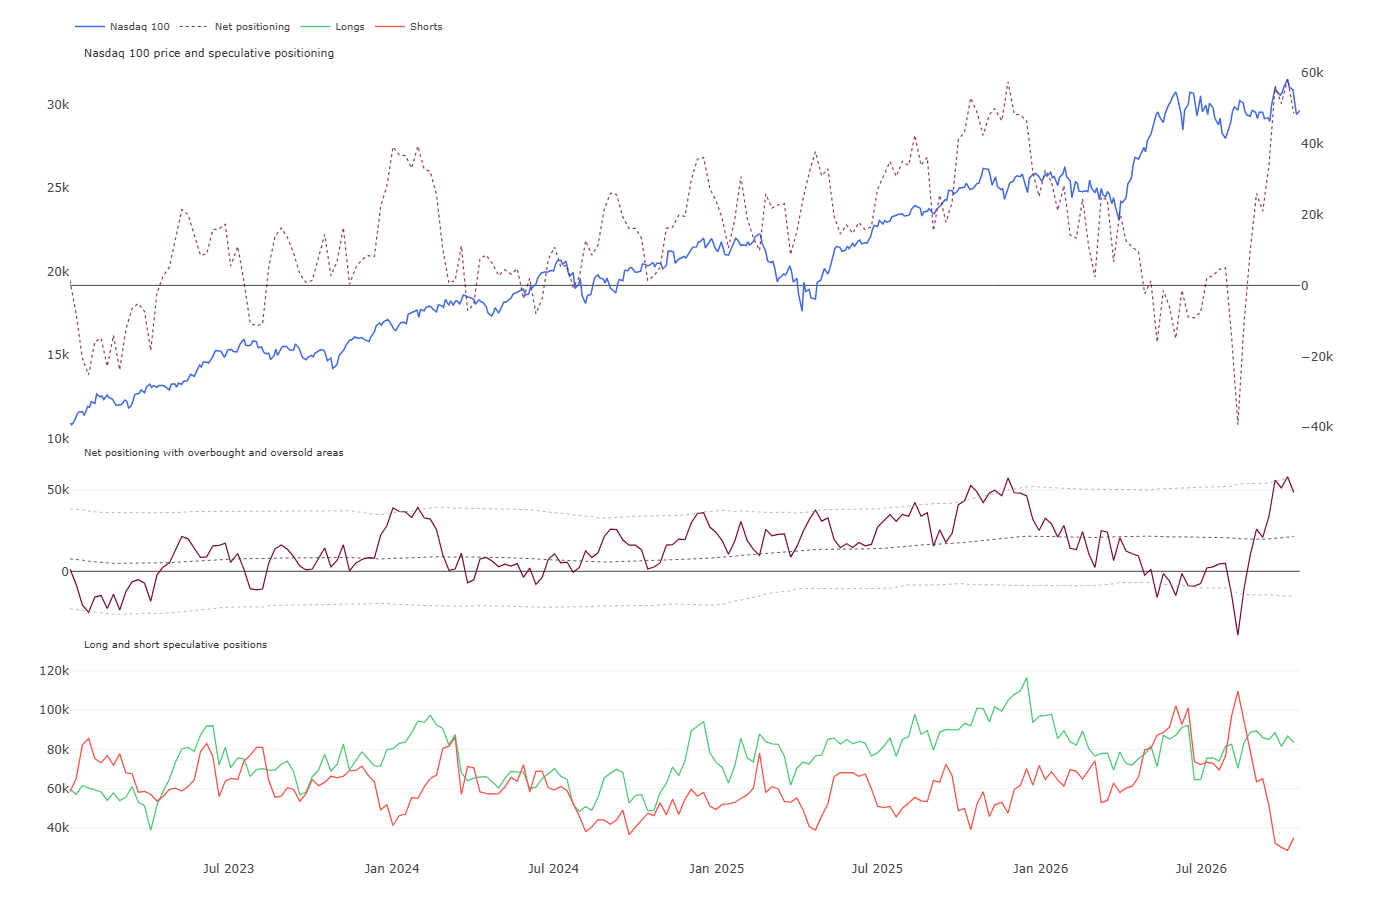
Monday's Wall Street rebound is a tangible sign that the market was technically oversold and investors still believe in the fundamentals of the AI investment cycle. At the same time, the US100 chart itself does not yet confirm this optimism. The breakdown of the long-term upward trendline and a weak RSI suggest treating Monday's move as a technical rebound within a broader correction rather than a return to the main uptrend. Earnings results from Meta, Tesla, and SpaceX this week, as well as further developments surrounding CoreWeave's debt and other "neoclouds," will be key to whether the US100 holds the 29,900–30,000 zone or deepens its decline toward 28,900–28,200. It is worth noting an interesting aspect regarding positioning, however. Recently, a massive number of speculative short positions on Nasdaq 100 futures were closed. This short covering moved the net positioning from an extreme oversold zone to an extreme overbought area. Nevertheless, the correlation between net positioning and the index itself remains relatively low.



Macro Calendar - UK Labor Market, ZEW Sentiment, and Wall Street Giants' Reports



Chart of the Day: What’s next for tech stocks after the deepest sell-off since April 2025? (19.10.2026)


Economic Calendar: Big tech earnings week and test for the AI rally (19.10.2026)


Morning Wrap: Nasdaq rebounds ahead of Mag7 earnings, bonds regain favour, oil falls from peak (19.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.