


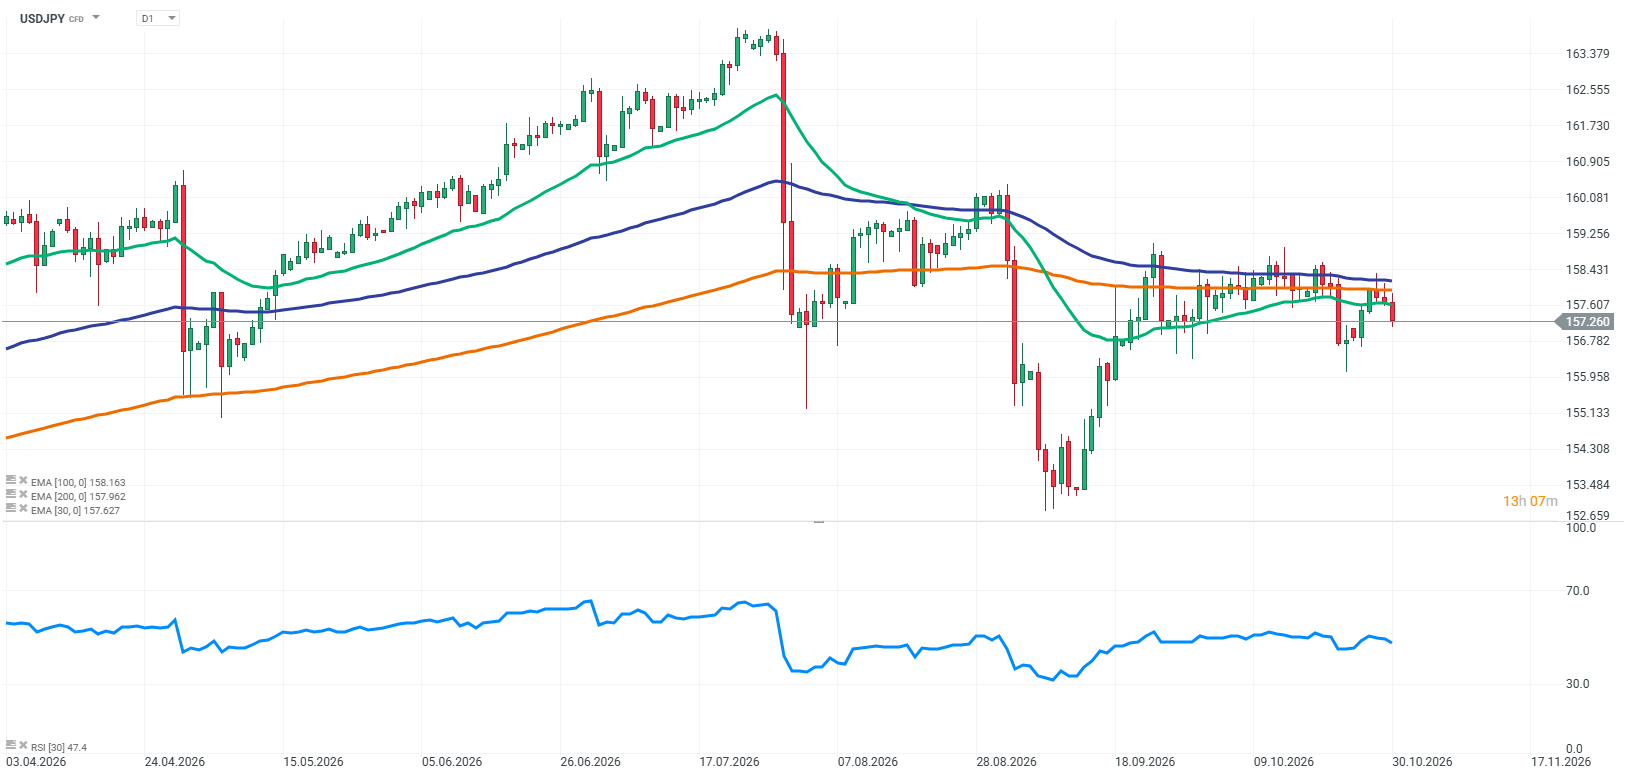
USDJPY came under pressure following the conclusion of the Federal Reserve's and Bank of Japan's October meetings. Both central banks decided to leave interest rates unchanged, but differences in their communication point to diverging approaches to the next stages of monetary policy. The message from Tokyo was particularly significant, as policymakers sent a clearer signal that further monetary tightening remains on the table.
Source: XTB Research
Key factors currently shaping USDJPY
Bank of Japan holds rates but delivers a clearly hawkish message
The Bank of Japan left its key interest rate unchanged at 1.25%, in line with market expectations. However, the accompanying statement proved important for the future outlook of monetary policy. The BoJ indicated that underlying inflation in Japan is now broadly consistent with its 2% target. This marks a significant shift in the assessment of economic conditions, as achieving sustainable price stability was one of the main prerequisites for further monetary policy normalisation.
The central bank also raised its underlying inflation forecast for fiscal year 2027 from 2.4% to 2.6%, while indicating that the balance of risks to prices remains tilted to the upside. This suggests that policymakers see the possibility of inflationary pressures persisting at a higher level than previously anticipated.
The voting outcome is also worth noting. The decision to keep rates unchanged passed by an 8-1 majority. Board member Hajime Takata voted in favour of an immediate rate hike to 1.50%, arguing that with inflation close to target, the central bank should move more quickly towards a more neutral interest rate level. This disagreement highlights increasingly visible calls within the BoJ for a faster pace of monetary policy normalisation.
December BoJ rate hike becoming increasingly realistic
The October meeting strengthened expectations of another BoJ move before the end of the year. If the central bank decides to raise rates in December, the policy rate would increase from 1.25% to 1.50%. However, this outcome is far from guaranteed. Policymakers will need to assess the state of household consumption, labour market conditions and the impact of previous monetary tightening on economic activity.
Energy prices and their impact on inflation will also remain important factors. The BoJ will need to determine whether price pressures are sufficiently persistent to justify further rate increases. From the foreign exchange market's perspective, the key question is whether upcoming comments from central bank officials will reinforce December as a realistic date for the next rate adjustment.
Fed also holds rates, but inflation leaves little room for a dovish shift
The Federal Reserve decided to leave interest rates unchanged within the 3.75–4.00% range. However, the voting outcome revealed a lack of full agreement among FOMC members regarding the future direction of monetary policy. Two Fed officials, Lisa Cook and Beth Hammack, voted in favour of a 25-basis-point rate hike. This signalled that some policymakers consider the current level of interest rates insufficient to effectively contain inflationary pressures.
Meanwhile, Chair Kevin Warsh emphasised the need for more information before making further decisions. The Fed wants to assess how previous monetary tightening is affecting the economy, particularly amid elevated energy costs and rising investment expenditure related to the development of artificial intelligence.
PCE inflation accelerates again. The dollar retains an important source of support
Another factor complicating the USDJPY outlook is the latest US inflation data. September's PCE index, the Federal Reserve's preferred measure of inflation, increased by 0.5% month-on-month, compared with 0.3% in August. Annual inflation accelerated from 3.4% to 3.6%. Price pressures therefore remain persistent and significantly above the central bank's 2% target.
Under these conditions, the Fed has limited room to ease monetary policy. Persistently elevated inflation could even justify further monetary tightening. Following the October meeting, markets priced in a probability of a December rate hike exceeding 80%. This is an important argument against the assumption that the monetary policy gap between the two central banks will narrow rapidly.
USDJPY after central bank decisions: further correction or a return to gains?
The current situation points to an increasing risk of further yen appreciation, but does not confirm a lasting reversal in the broader USDJPY trend. In a bearish scenario, the key factor will be confirmation from the BoJ that it is prepared to raise interest rates in December. A further decline in US Treasury yields would provide additional support for the Japanese currency.
The opposite scenario assumes that the dollar remains strong due to persistent inflation in the United States, while expectations of another BoJ rate hike are pushed further into the future. In that case, the yen's current appreciation could prove to be merely a correction within a broader upward trend in the currency pair.
The risk of intervention by Japanese authorities should also remain on investors' radar. The 160 level remains an important reference point, although it is not an automatic threshold that would necessarily trigger action from Tokyo. The possibility of intervention may continue to limit the pair's upside potential, particularly in the event of a rapid depreciation of the yen.
Conclusion
The October meetings of the Fed and BoJ resulted in unchanged interest rates, but it was the Japanese central bank that delivered the more hawkish message. The upward revision of its underlying inflation forecast for the next fiscal year to 2.6%, together with the vote in favour of an immediate rate hike to 1.50%, increases the significance of the December meeting.
At the same time, persistent inflation in the United States and hawkish voices within the FOMC mean that the dollar continues to enjoy meaningful fundamental support. In the short term, the BoJ's more hawkish communication may favour the yen and limit USDJPY's upside potential. However, the pair's ultimate direction will depend on whether expectations surrounding the December decisions of both central banks are confirmed by incoming economic data.
Key factors for USDJPY:
-
Hawkish BoJ: Rates remain at 1.25%, but the central bank signals that further monetary tightening remains possible.
-
Japanese inflation: Underlying inflation is broadly consistent with the 2% target, while the FY2027 forecast has been raised to 2.6%.
-
December rate hike: The possibility of the BoJ raising rates from 1.25% to 1.50% remains an important supportive factor for the yen.
-
Fed and PCE inflation: Inflation accelerating to 3.6% year-on-year limits the scope for monetary policy easing.
-
US Treasury yields: A decline in yields could put additional pressure on the dollar against the yen.
-
Intervention risk: Japanese authorities may still respond to excessive weakness in the domestic currency, particularly near the 160 level.
-
Base scenario: The BoJ's more hawkish stance increases the risk of a further downward correction in USDJPY, although persistent US inflation limits the yen's appreciation potential.


Binance Hit by the Largest Hack in Cryptocurrency Market History. Losses Could Reach USD 6.3 Billion


Economic Calendar: Preliminary European GDP and German Inflation in Market Focus


Morning Wrap: Wall Street's Tech Slowdown: Massive AI Investments Spark Growing Concerns


Daily Summary: Bloody Thursday on Wall Street: Nasdaq Leads the Sell-Off
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.