

- US natural gas trades around 3.12 USD per MMBtu following a recent futures contract rollover and pipeline outage.
- TC Energy resolved the Mountaineer Xpress pipeline failure, erasing the supply risk premium from prices.
- Record September production and high inventory forecasts weigh on prices while strong LNG exports and extreme short positioning create upside risk.
Gas gives back premium from pipeline outage, but weather and LNG prevent deeper discount
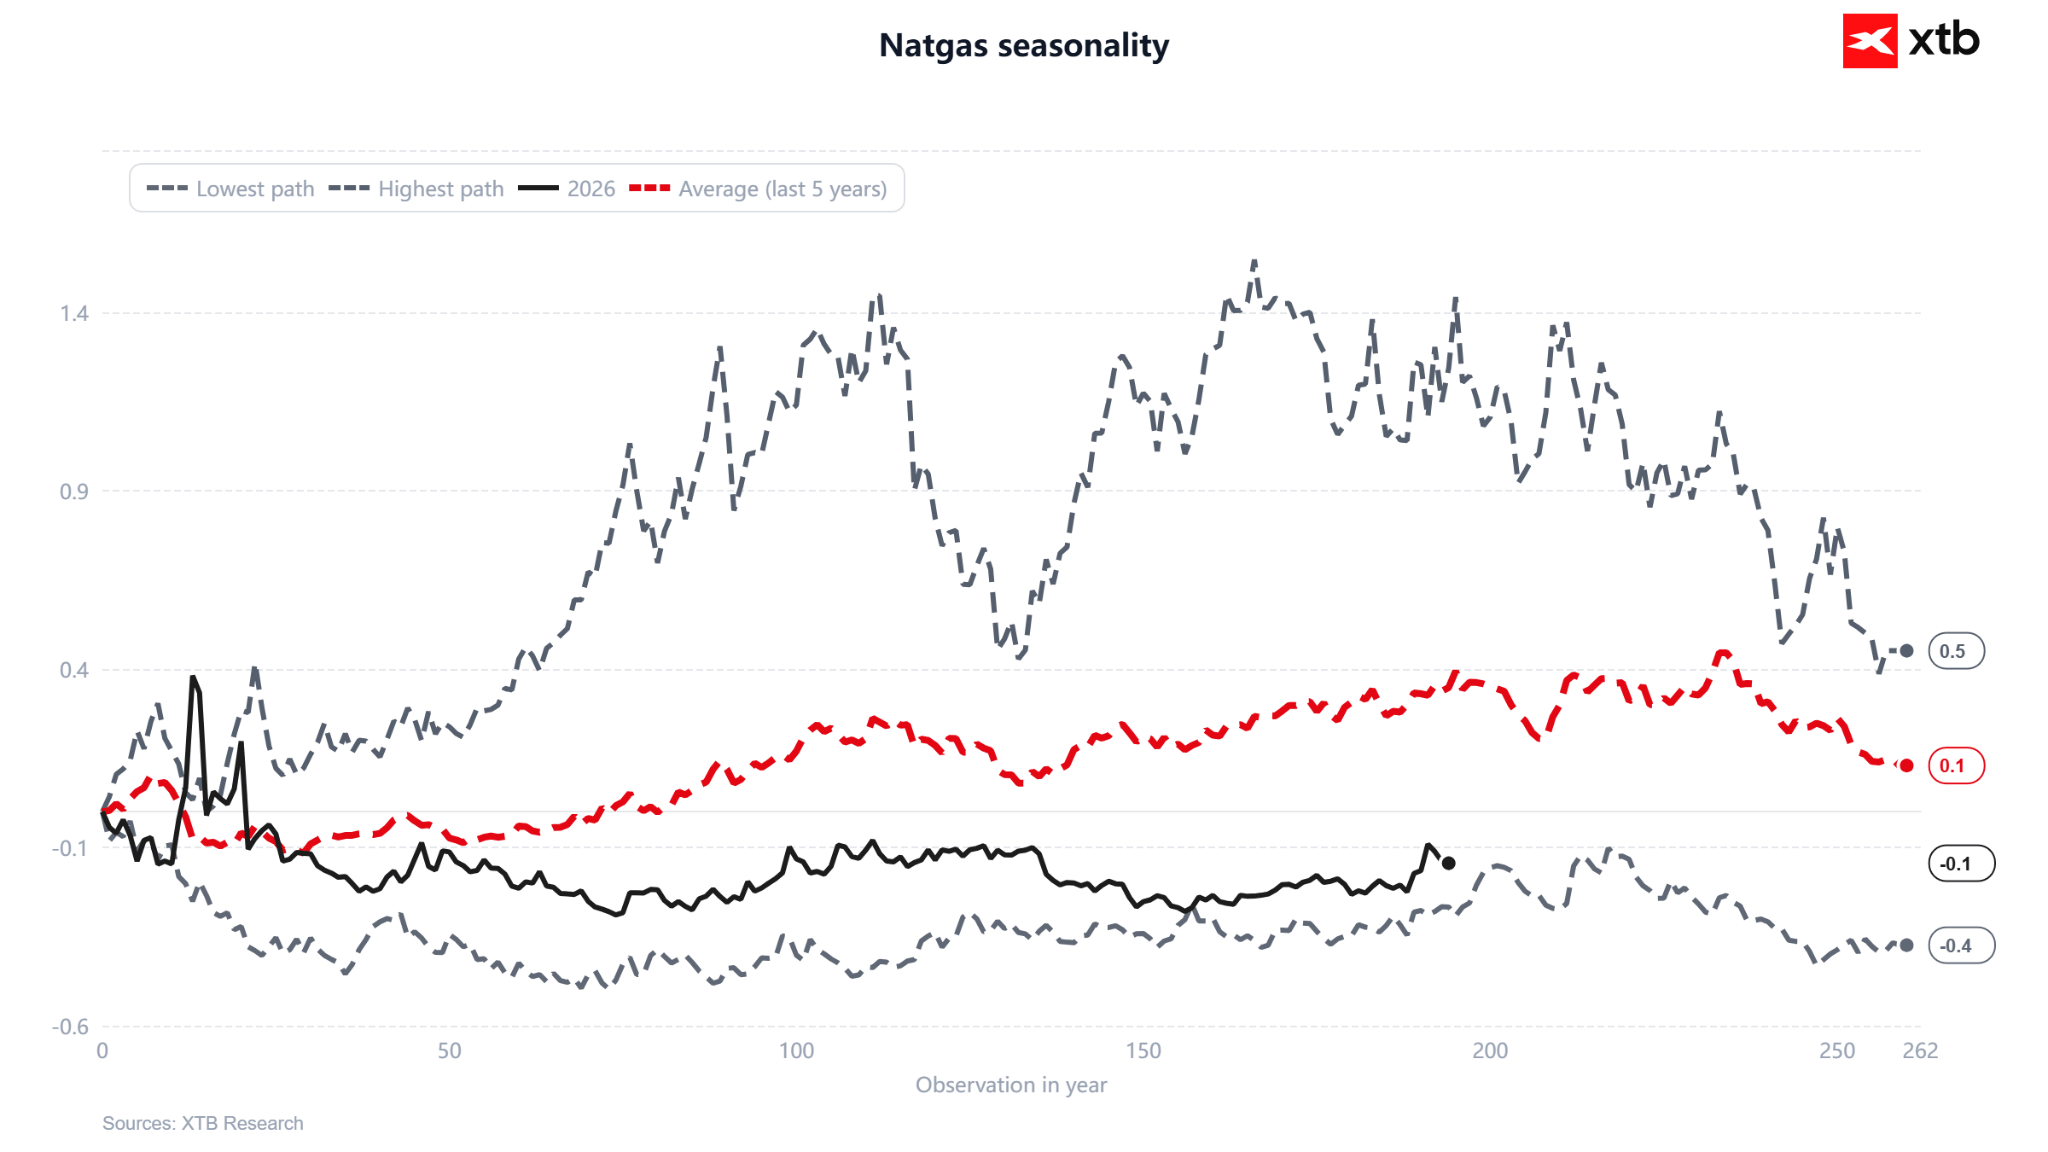
US natural gas is trading around $3.12 per MMBtu and is falling for the second session in a row. However, it is worth noting one important detail key to further analysis. On September 23, futures contracts rolled over, and this accounts for a significant portion of the spike in quotes visible on the chart. The monthly change of 6.7 percent and the improvement in annual dynamics to minus 6.3 percent largely result from the transition to the new contract series, rather than a real demand impulse. The forward curve on NATGAS during the heating season remains in very high contango to the January contract. Historically, Natgas usually reached its price peak around November.
The second factor boosting prices was an outage in the United States itself, not the situation in the Middle East. TC Energy declared force majeure last Thursday on the Mountaineer Xpress pipeline in West Virginia, removing 1.4 to 1.8 billion cubic feet per day from transmission. The market surged to its highest level in two and a half months. On Sunday, however, the company announced that the failure had been resolved, which instantly erased the supply risk premium from prices.
Weather works both ways
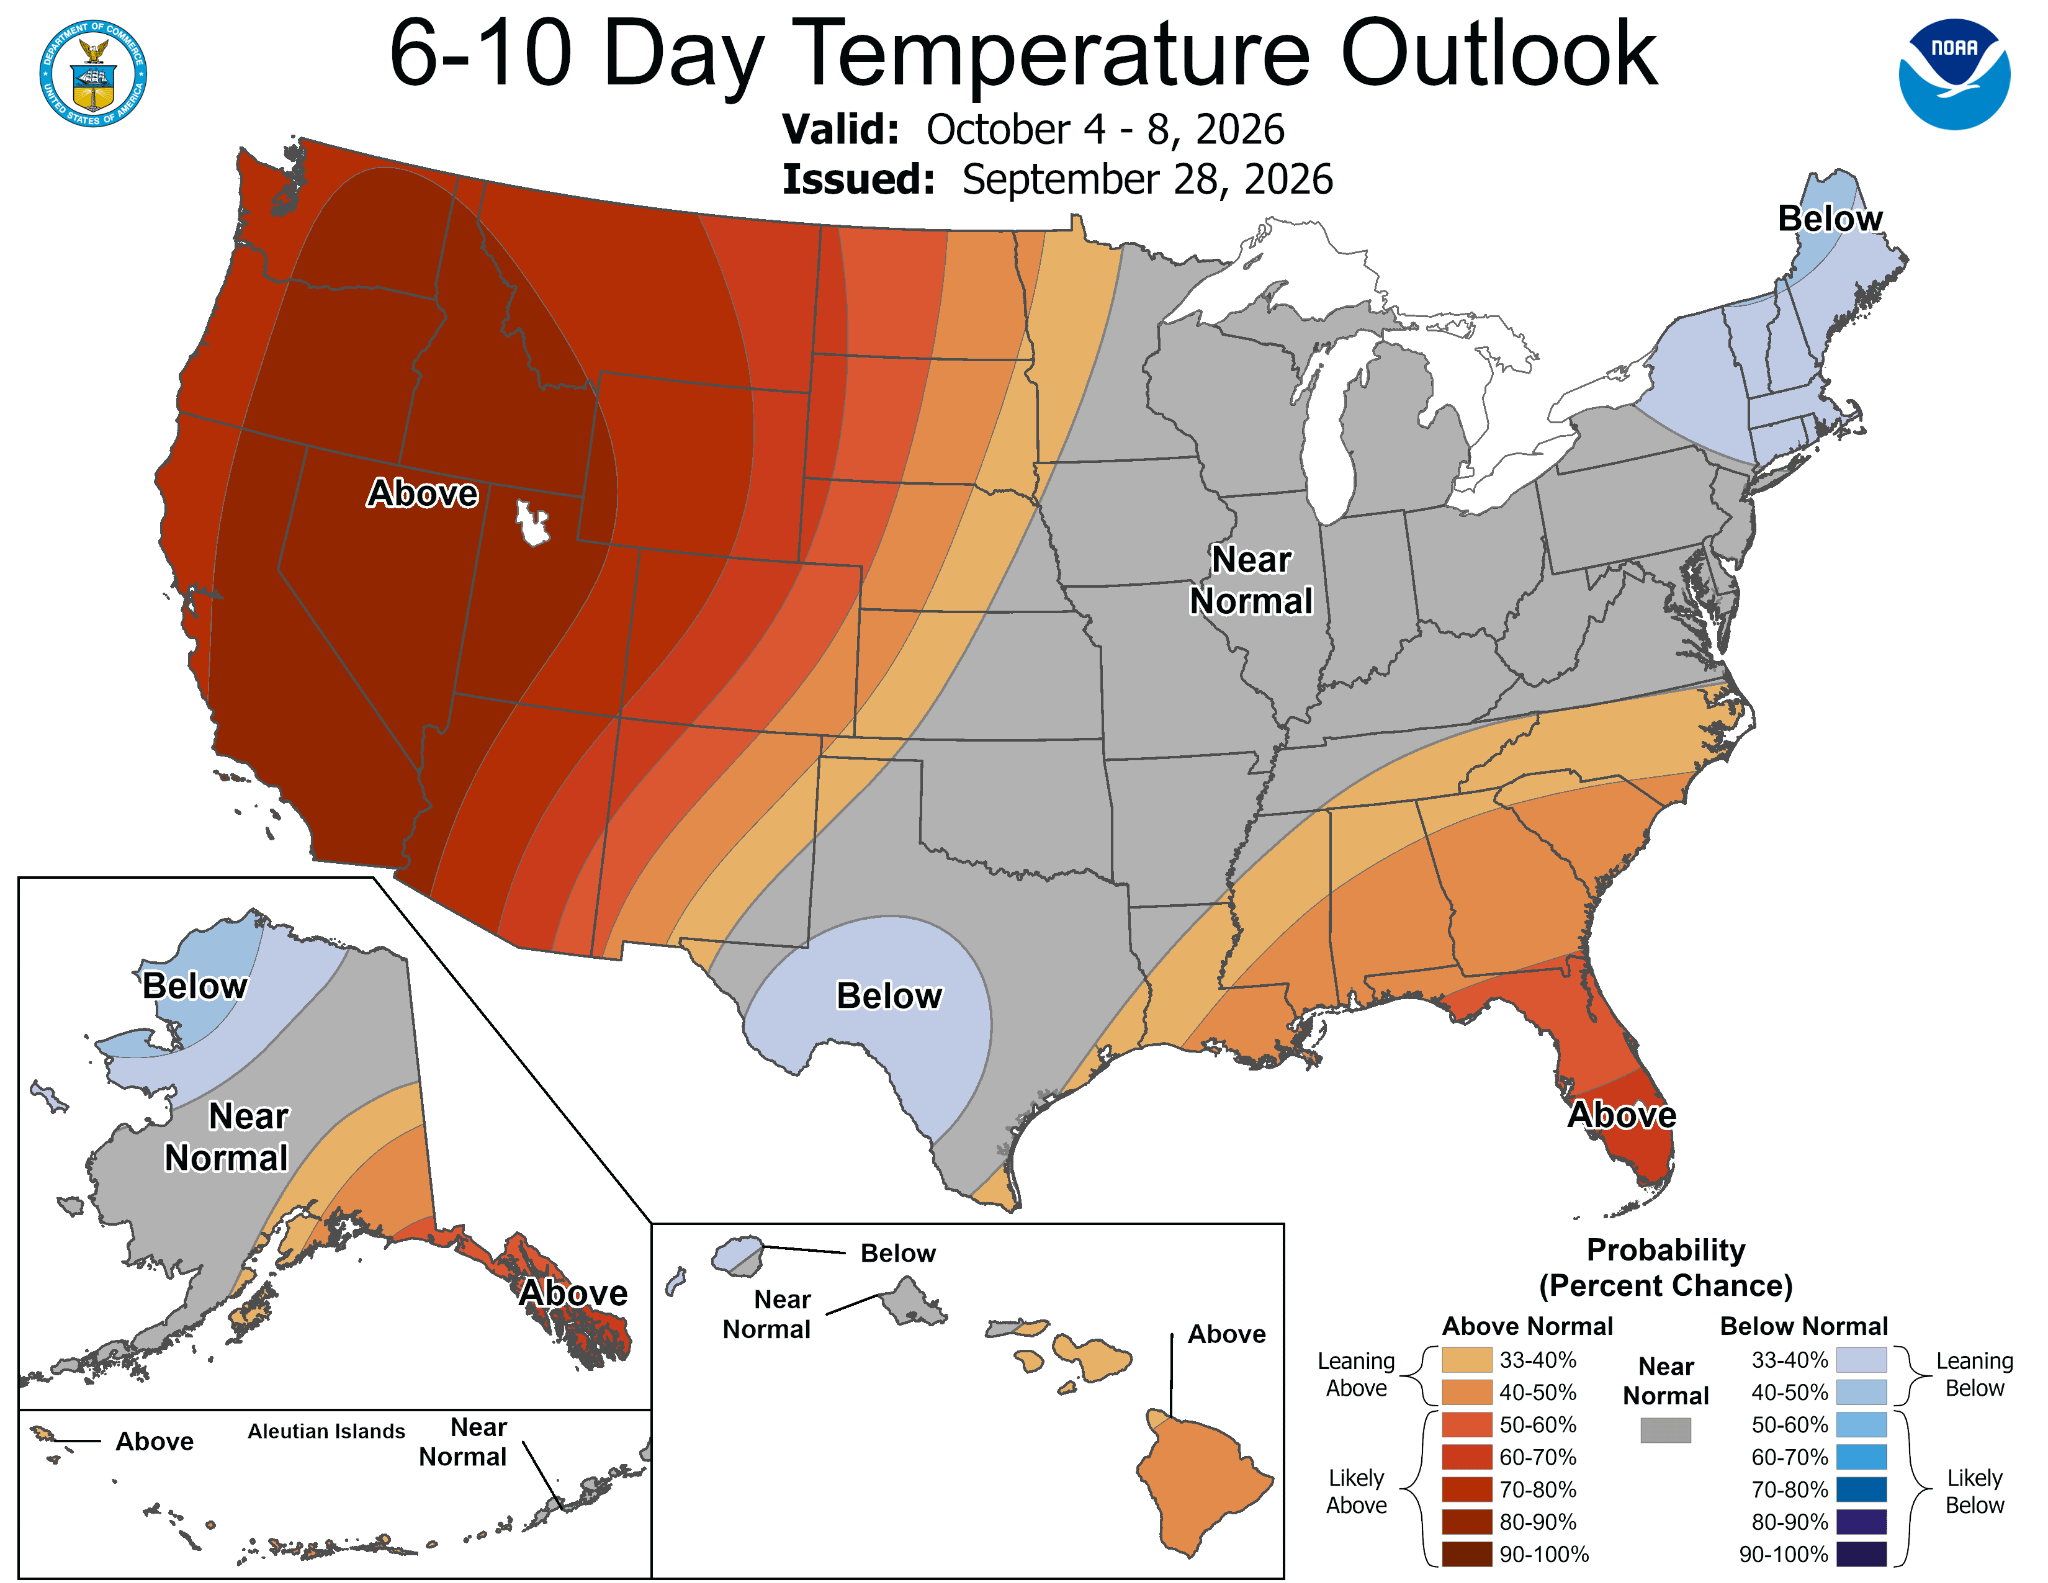
The temperature map from the release date of the EIA report clearly shows above-normal heat in the South, Midwest, and eastern regions of the country, which continues to support cooling demand. However, NOAA's forecast for October 4 to 8 shifts the signal toward the bears. The West is expected to see temperatures well above normal with a probability exceeding 80 percent, the Center and East remain near normal, and cooler weather is expected exclusively in New England and Texas. For a market entering the heating season, this means delayed start of heating demand. In the background, expectations remain for Super El Niño—a warmer than usual autumn and winter—which is the most serious medium-term argument for the bears.
Supply and demand balance
The EIA report for the week ended September 18 showed an injection of 53 billion cubic feet compared to expectations of 51 and a five-year average of 76. The surplus against seasonal norms narrowed as a result from 118 to 95 billion cubic feet. Inventories are 4.5 percent lower year-over-year, but still 2.9 percent above the five-year average.
On the supply side, the picture remains heavy. September production averaging 112.5 billion cubic feet per day is near records, and the EIA estimates that inventories at the end of October will reach 3,985 billion cubic feet, the highest in a decade and 5 percent above normal.
The counterweight is exports. Flows to nine major LNG terminals averaged 17.9 billion cubic feet per day in September compared to 17.2 in August, and reached 19.0 on Monday, despite the Cove Point terminal being offline for maintenance. European storage facilities are 71 percent full compared to a five-year average of 87 percent, maintaining fierce competition for flexible LNG cargoes between Asia and Europe.
Technical analysis
Price broke out of a multi-month consolidation bounded below by support around 3.000, tested multiple times since May, but stalled in the supply zone of 3.25 to 3.36, which blocked quotes back in June and July. The current pull-back from the upper edge of this zone is a classic rejection of resistance. An ascending trendline drawn from the August and September lows runs below. However, it is worth emphasizing that the breakout from this consolidation was linked to the rollover. RSI at 58.5 shows growing momentum without an overbought signal. MACD maintains a bullish setup, but the histogram is beginning to shrink, signaling potential fading of the impulse.
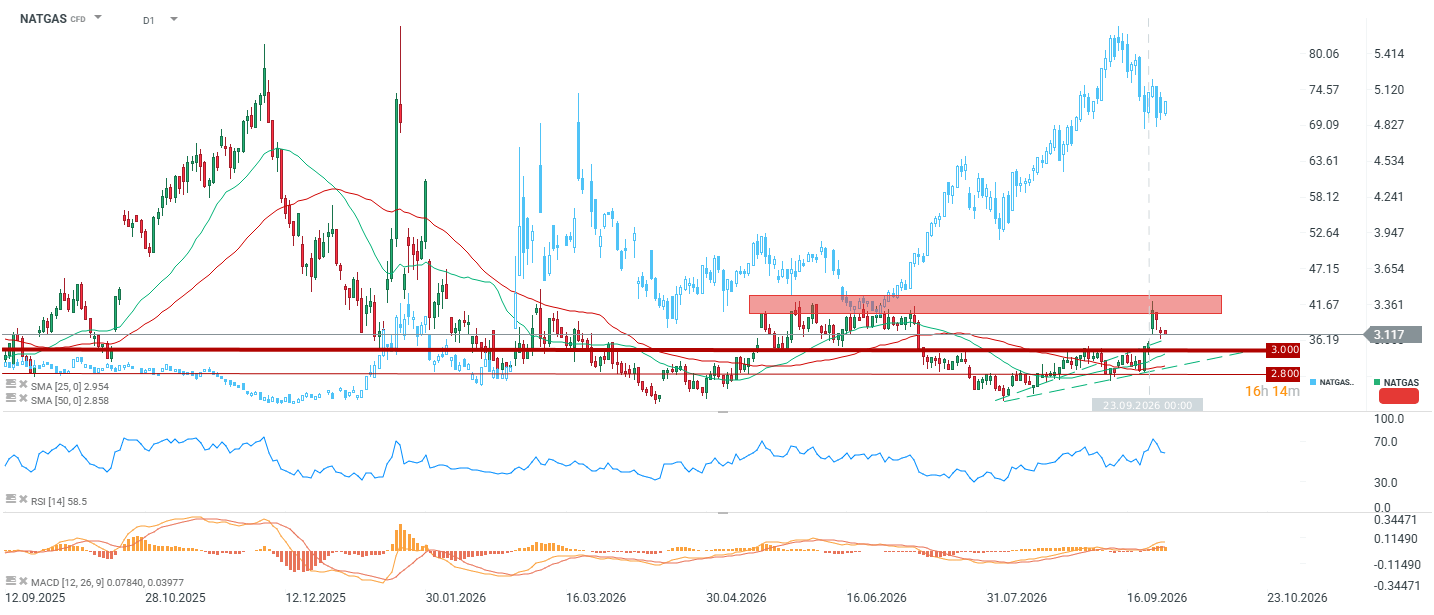
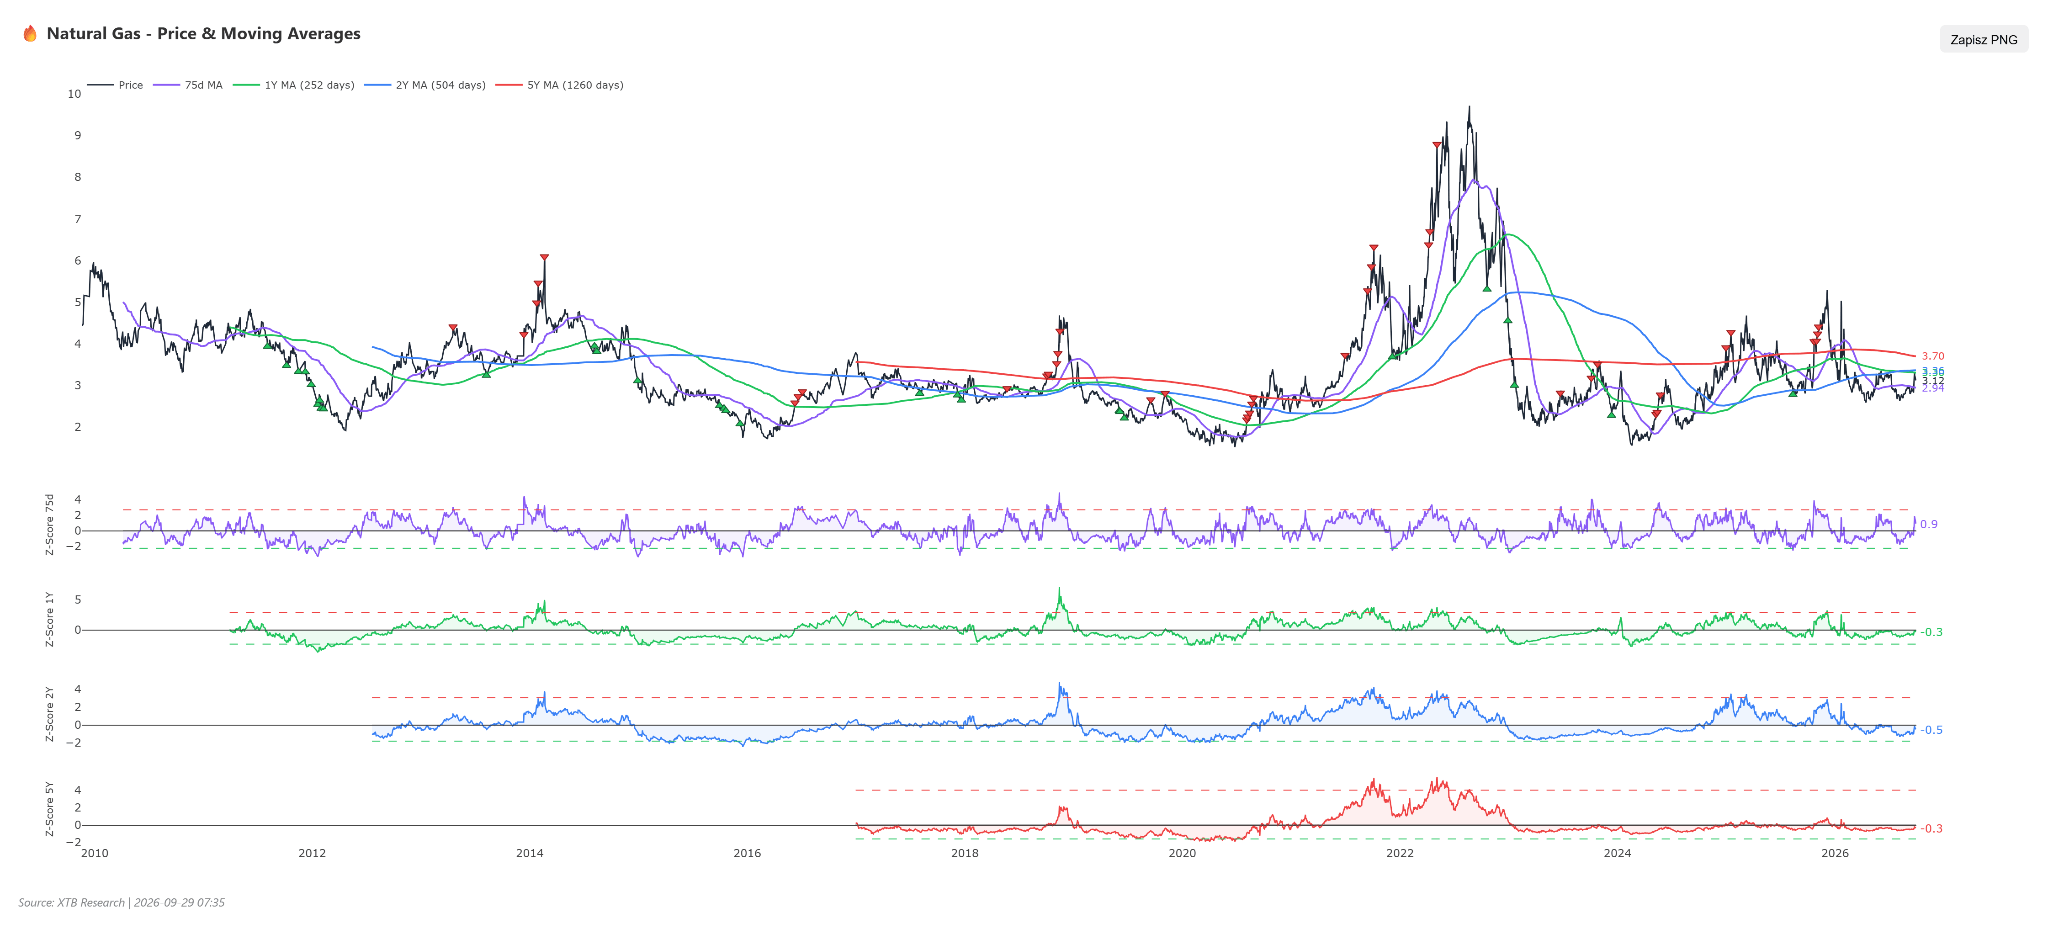
Price currently sits above the 25-period SMA at 2.954 and the 50-period SMA at 2.858. In a broader context, the structure remains bearish. Quotes broke above the 75-session and 1-year moving averages around 3.12, but remain below the 2-year average at 3.36 and distinctly below the 5-year average at 3.70. Until these two are overcome, we are talking about a bounce within a downtrend, not a regime change.
Valuation and positioning
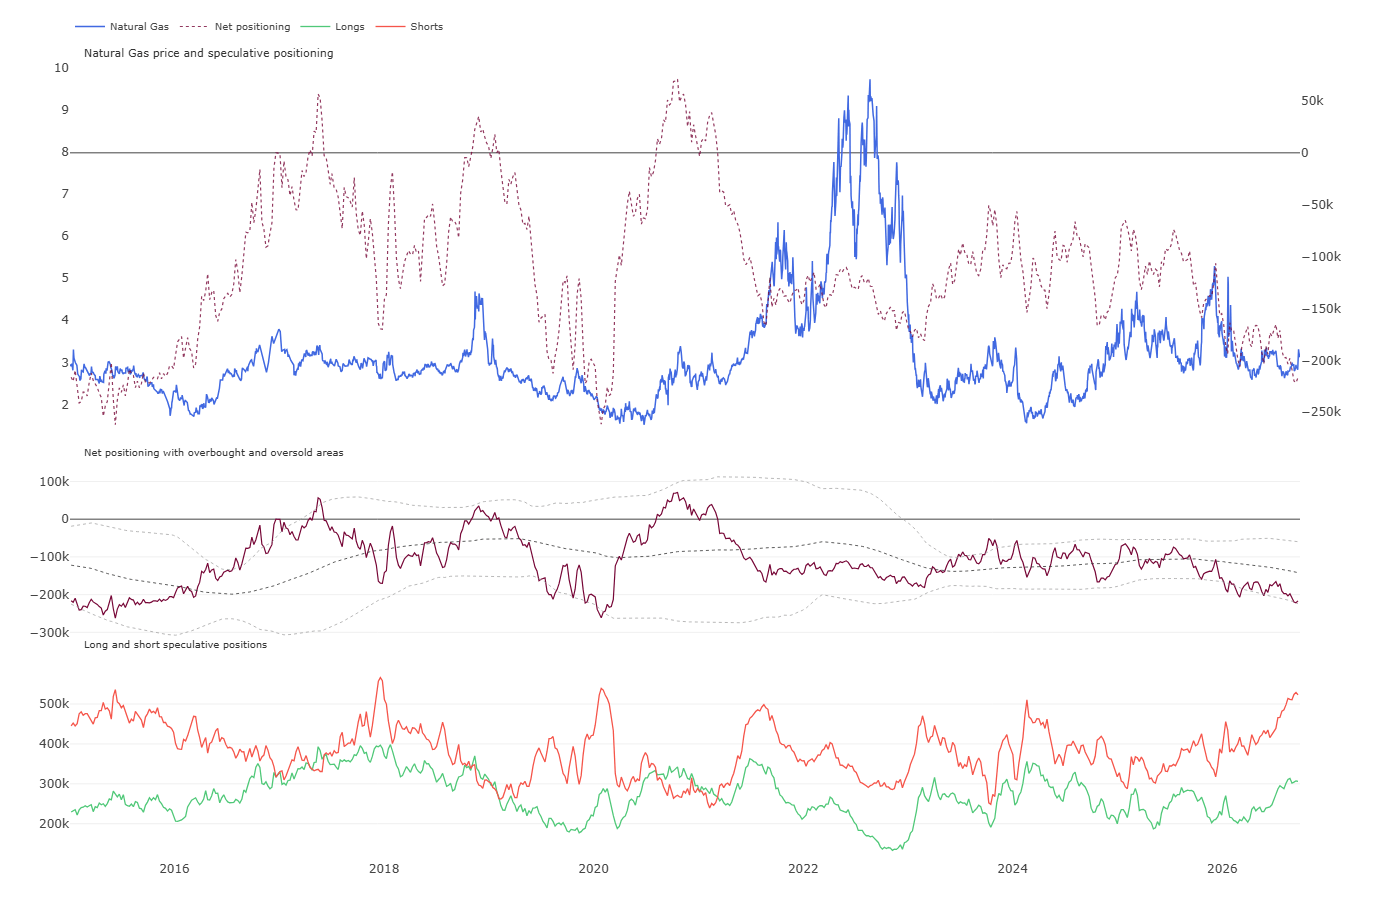
The 1-year Z-score is minus 0.30, 2-year is minus 0.50, and 5-year is minus 0.34, so the commodity has emerged from deep discount territory, but is not expensive. The key factor, however, is the futures market. Net speculative positioning fell to around minus 220 thousand contracts, the lowest since 2020 and near the bottom of the oversold range. This is driven by a record number of short positions exceeding 520 thousand contracts. Such extreme positioning creates a real risk of forced short covering on the first cold spell impulse and is currently the strongest argument for the bulls, much stronger than valuation itself.
Summary
The recent upward move is largely the sum of two one-off effects—contract rollover and pipeline failure—both of which have now faded. Record production and forecasts of the highest inventories in a decade weigh on prices, while rising LNG exports and extreme short positioning from funds create asymmetric upside risk. The path of October weather will be decisive. If a warm scenario materializes, the market will return toward 2.80. If the first real cold spell arrives, the scale of short positions could generate a move much stronger than fundamentals alone would suggest. Nevertheless, at least for now, it appears that after each rollover price will come under downward pressure. On the other hand, any gust of cold weather could mean double-digit price increases given the very low base.


Economic Calendar - RBA Hawkish Move and a Wave of Central Banker Speeches



Morning Briefing: Higher Rates in Australia and Further Rise in Oil Prices


Daily Summary: Lack of progress in negotiations weighs on Wall Street and precious metals (28.09.2026)

Gold falls 4%
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.