


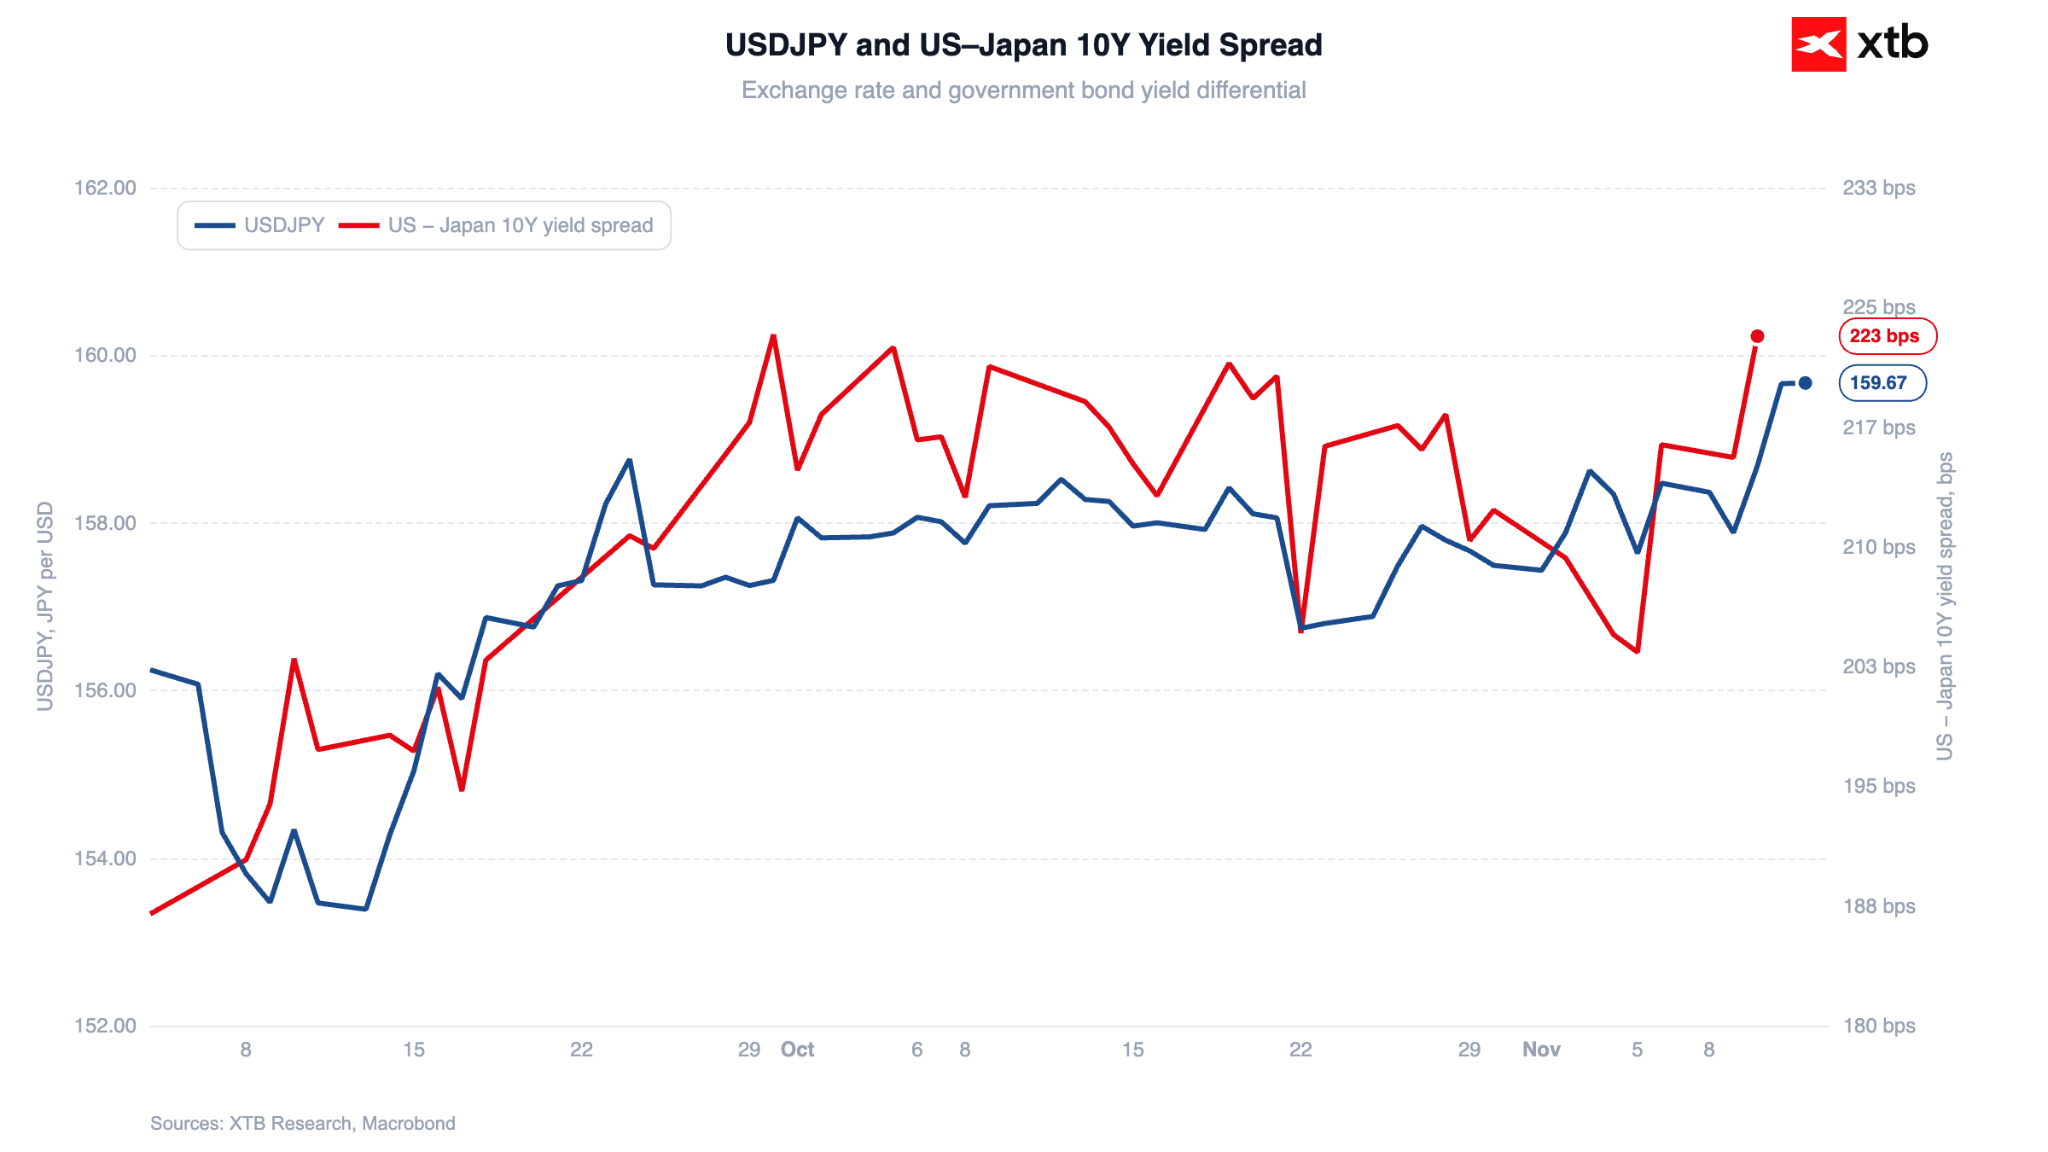
The yen has suffered a pronounced weakness in recent days. Overnight, USDJPY touched a two-month high of 159.94 and currently remains near these levels. This movement is primarily driven by rising expectations of interest rate hikes by the Federal Reserve, following higher-than-expected US inflation data for October.
Figure 1: USDJPY and US–Japan yield spread (08.2026 - 11.2026)
 Source: XTB Research, 12.11.2026
Fed officials support the dollar
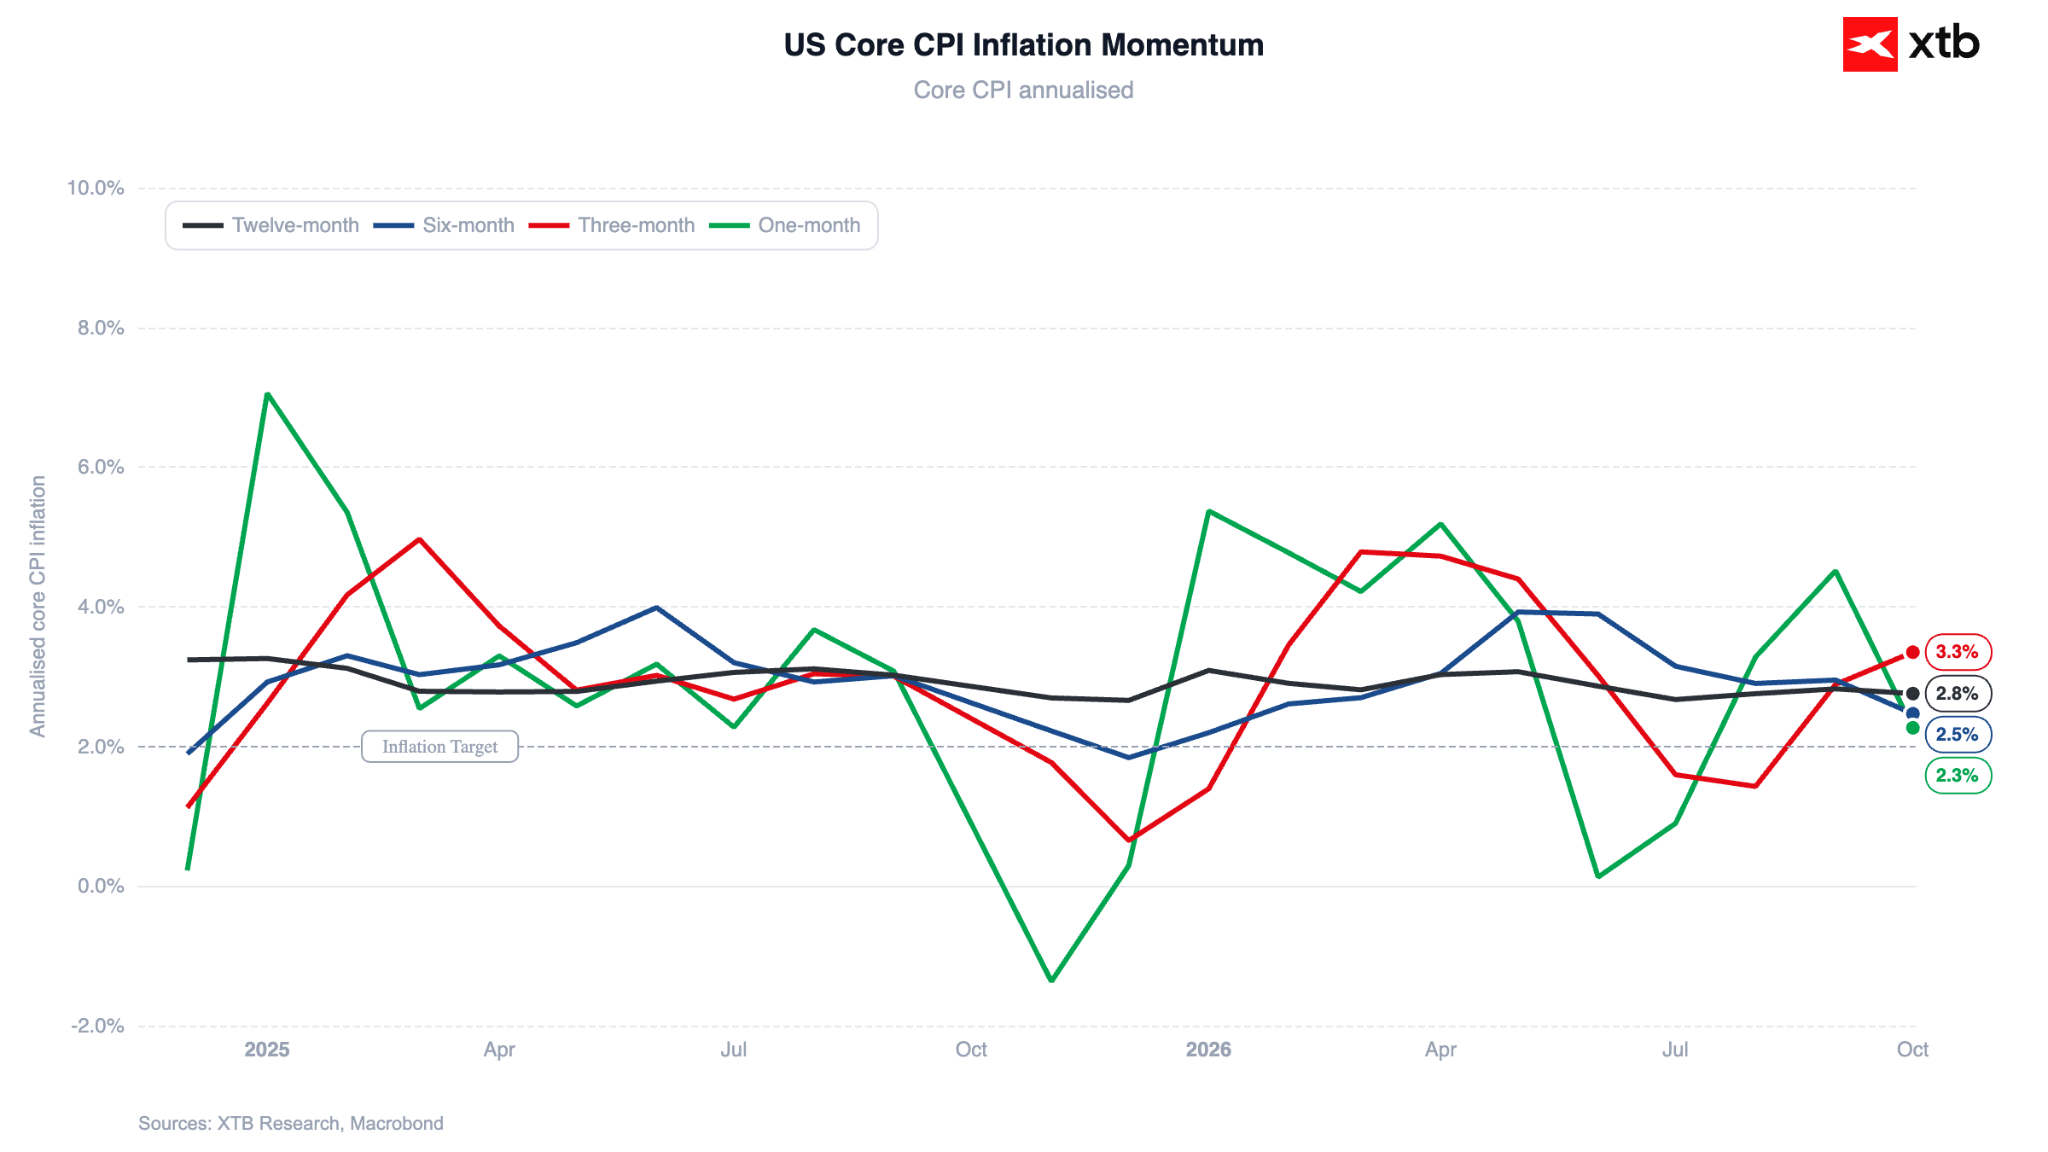
As noted earlier, market expectations for Federal Reserve rate hikes are climbing. Investors have fully priced in a rate increase for December, with some even speculating on a 50 bps move, though we view this scenario as highly unlikely. To recap, October inflation surpassed forecasts, with the headline CPI rising 0.4% m/m against the anticipated 0.3%, while core inflation increased by 0.3% compared to the 0.2% consensus.
Figure 2: US core CPI inflation momentum (2024 - 2026)
 Source: XTB Research, 12.11.2026
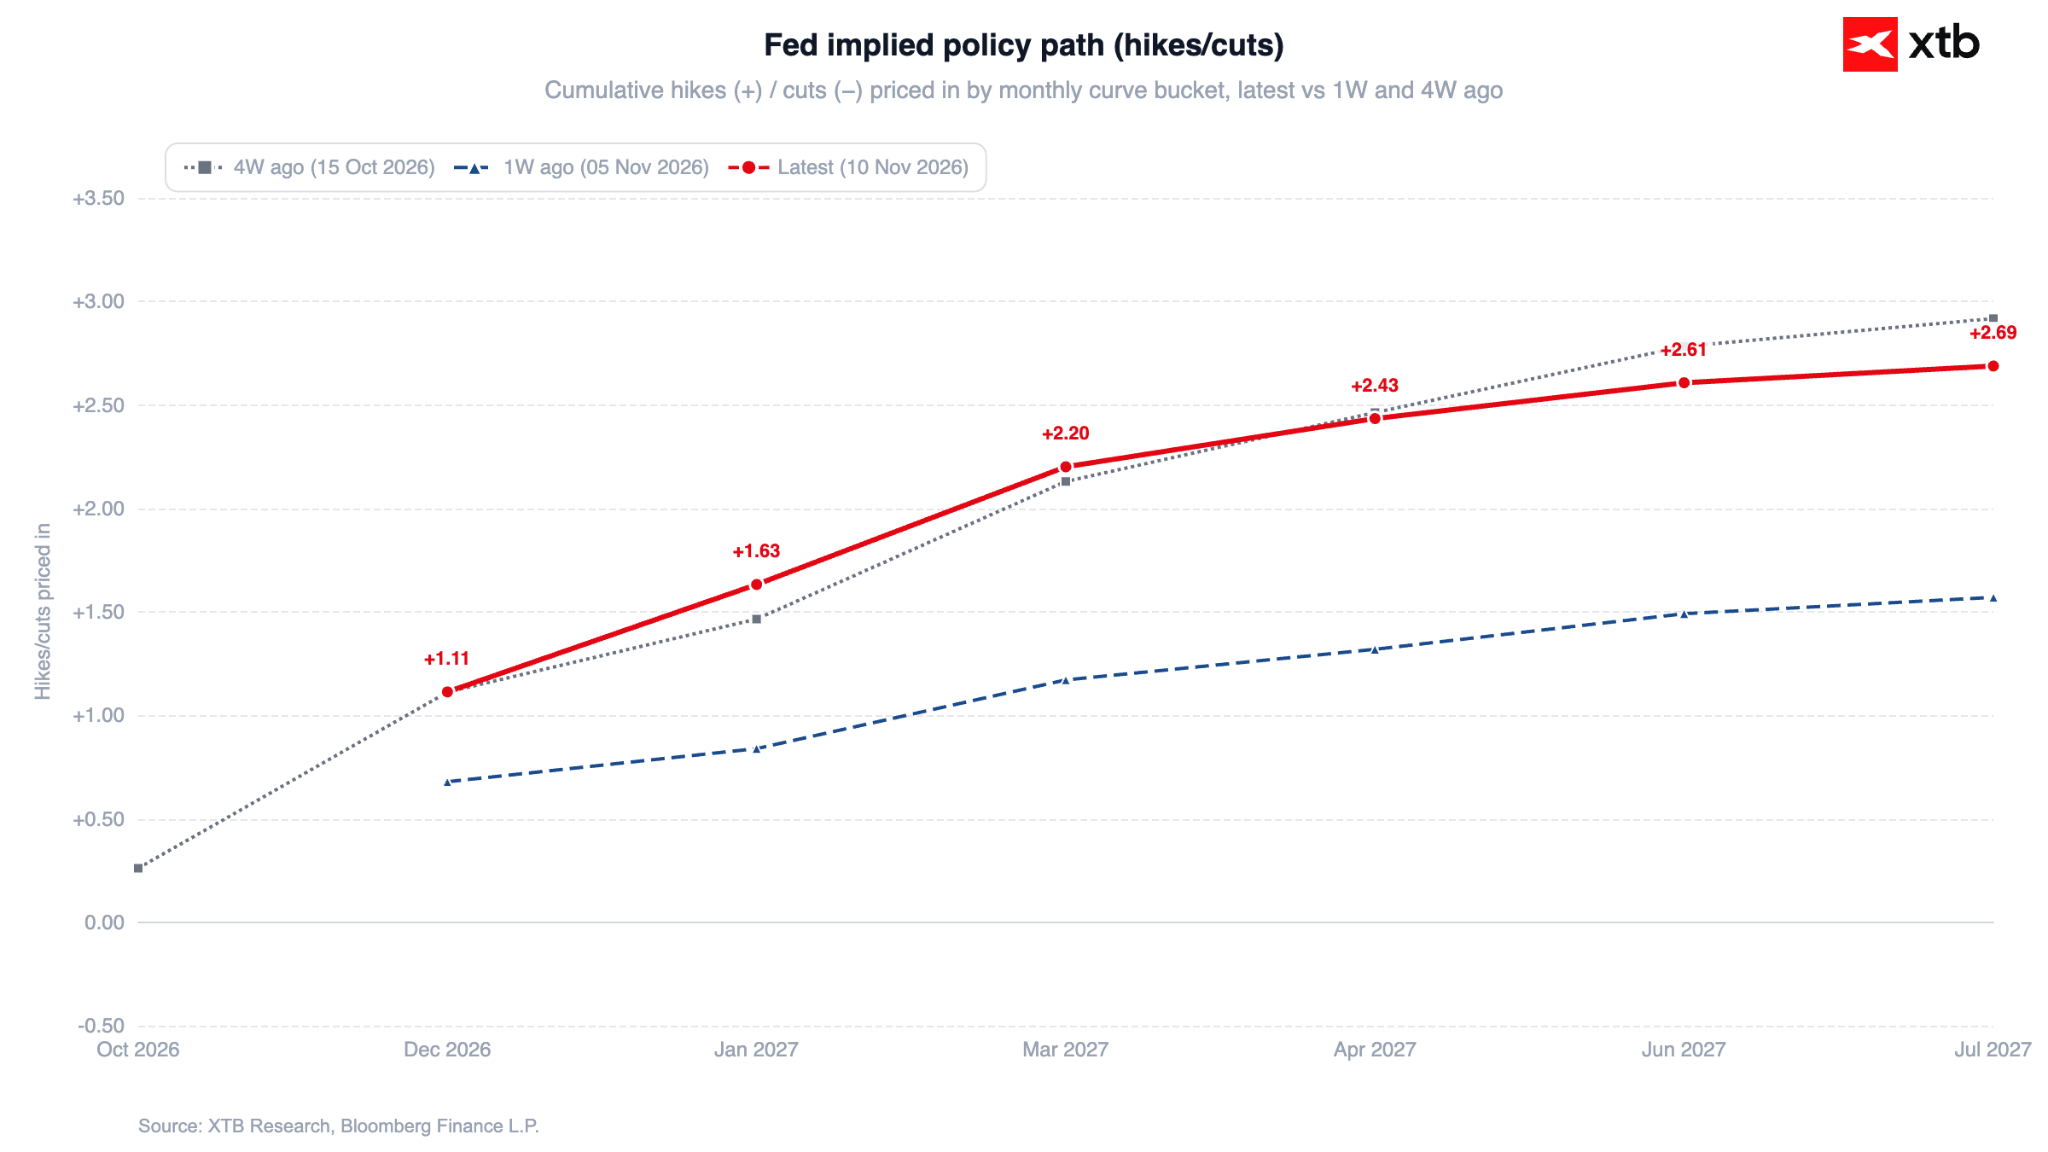
Christopher Waller expressed support for a 25 bps hike in December, noting that if core inflation persists at or above 0.3%, a 50 bps increase should be considered. Chicago Fed President Austan Goolsbee described the October reading as borderline disturbing.
Figure 3: Market-implied Fed policy path (2026 - 2027)
 Source: XTB Research, 12.11.2026
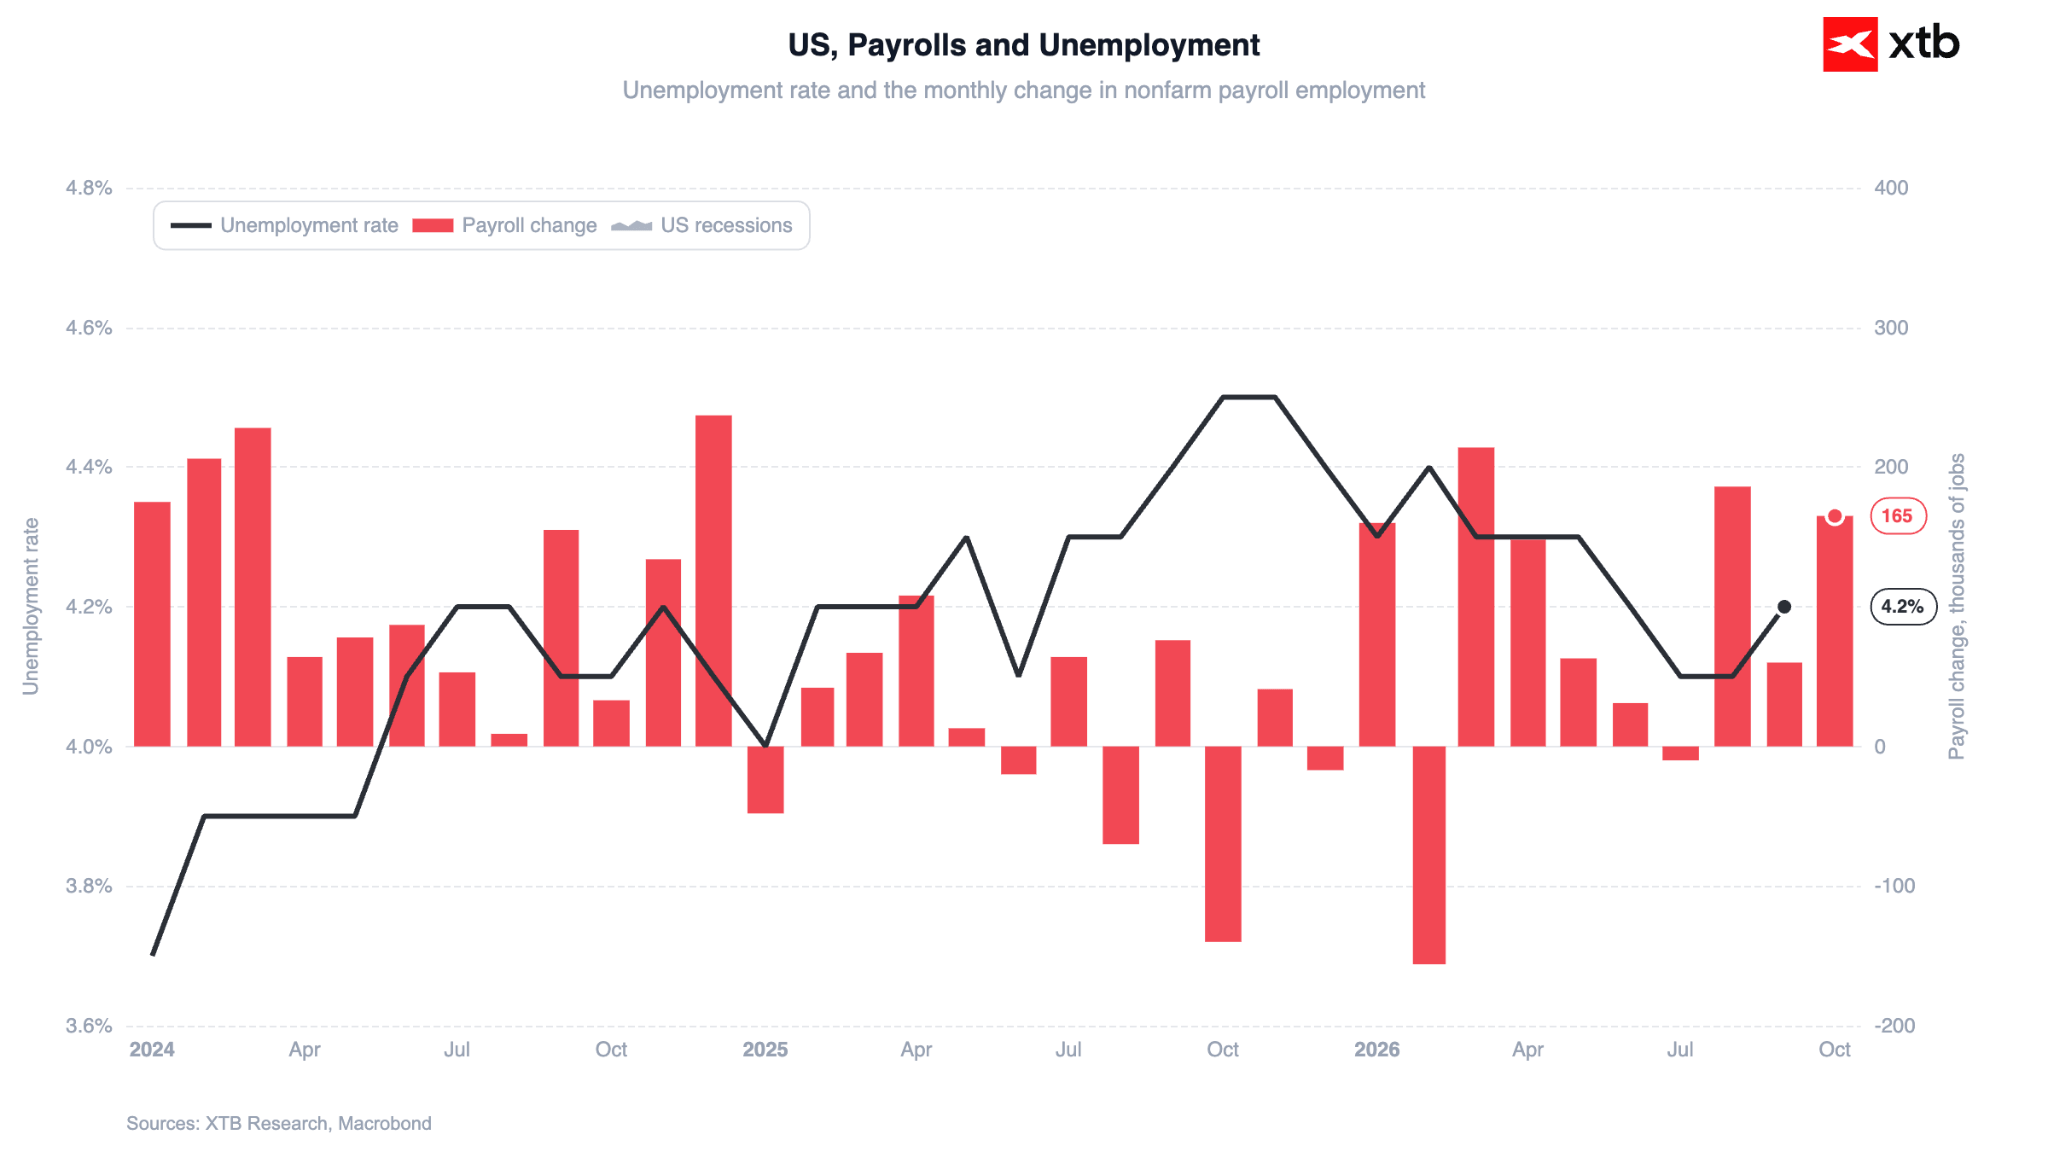
Attention now shifts to today's release of US weekly initial jobless claims at 14:30. However, their market impact is likely to be limited given the recent NFP publication.
Figure 4: US Nonfarm Payrolls and unemployment rate (2024 - 2026)
 Source: XTB Research, 12.11.2026
Policy rate differential remains wide
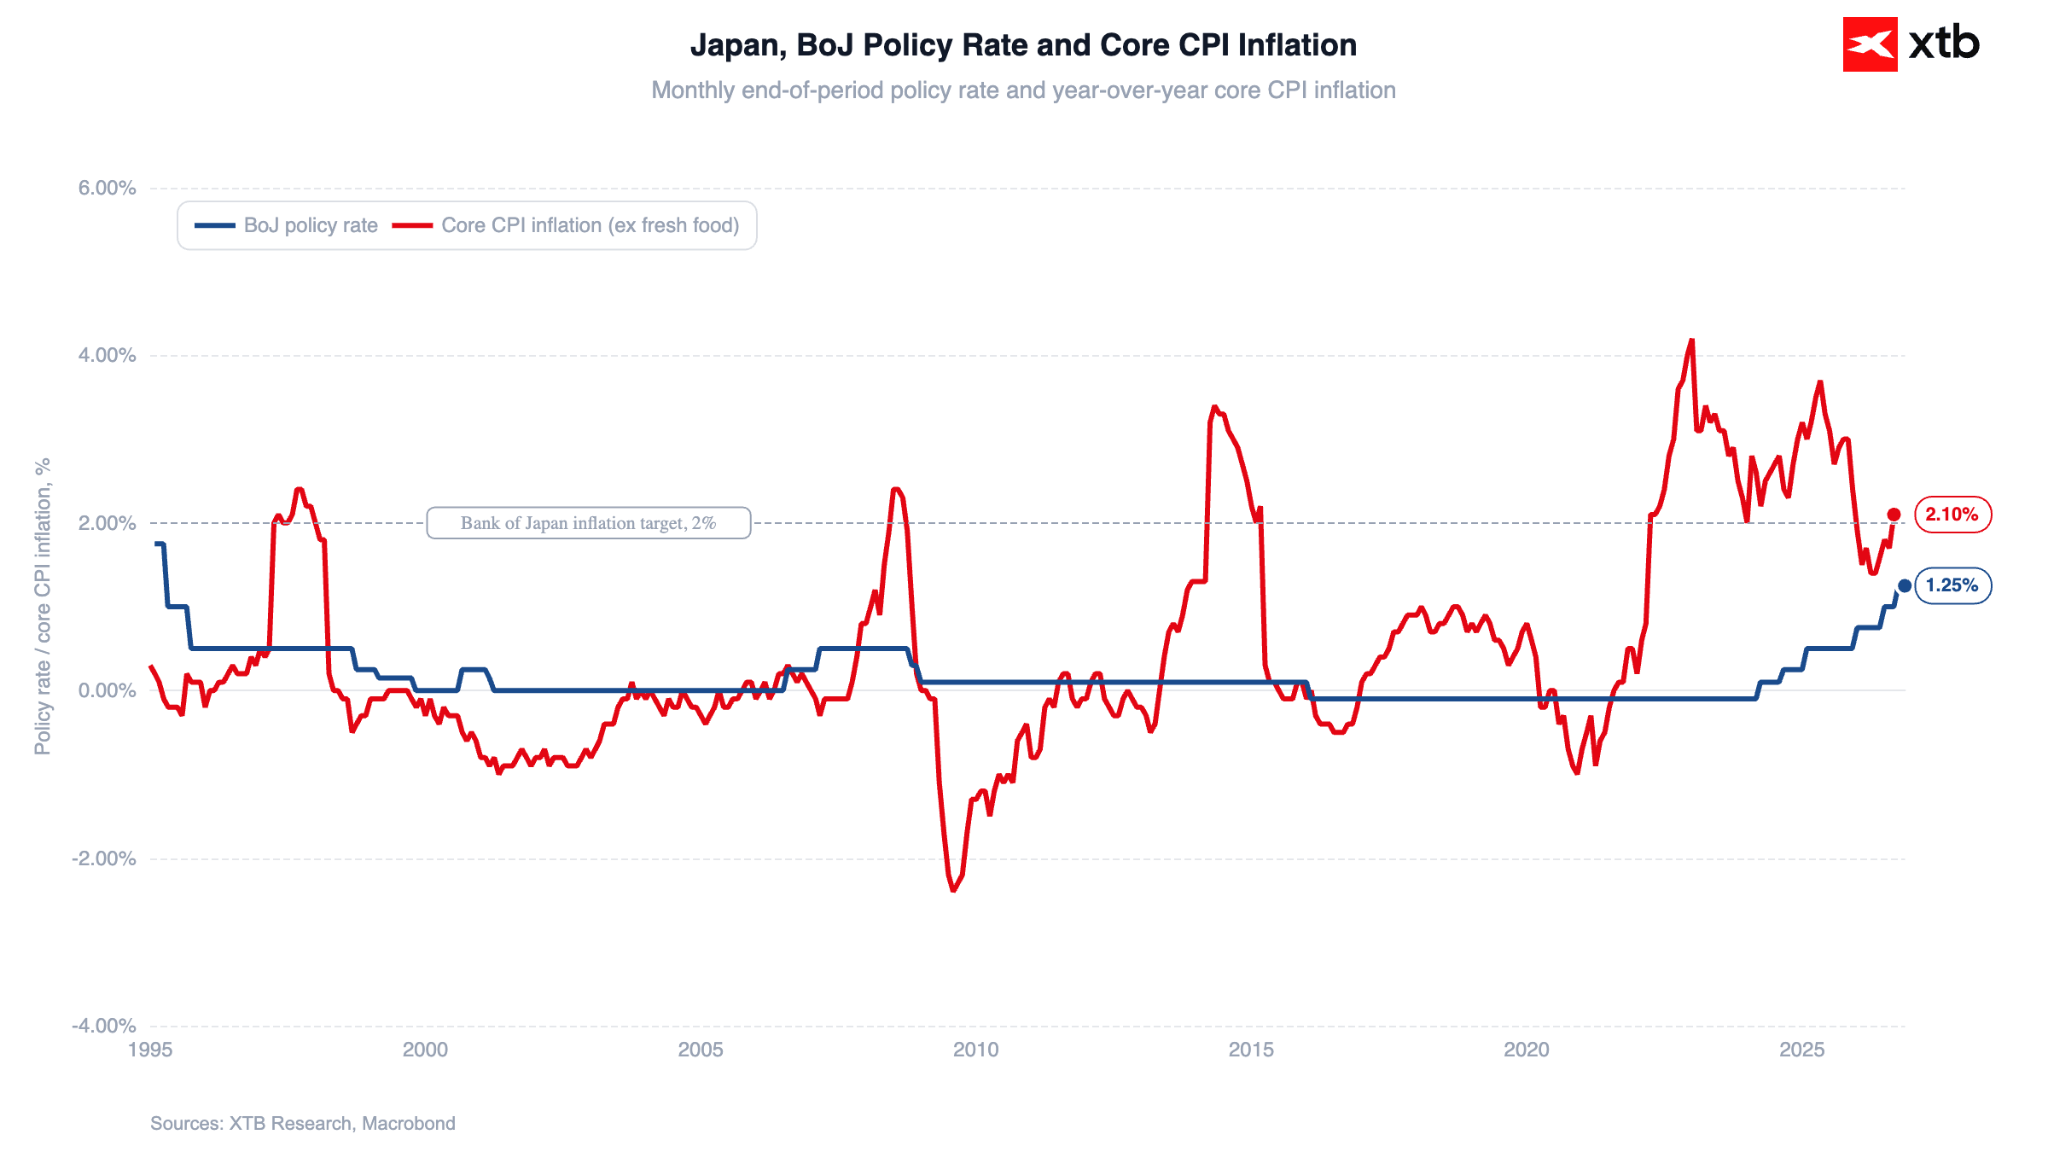
The Bank of Japan recently declared an end to its ultra-loose monetary policy framework, citing victory over sub-target core inflation. Interest rate hikes are currently proceeding at a quarterly pace, the fastest since 1990. Rhetoric from BoJ officials remains generally hawkish, yet it has not been sufficiently aggressive to lift rate expectations enough to match the trajectory projected for the Federal Reserve. Moreover, dovish commentary continues to emerge, as detailed below.
Markets are currently pricing in roughly an 80% probability of a BoJ rate increase in December, with a similar likelihood attached to another hike in March. Under the baseline scenario, this implies a pause in January, keeping to the quarterly tightening pace. In contrast, two rate hikes from the Federal Reserve are fully priced in through March, alongside a modest ~20% chance of a rate increase at each upcoming meeting (December, January, and March).
Dovish signals from the BoJ
BoJ Board member Toichiro Asada, widely regarded as one of the central bank's most dovish policy makers, stated today that while he does not oppose rate hikes, he urges caution regarding their pace. He emphasized that recent price increases were driven largely by supply-side factors rather than demand, warning that further tightening could weaken household consumption without meaningfully curbing core inflation.
Figure 5: BoJ policy rate and core CPI inflation in Japan (1995 - 2026)
 Source: XTB Research, 12.11.2026
Asada noted that his view is shared by other members of the board. Notably, September data revealed the sharpest decline in household spending since the pandemic. Preliminary Q3 GDP figures are due on Monday, with consensus pointing to a significant growth slowdown to around 0.1% q/q.
Tokyo reiterates intervention readiness
Atsushi Mimura, Japan's top foreign exchange official at the Ministry of Finance, described recent currency moves as overly rapid, cautioning that investors may have forgotten the summer episodes of active intervention. He declined, however, to specify key technical levels.
Chief Cabinet Secretary Minoru Kihara echoed these concerns, stating that yen undervaluation presents a serious challenge and confirming that the Ministry of Finance will maintain close communication with the US Treasury Department.
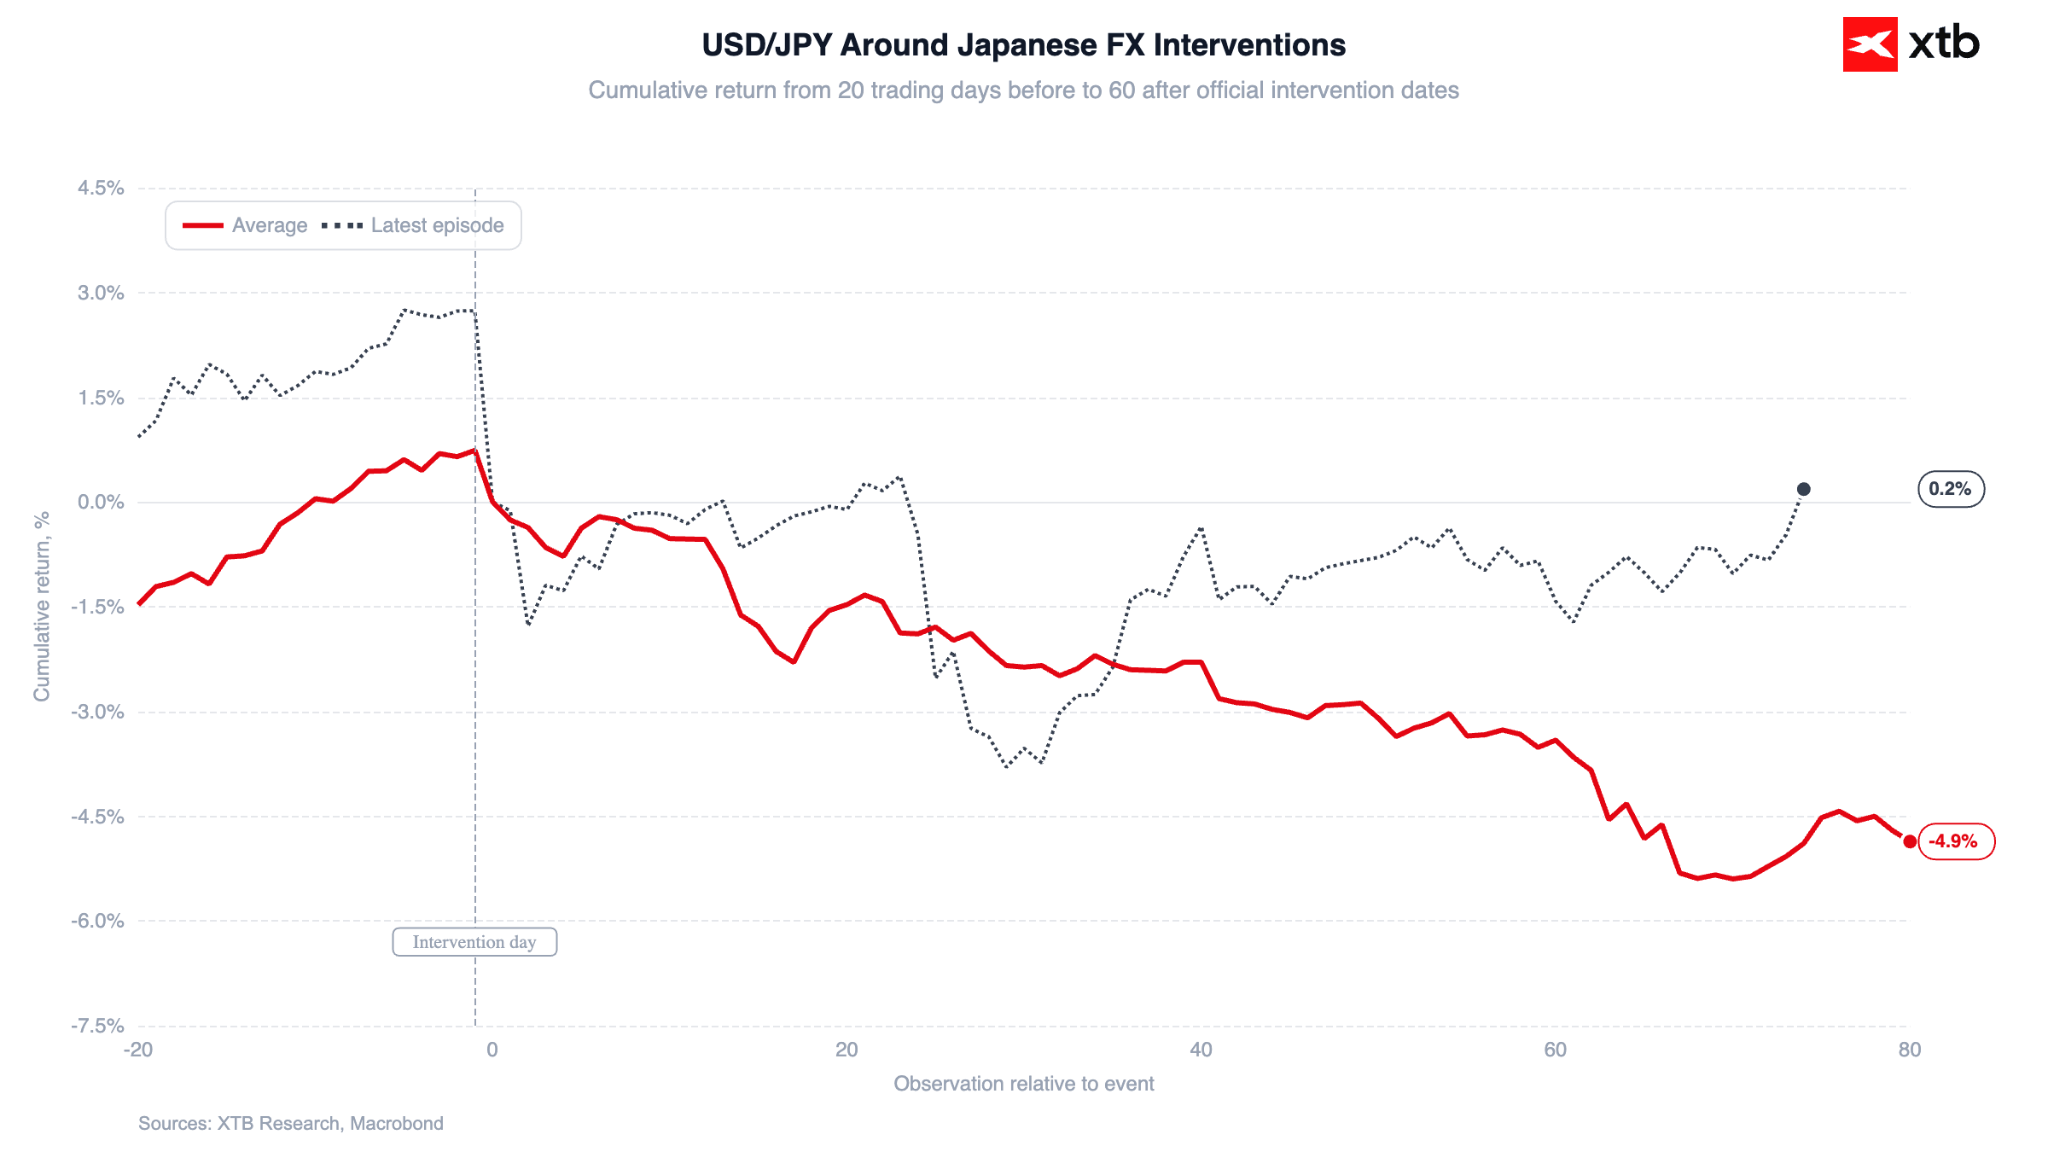
To recap the summer events, Japan deployed approximately $96.5bn over three days starting 30 July to buy yen. This marked the first joint FX intervention with the US Treasury since 1998, pushing USDJPY down from above 163.00 to 155.23.
Figure 6: USDJPY around Japanese FX intervention episodes (2022 - 2026)
 Source: XTB Research, 12.11.2026
Outlook
Looking ahead, Japan's preliminary GDP data will be released on Monday, followed by key central bank rate decisions in December: the Fed on 9 December and the BoJ on 19 December. Until then, the yen is likely to remain under pressure, particularly if incoming US data points to persistent inflationary momentum. Continued weakness in the yen will heighten the probability of direct FX intervention by Japanese authorities.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



📊Daily Summary: Tech sector drives Wall Street rebound, DAX leads in Europe


⬇️EURUSD pulls back ahead of CPI


📈Morning Wrap: Tech Bounce and Oil Price Collapse Following Signals of De-escalation Around Iran


Daily Summary: From Panic to Euphoria. The Market Recoups Losses.
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.