


CoreWeave remains one of the clearest examples of the contradictions driving the artificial intelligence market.
The cloud computing provider is rapidly growing revenue and securing multi year contracts, yet infrastructure expansion is consuming capital faster than the business can generate it.
For investors, the pressing question is how much AI value accrues to shareholders, and how much goes to hardware suppliers or lenders.
Financials
- CoreWeave’s revenue in the second quarter of 2026 increased by 112% year over year to USD 2.58 billion.
- The company raised its full year sales forecast to USD 12.4 to 13.2 billion.
- The backlog of contracted future revenue reached around USD 104 billion, and in early Q3 the company additionally secured more than USD 25 billion in new customer commitments.
Demand is strong, but the company still remains extremely inefficient at converting orders into profits.
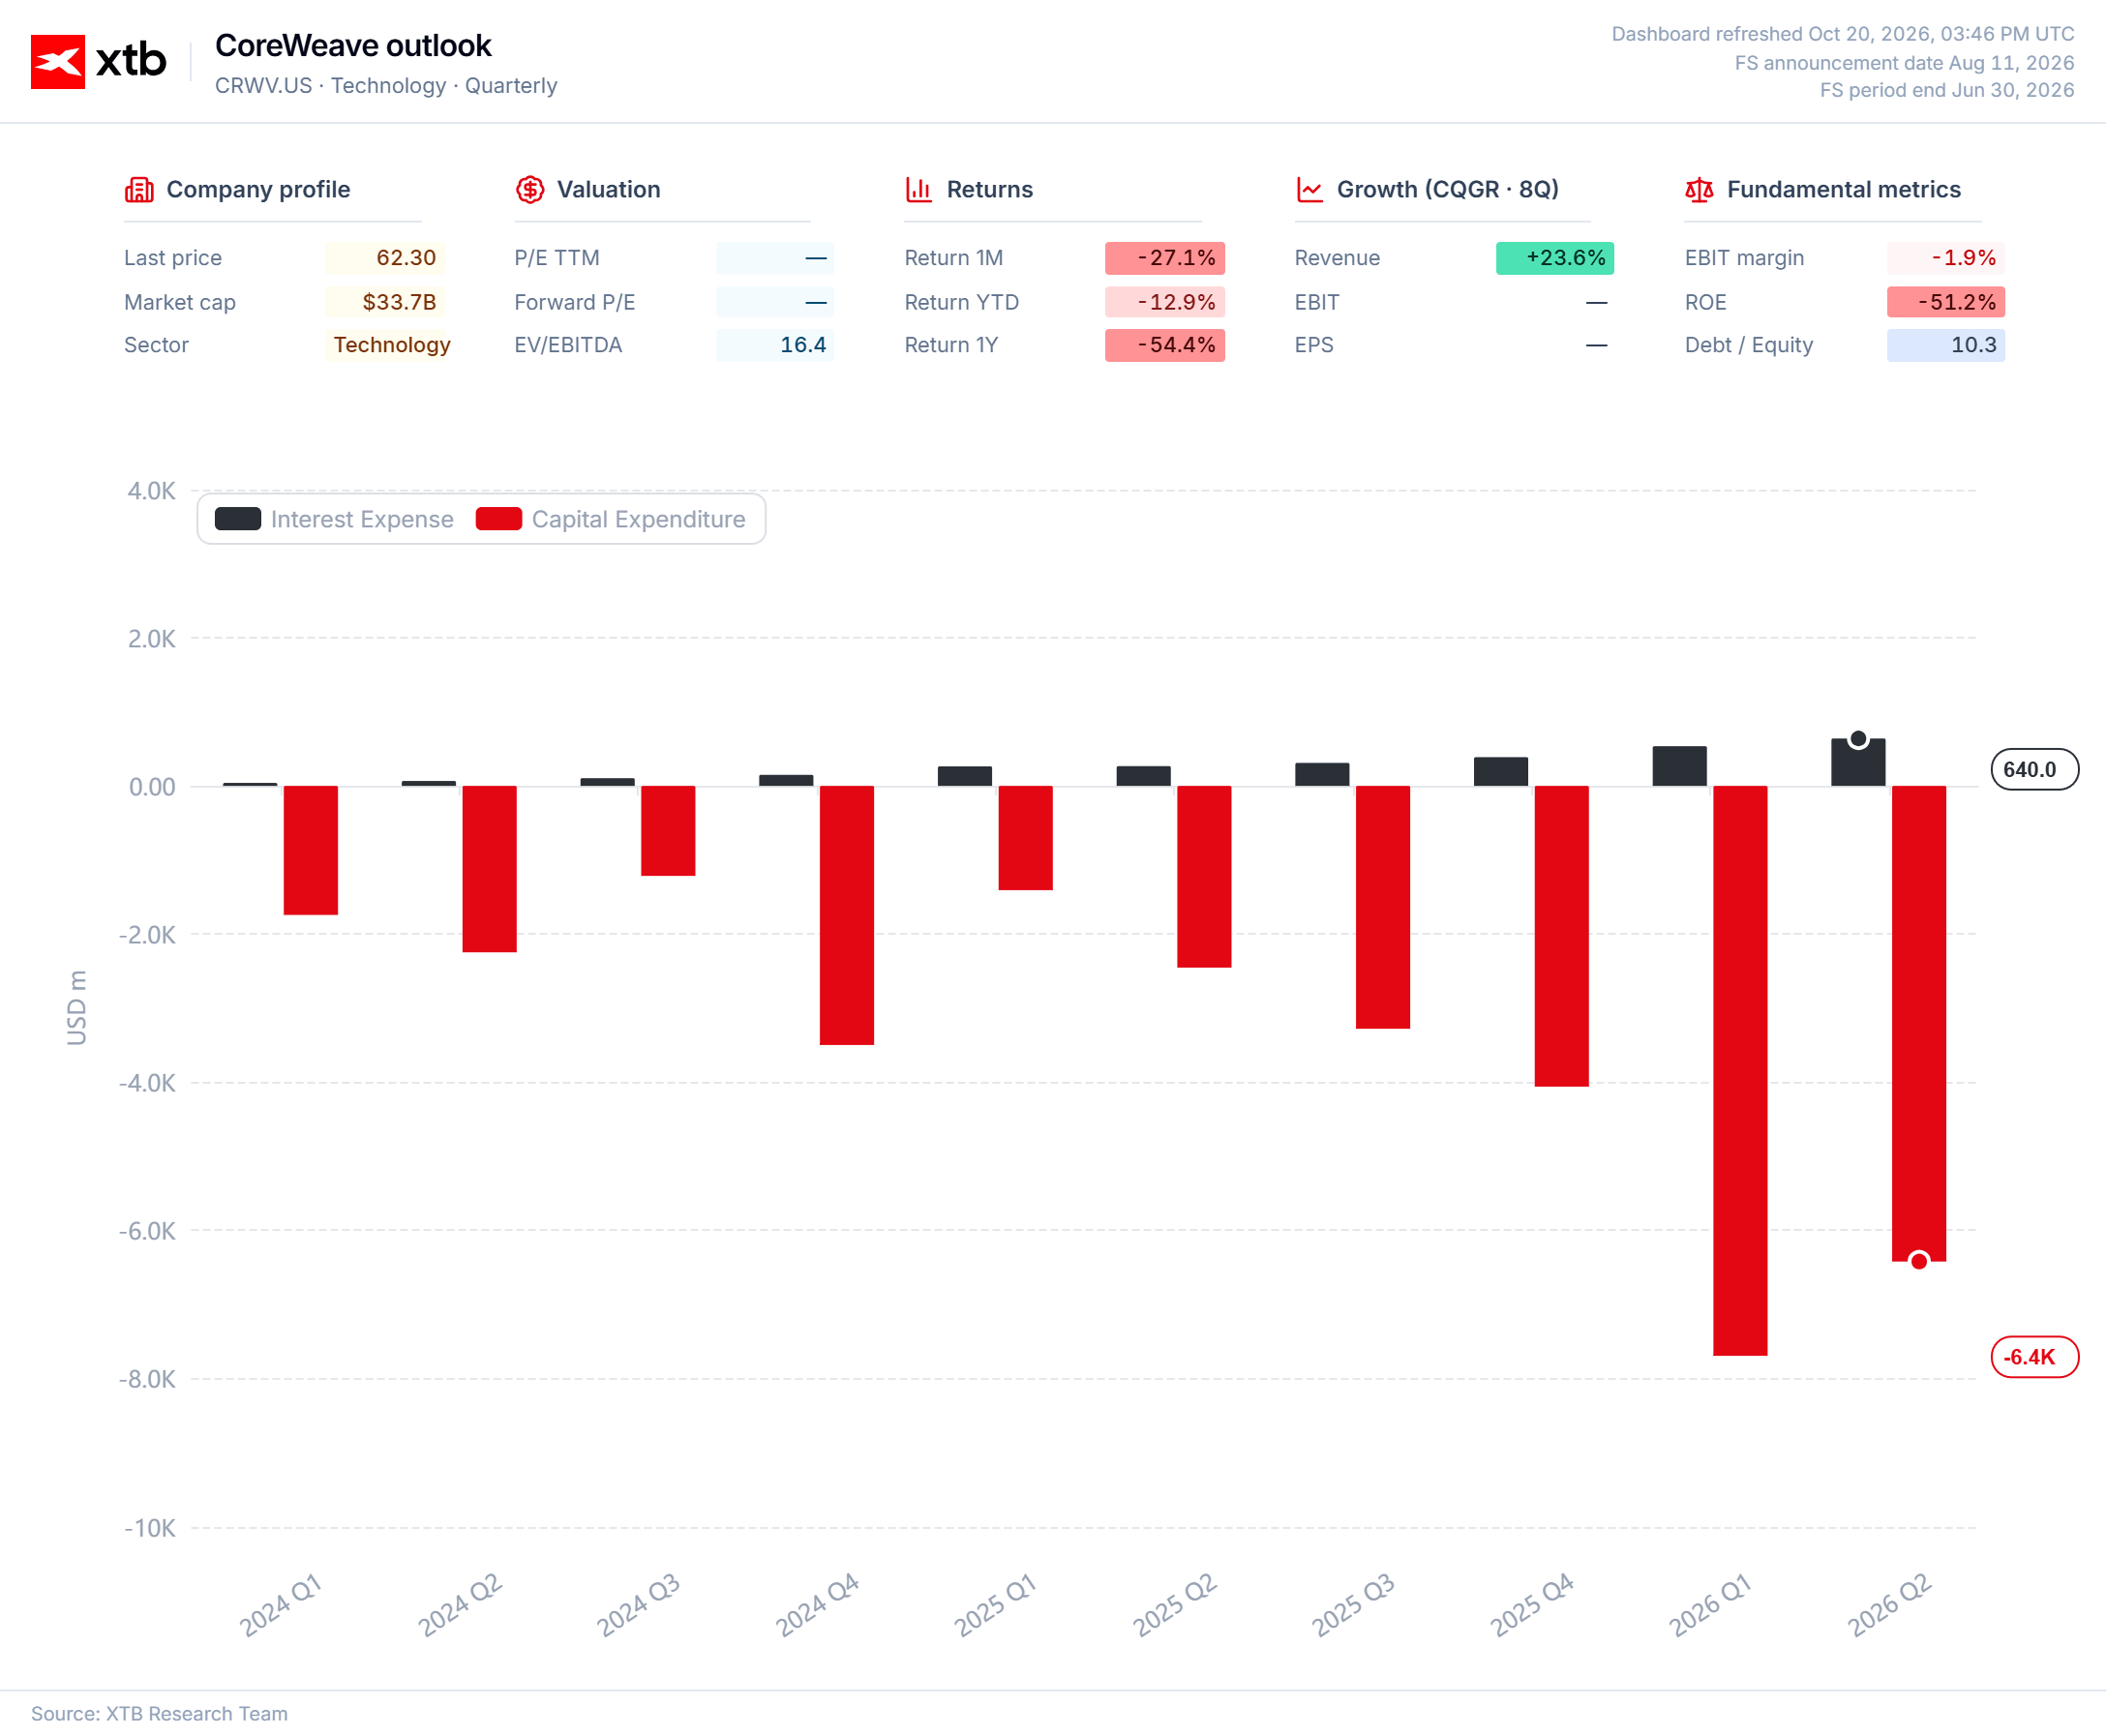
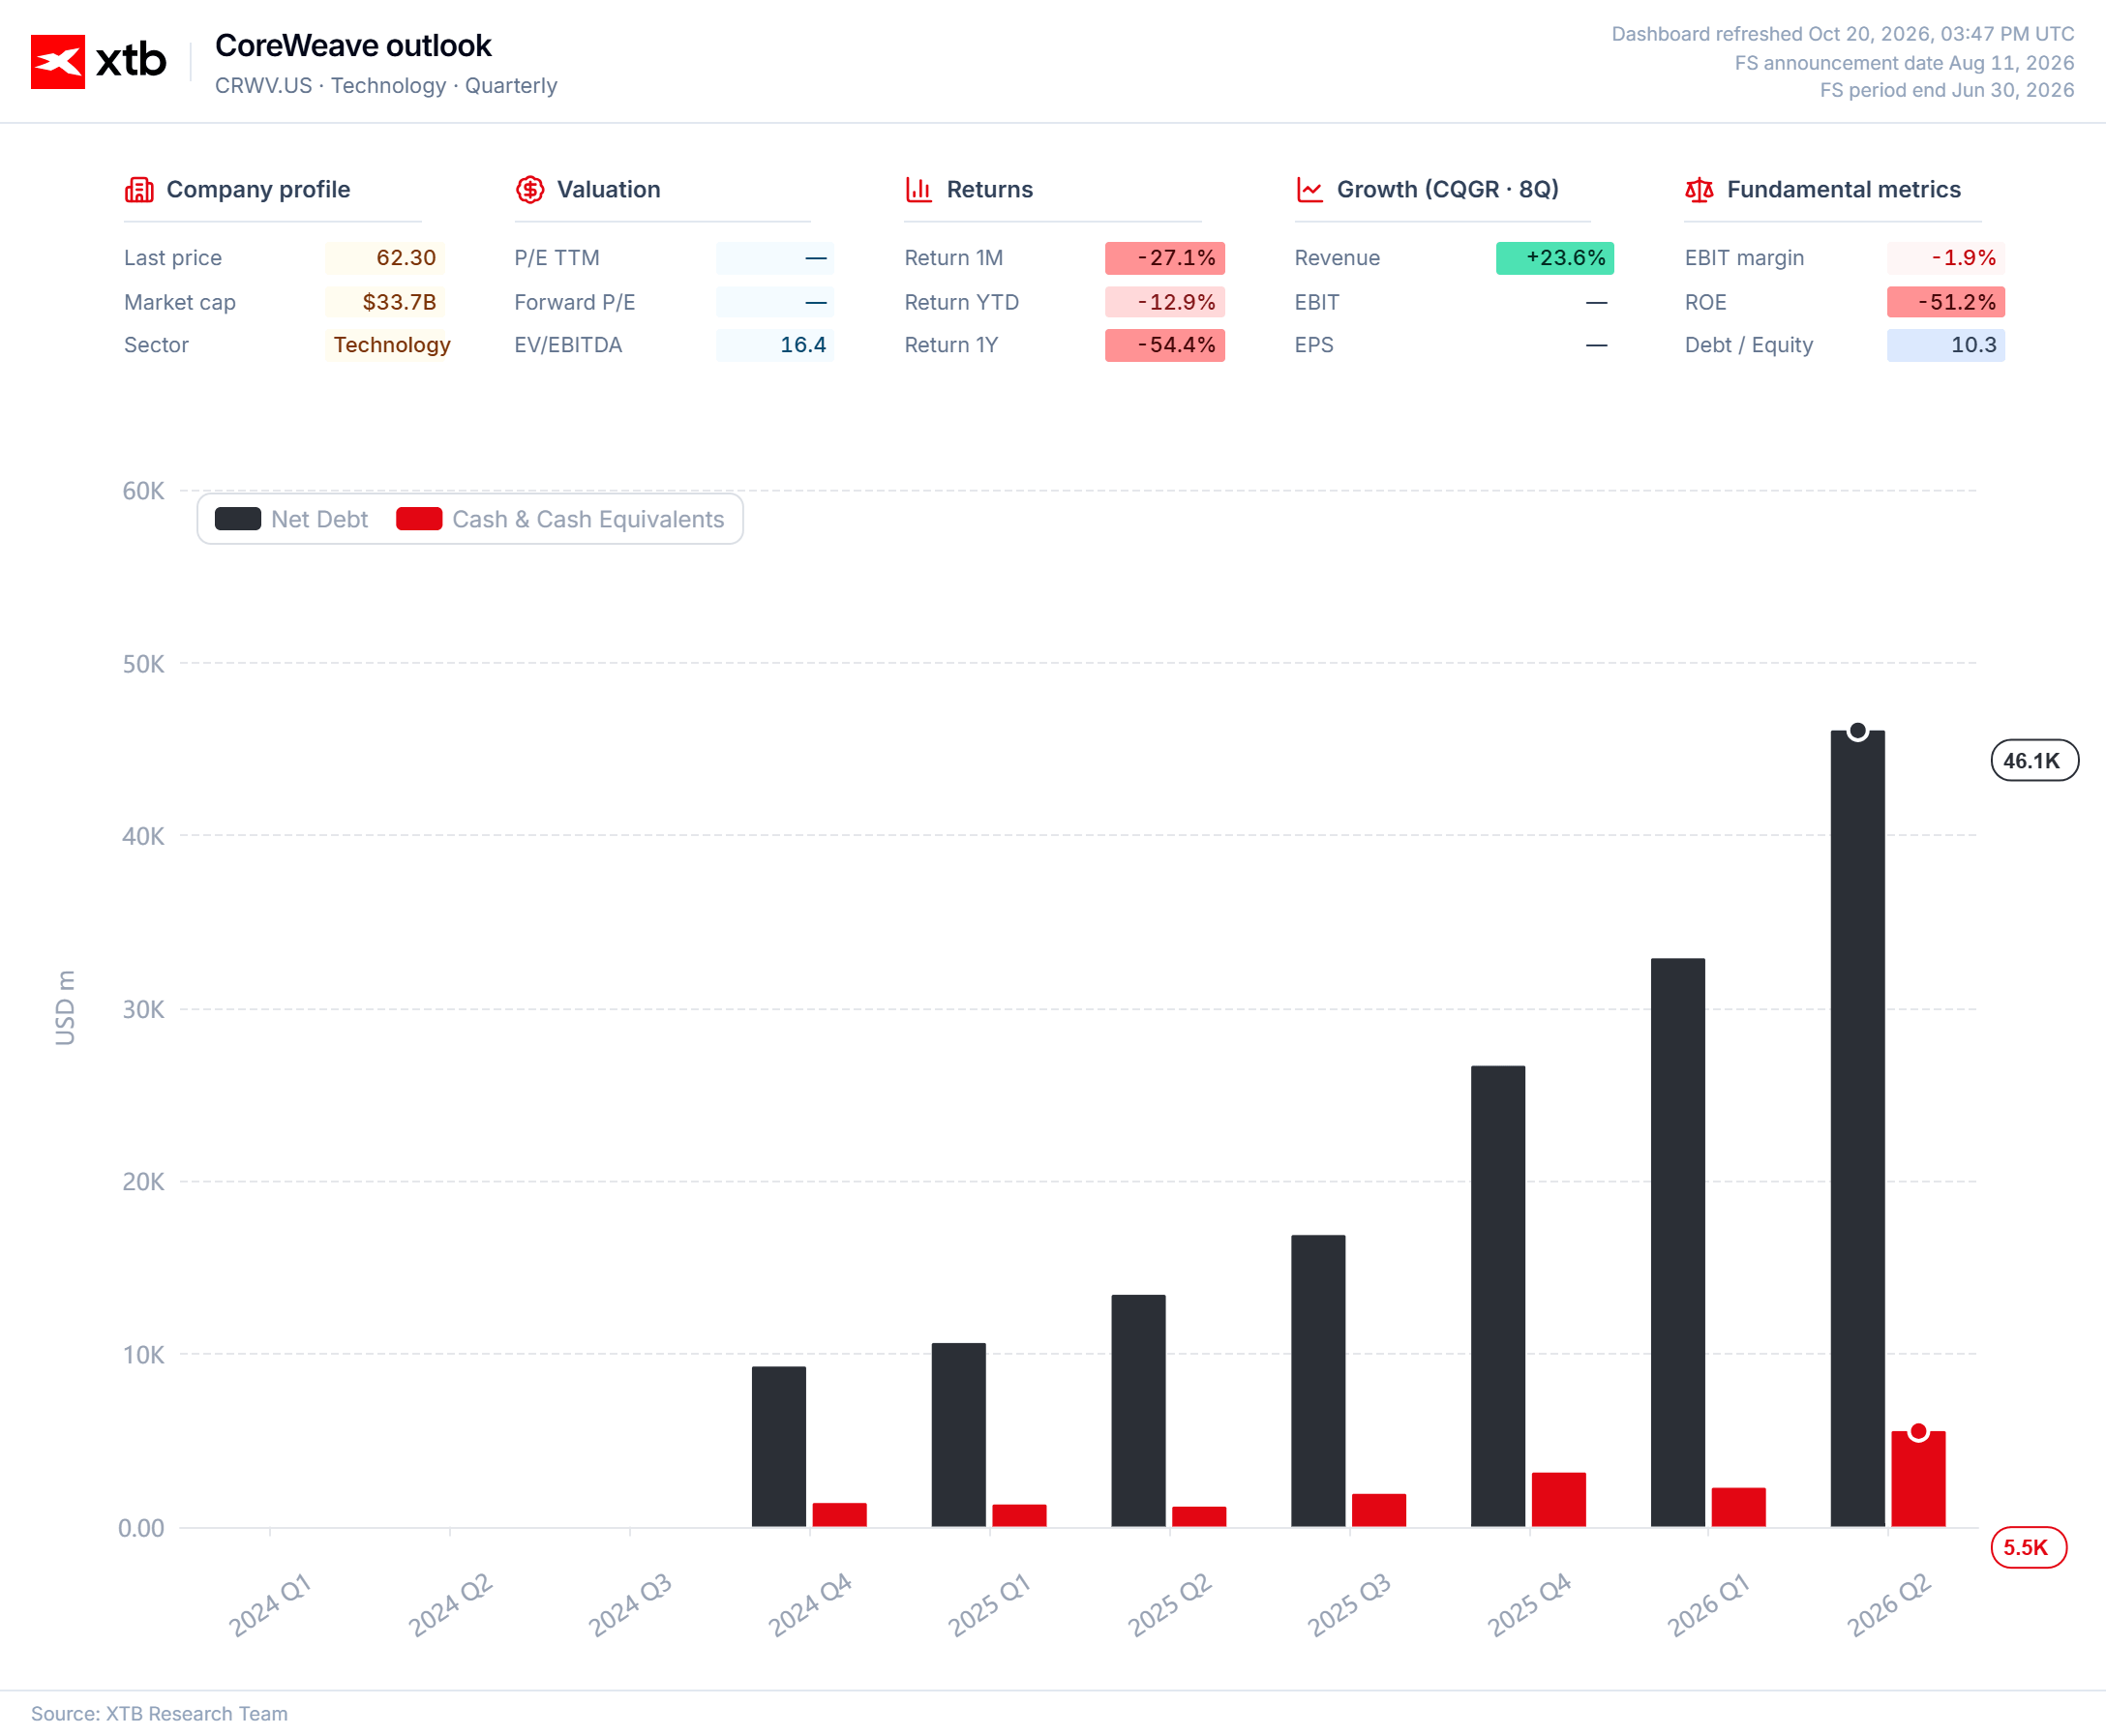
The gap between profits and the company’s ambitions is being financed by massive debt, even by industry standards. Planned capital expenditures for 2026 amount to USD 35 to 39 billion, almost three times projected revenue.
In the second quarter, interest expense reached USD 640 million versus USD 267 million a year earlier, and the net loss increased to USD 626 million. Despite an approximately 59% (adjusted) EBITDA margin, the company is still not net profitable.
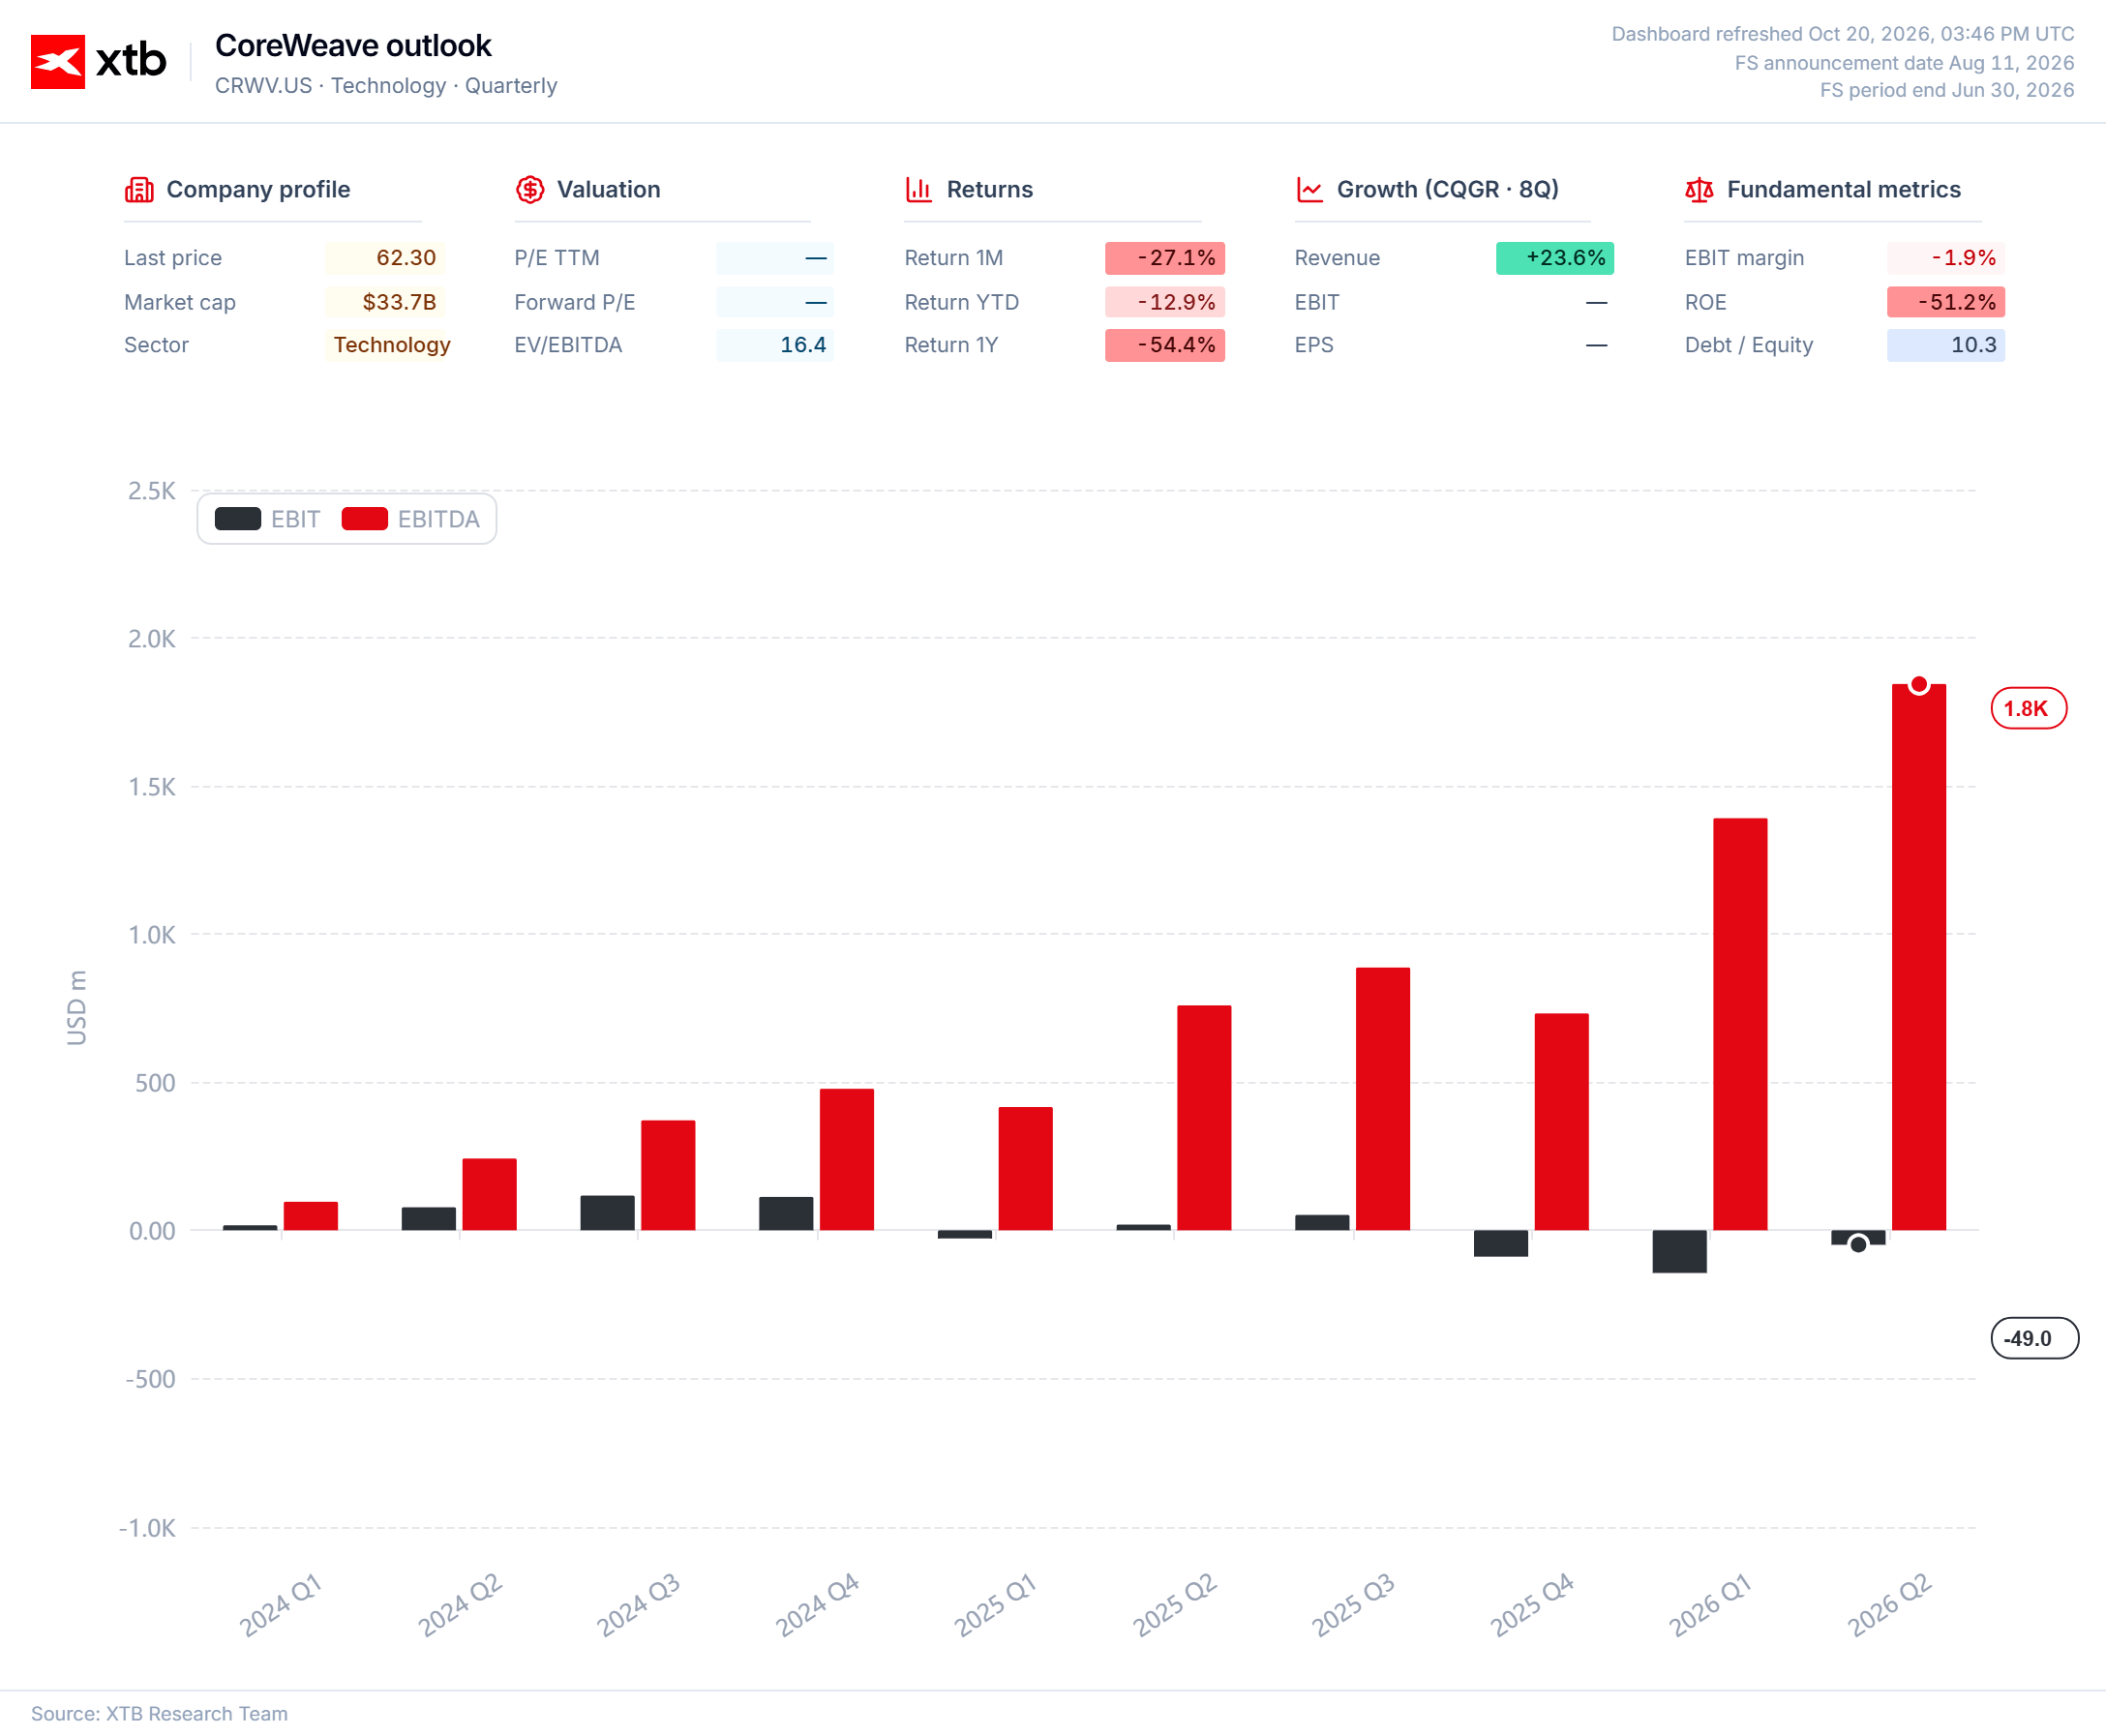
Importantly, as the name suggests, EBITDA does not include infrastructure depreciation or the cost of financing it. The company reports an enormous USD 2.5 billion in impairment charges. Also important, the company’s accounting policy assumes a 6 year useful life for assets, which seems misaligned with the breakneck pace of AI industry development.
The Burden of Debt
Financing is increasingly reflecting the company’s mounting challenges, and is becoming the biggest one. Yields on some bonds have risen to 16%, signaling serious creditor concerns.
In addition, despite growing semiconductor supply, shortages remain severe and long term. In the short term, this means cost pressure, and in the long term, pressure on margins due to rising competition.
CoreWeave’s situation is difficult, but not yet hopeless, and the company has room to improve operating efficiency.
New contracts signed in the second quarter offered contribution margins up to 10 percentage points higher than in previous quarters. Expanding AI model deployment services as well as software, data storage, and networking could increase the revenue generated from existing infrastructure.
Key factors here are the partnership with Nvidia and contracted access to power. If the company manages to reassure creditors while maintaining its current growth pace, the risk balance could shift dramatically in its favor. However, if component prices and availability remain this strained, the company may not be able to achieve the economies of scale necessary for the exponential growth assumed by the “neo cloud” business model.



Chart of the Day: US100 (Nasdaq 100). Rebound in AI trade vs. weakening technical picture



Macro Calendar - UK Labor Market, ZEW Sentiment, and Wall Street Giants' Reports


Chart of the Day: What’s next for tech stocks after the deepest sell-off since April 2025? (19.10.2026)


Economic Calendar: Big tech earnings week and test for the AI rally (19.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.