


Major US equity indices are trading in the green today. The tech-heavy Nasdaq 100 gained as much as 1.7%, while the S&P 500 rose 1.1%. The Dow Jones lagged behind, yet still enjoyed a solid session, up 0.6%.
Figure 1: Winners and Losers in the Nasdaq 100 (17.09.2026)
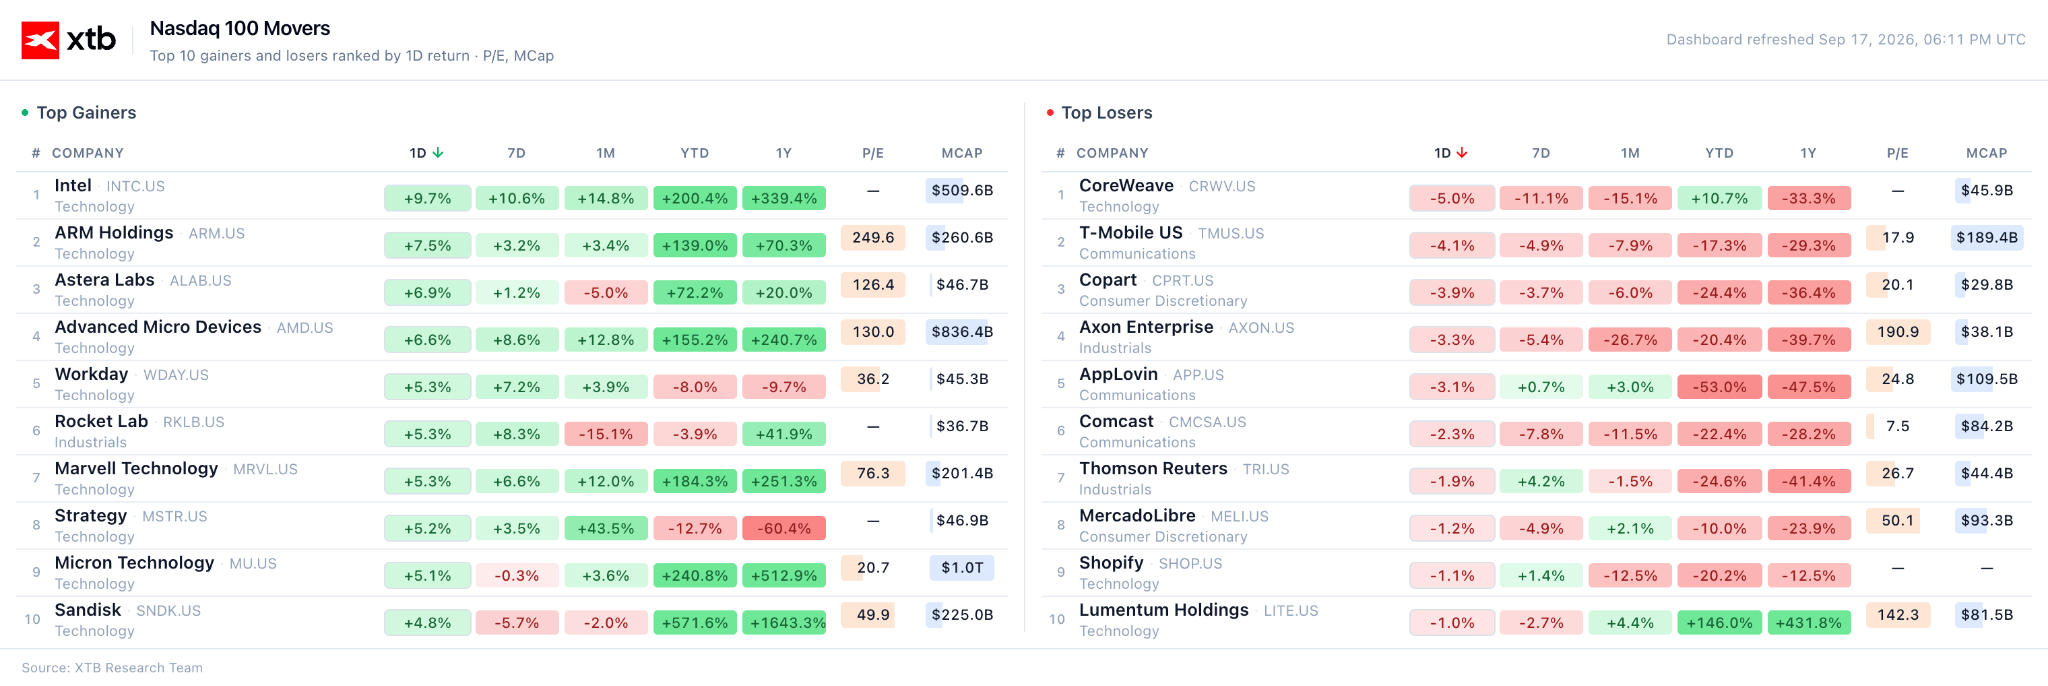 Source: XTB Research, 17.09.2026
At least two key factors can be attributed to today's rally.
Monetary Policy and Macroeconomic Data
It is worth beginning with yesterday’s Federal Reserve meeting. In line with expectations, interest rates were raised by 25 bps. As the decision was almost fully priced in, market focus shifted primarily to the accompanying commentary.
Crucially, the decision was unanimous, with Kevin Warsh sending a clear signal that elevated inflation necessitates a restrictive stance, which the robust condition of the US economy can well accommodate. He noted that summer readings offer no grounds to suggest the underlying inflationary trend has materially improved.
The dot plot, representing committee members' anonymous interest rate projections, points to one more rate hike this year. Warsh once again opted out of participating in the projections.
Bond Market
US 10-year Treasury yields initially rose by nearly 1.5%. Today, however, we witnessed a sharp drop back to pre-decision levels (around 1.95% for 10-year bonds).
Figure 2: US 10-Year Government Bond Yields (06.2026 - 09.2026)
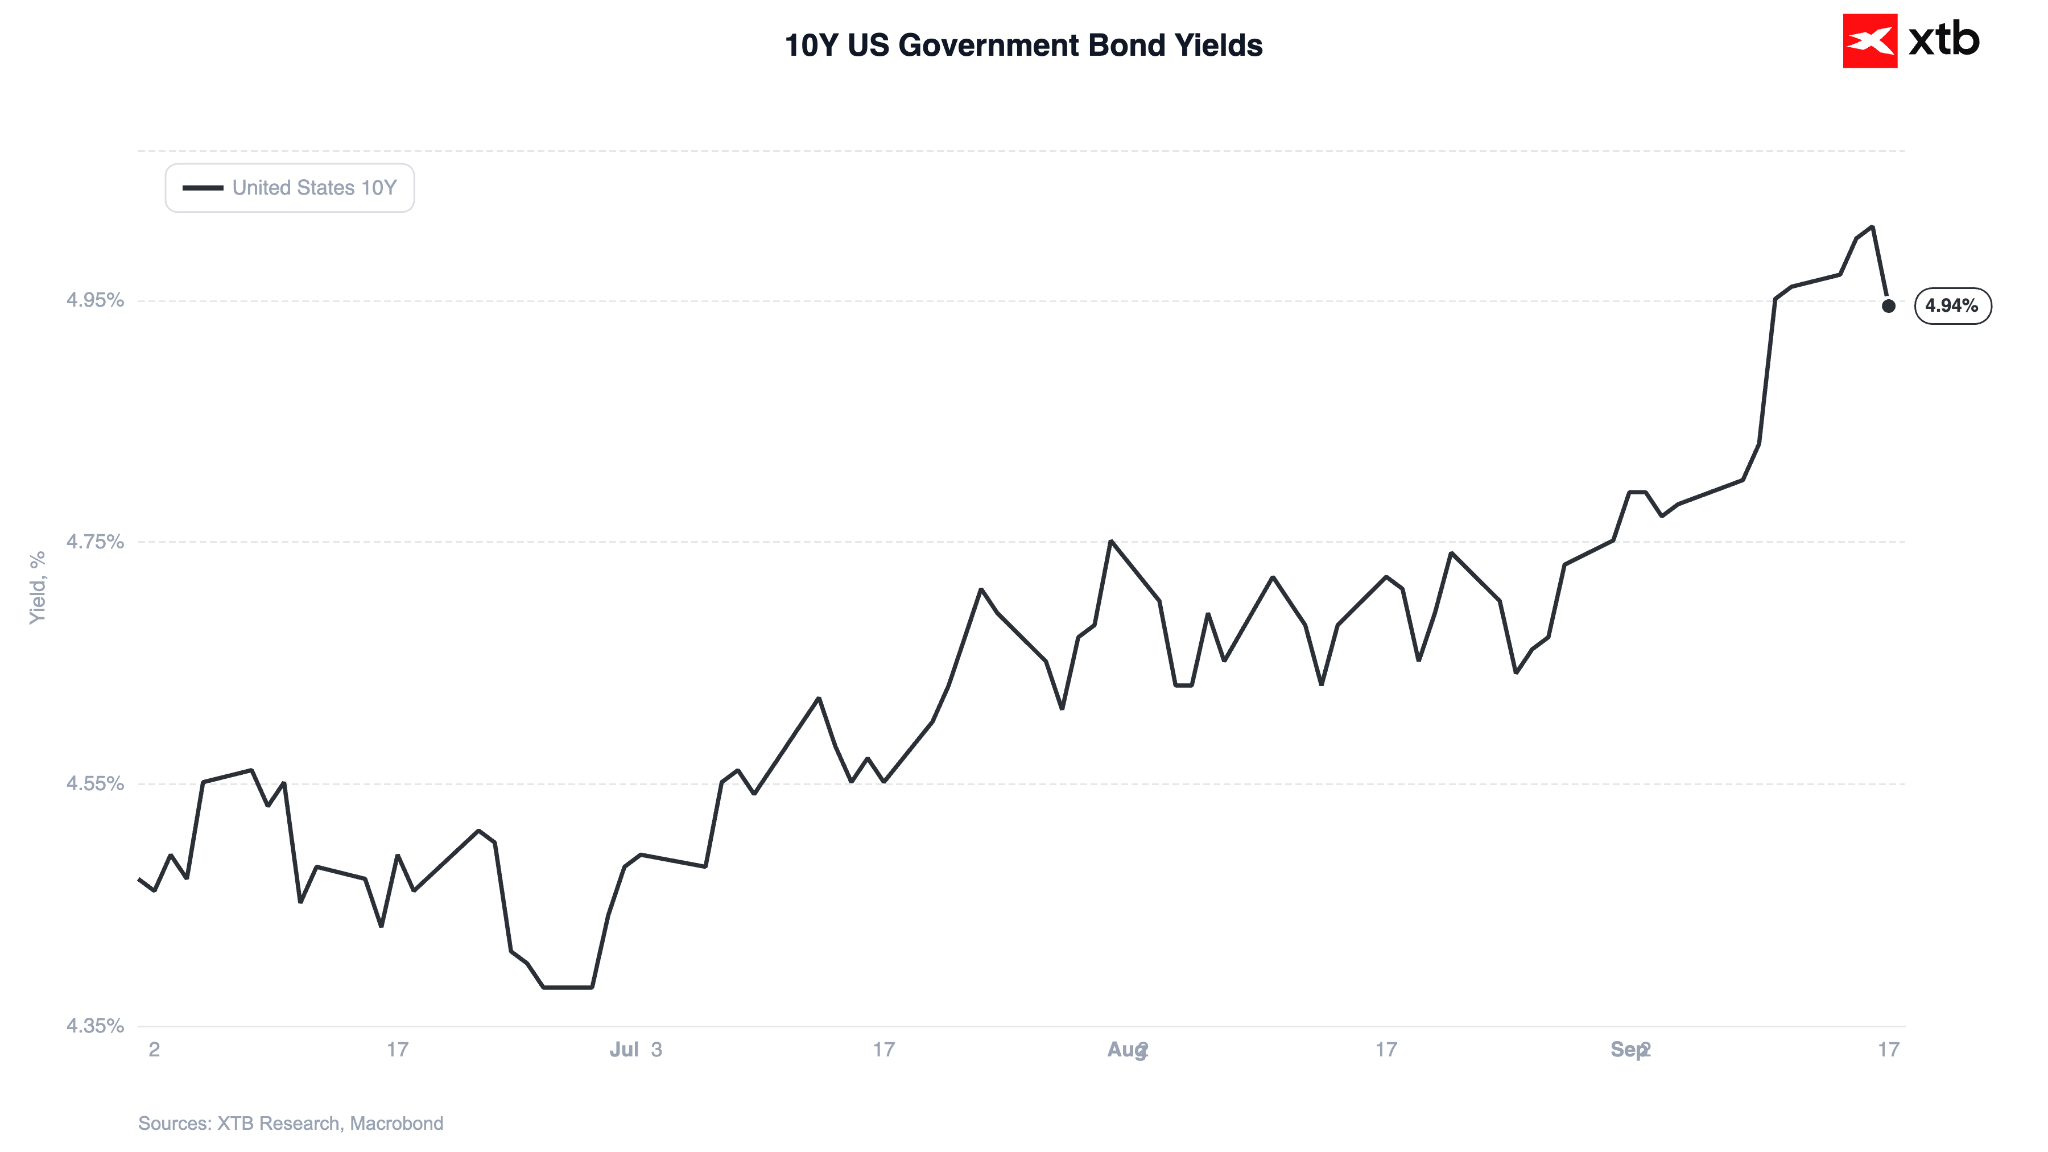 Source: XTB Research, 17.09.2026
The primary driver behind this move appears to be the sharp decline in crude oil prices. Around 2:00 PM, Brent crude was trading below $102 per barrel. Prices have since recovered towards higher levels around $105.
Figure 3: Brent and WTI Crude Oil (2026)
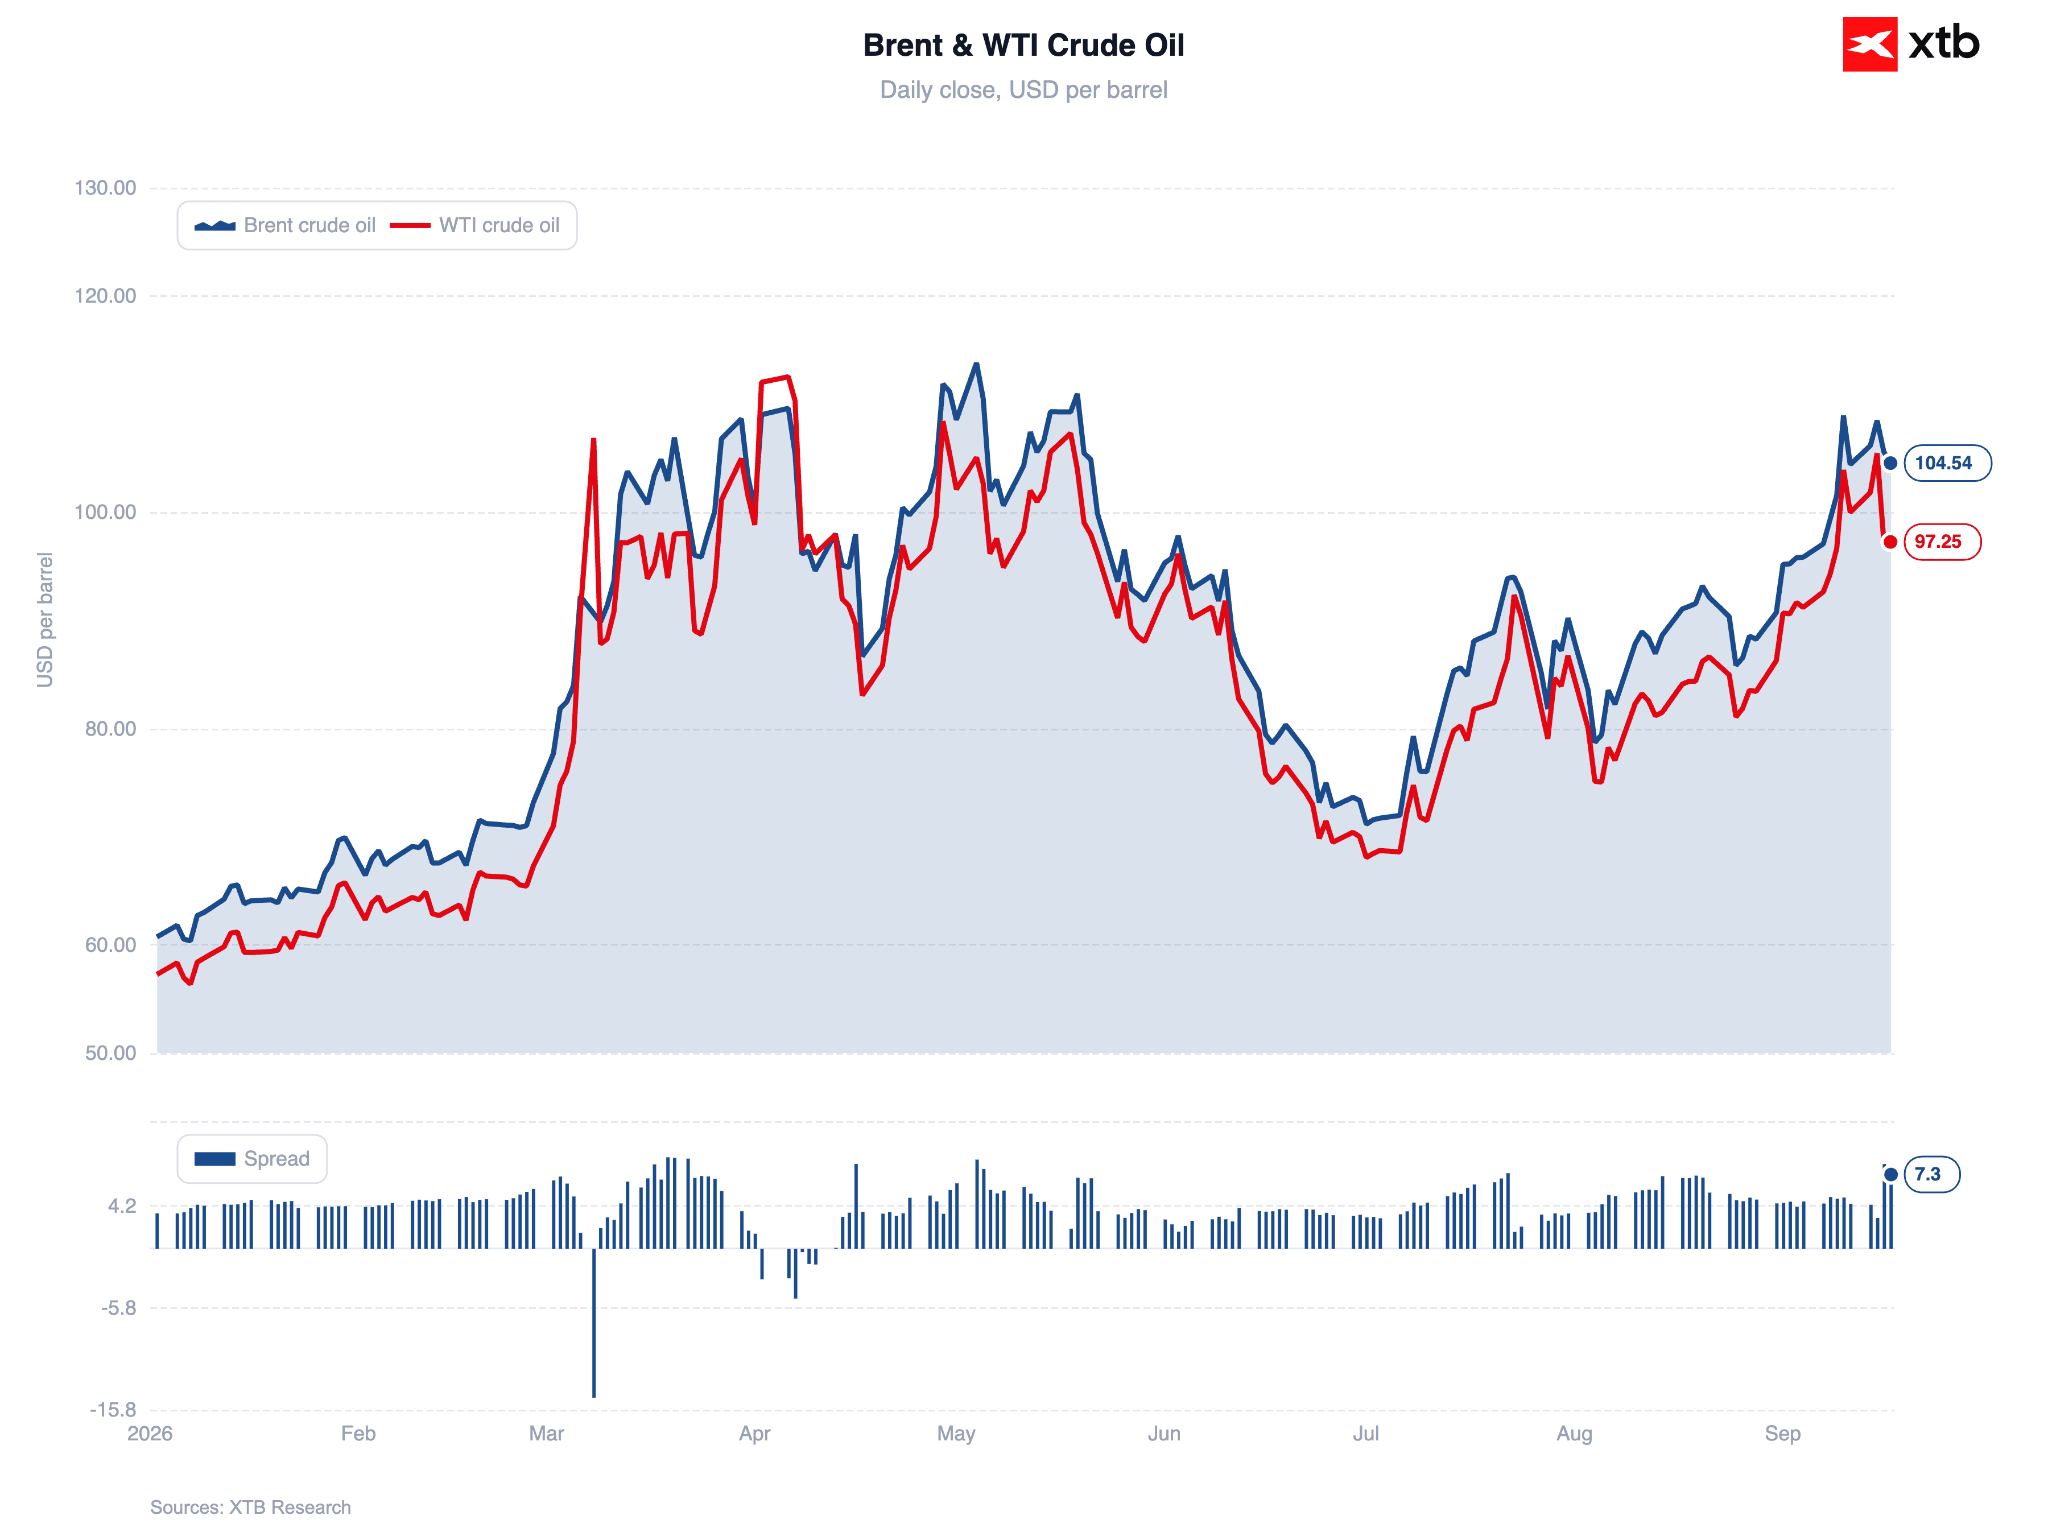 Source: XTB Research, 17.09.2026
The pullback in the bond market is notably softer. It appears that, equal to the drop in energy commodities, easing fears regarding the Fed's independence were crucial. A loss of independence would risk unanchoring inflation expectations (and necessitate far more aggressive tightening in the future). From this perspective, a rate hike may represent the "lesser of two evils" for investors.
Energy Commodities
Energy commodity prices are being supported, among other things, by the re-routing of a portion of Saudi crude oil exports towards ports in Oman following damage to the East-West pipeline. Investors also welcomed assurances from US officials that the damaged pipeline is expected to resume operations within the next few days.
Stock Market
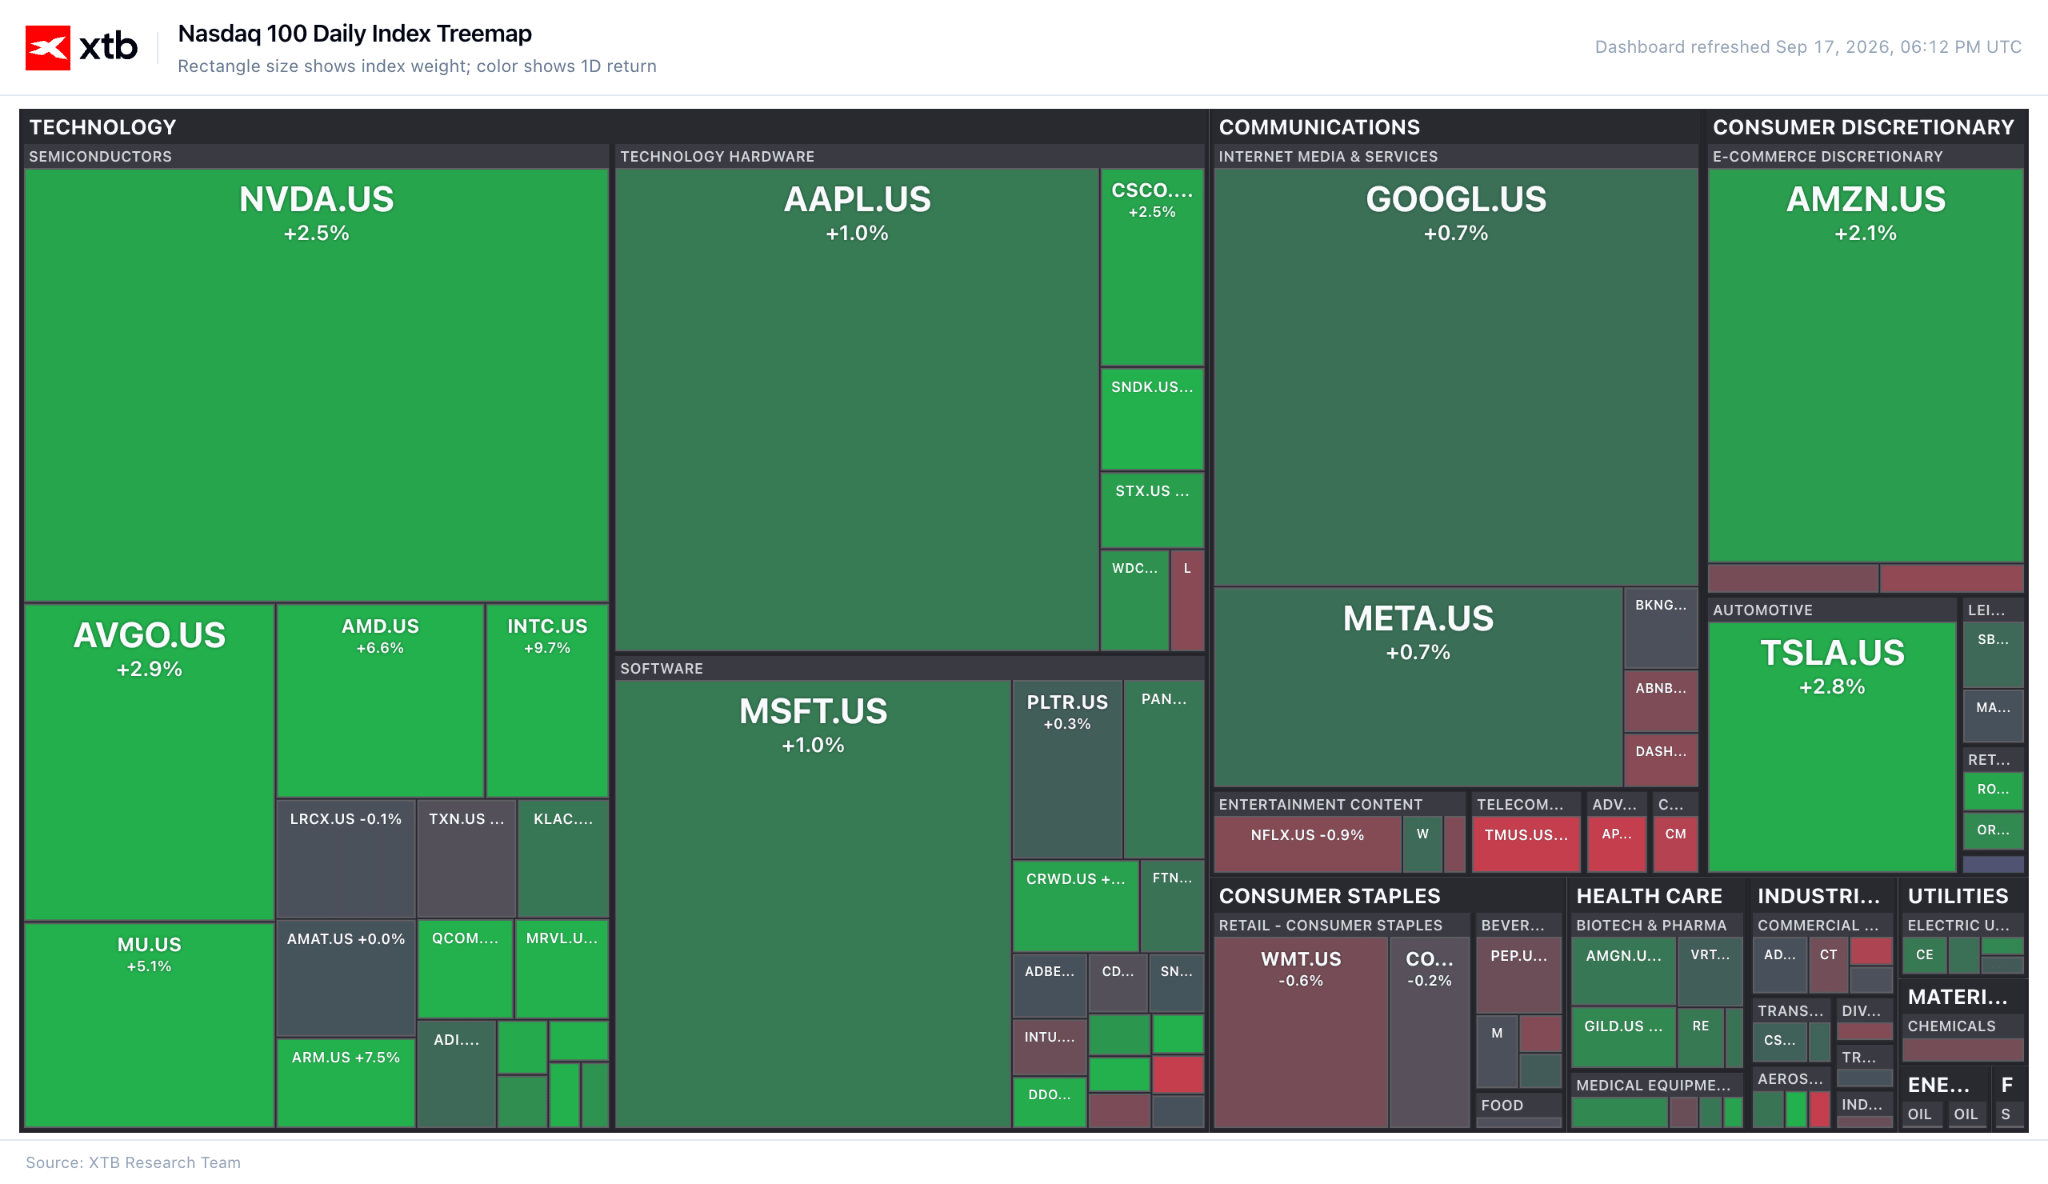
Semiconductor stocks lead today’s gains, being the most sensitive to bond yields due to DCF valuation models where 10-year US Treasuries typically serve as the discount rate. The popular SOXX index is up by a strong 3.5%.
Figure 4: Treemap for the Nasdaq 100 (17.09.2026)
 Source: XTB Research, 17.09.2026
Against the backdrop of market events, an AI risk summit convened by King Charles III took place in Scotland, attended by Jensen Huang (Nvidia), Demis Hassabis (Google DeepMind), Sarah Friar (OpenAI), and Tino Cuellar (Anthropic), among others. Huang urged AI development companies to rigorously test their systems and pause the deployment of products that are not sufficiently safe.
The meeting came amidst a broad debate sparked by a weekend essay from Anthropic CEO Dario Amodei, calling for a slowdown in the development of the most advanced AI models - a proposal endorsed by OpenAI CEO Sam Altman. At the time, Huang spoke against additional sector regulation.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



Nasdaq 100 Up 1.7%


US Open: Nasdaq, gold and silver surge following... an interest rate hike (17.09.2026)


🇬🇧 Will the pound recover after the BoE?



📊Daily Summary - Hawkish Fed raises rates and signals more. Dollar gains while gold falls
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.