

- US headline inflation accelerated to 3.7% YoY in September, exceeding market forecasts.
- Markets repriced Fed expectations, lifting the implied probability of an interest rate hike to nearly 50%.
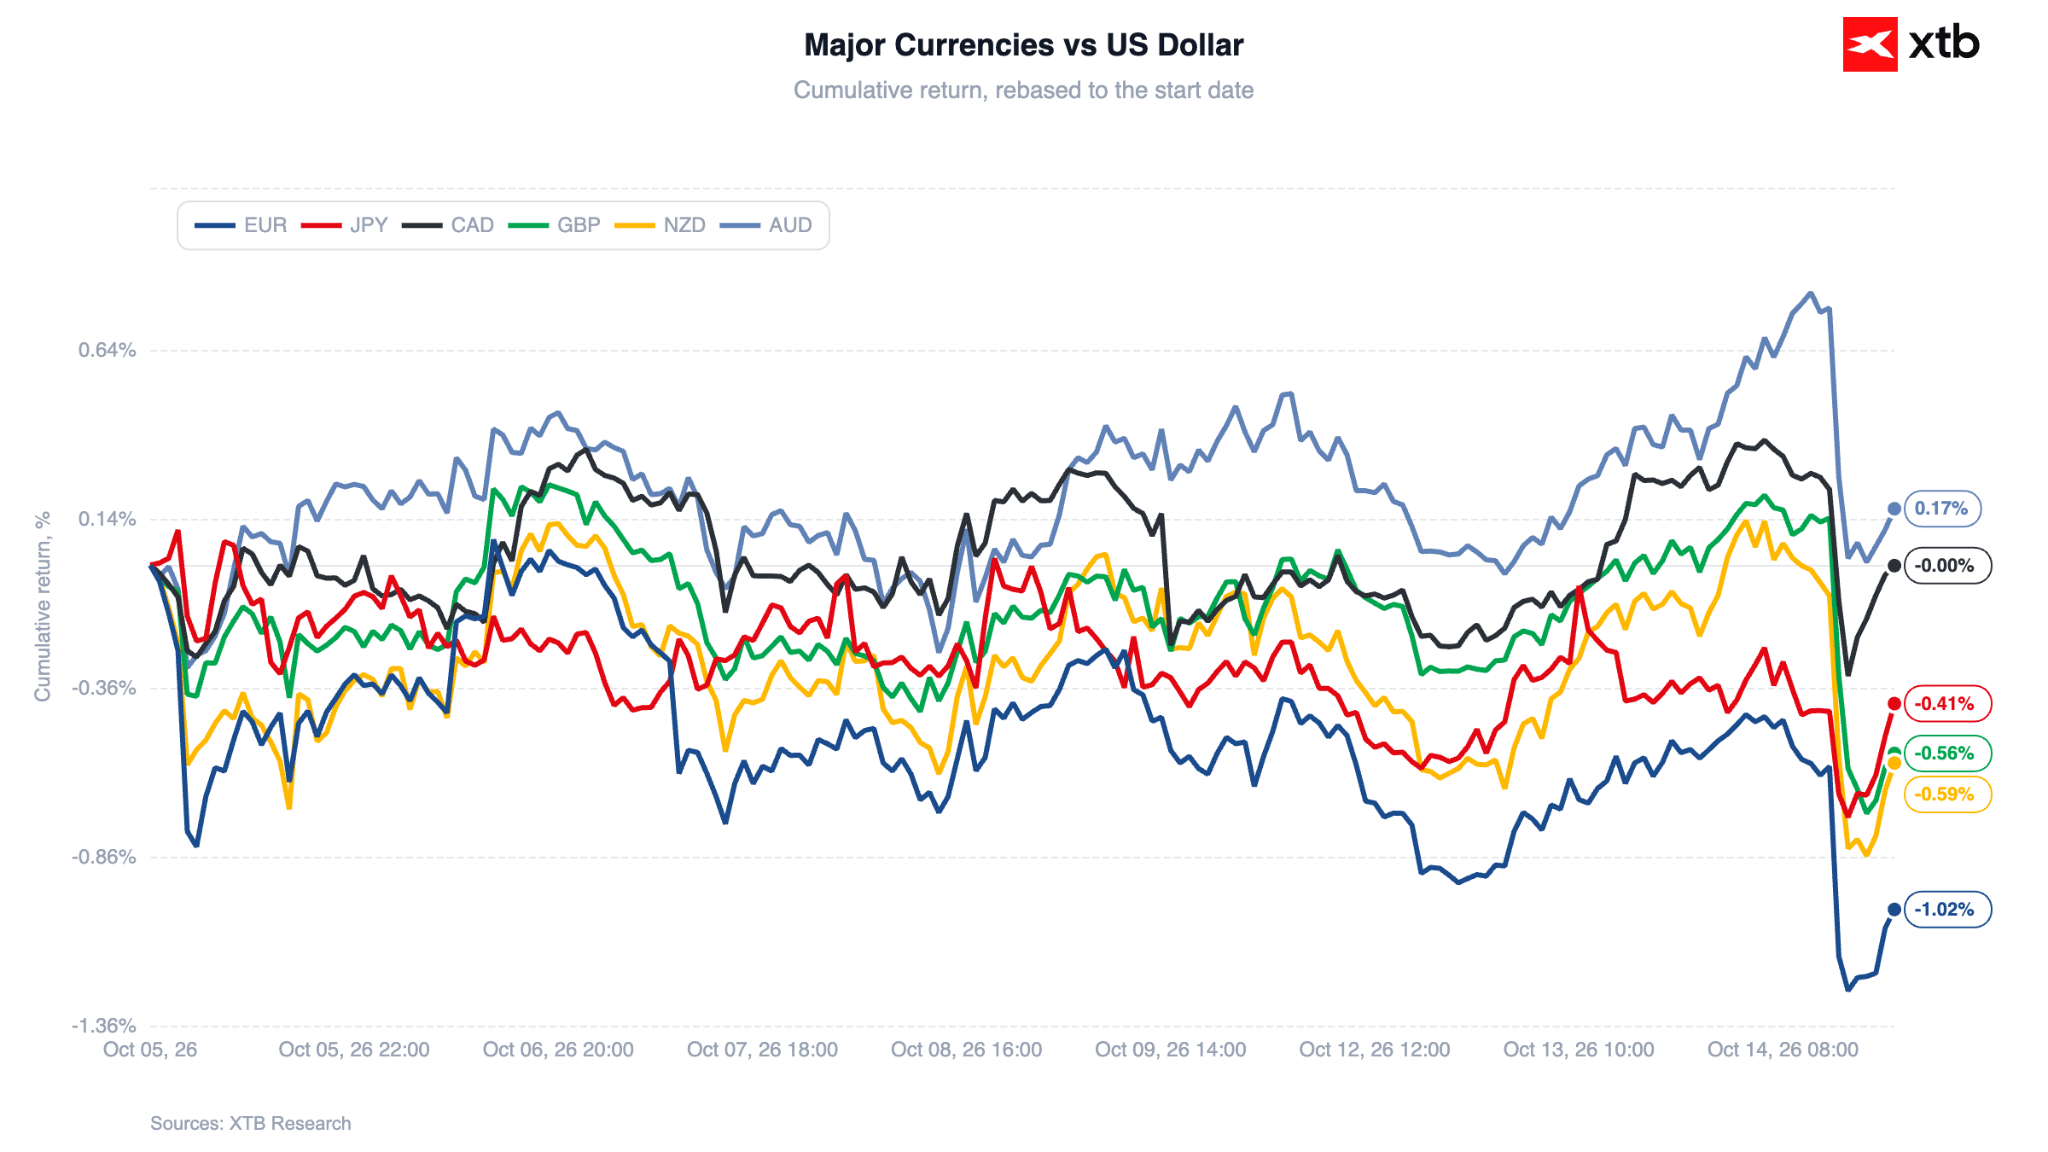
- The US dollar strengthened broadly, pushing EUR/USD lower toward 1.11.
- Geopolitical conflict escalation in Saudi Arabia supported crude oil prices.
- US equity indices declined sharply, led by semiconductor stocks and technology shares.
Wednesday's US consumer price inflation reading came in higher than market consensus, prompting an immediate surge in Treasury yields, a rally in the US dollar to its highest level since May 2025, and a broad sell-off across global equity and precious metals markets.
Concurrently, investors monitored the further escalation of the conflict in Saudi Arabia. Missile and drone strikes by Houthi forces hit Saudi Aramco's headquarters and disrupted operations at the country's principal airport, which, alongside additional maritime incidents in the Strait of Hormuz, provided upward support for crude oil prices.
Macroeconomic data
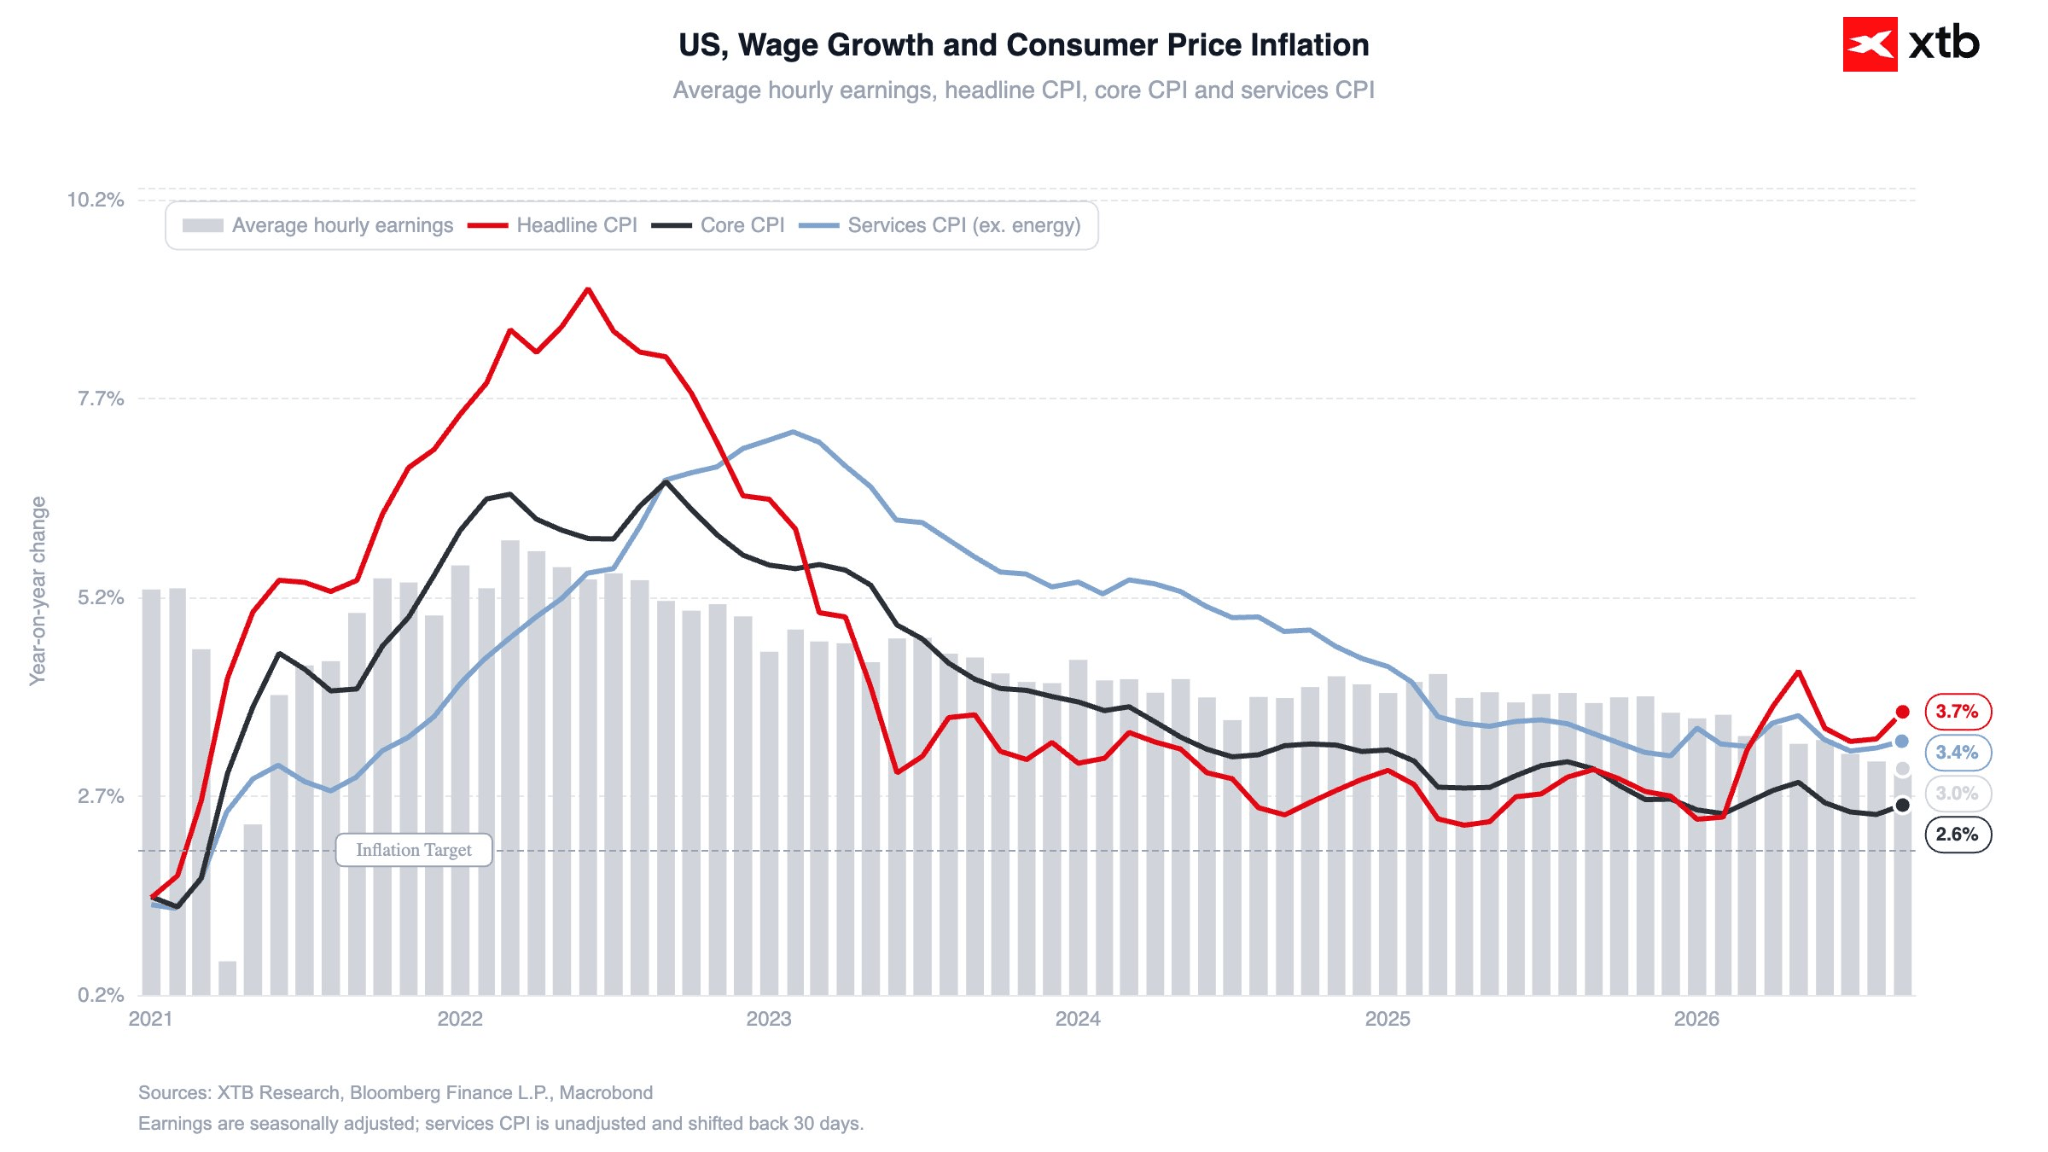
Today's CPI report printed above consensus estimates. Headline inflation accelerated to 3.7% YoY (up from 3.4% in August), exceeding the forecasted 3.6%. Core inflation (excluding food and energy) rose to 2.6% YoY against expectations of 2.5%. Inflation has now remained above the Federal Reserve's target for 66 consecutive months, with little indication of a prompt return to target.
Figure 1: US CPI inflation and wage growth (2021 - 2026)
 Source: XTB Research, 14.10.2026
Prices are increasing at their fastest pace in five months. The primary driver of this increase was energy costs, particularly fuel (+9.1% MoM and 34% YoY). Upward pressure is also evident across other sectors: computer and component costs advanced 9.7% YoY, driven by the data centre construction boom and shortages in semiconductor memory.
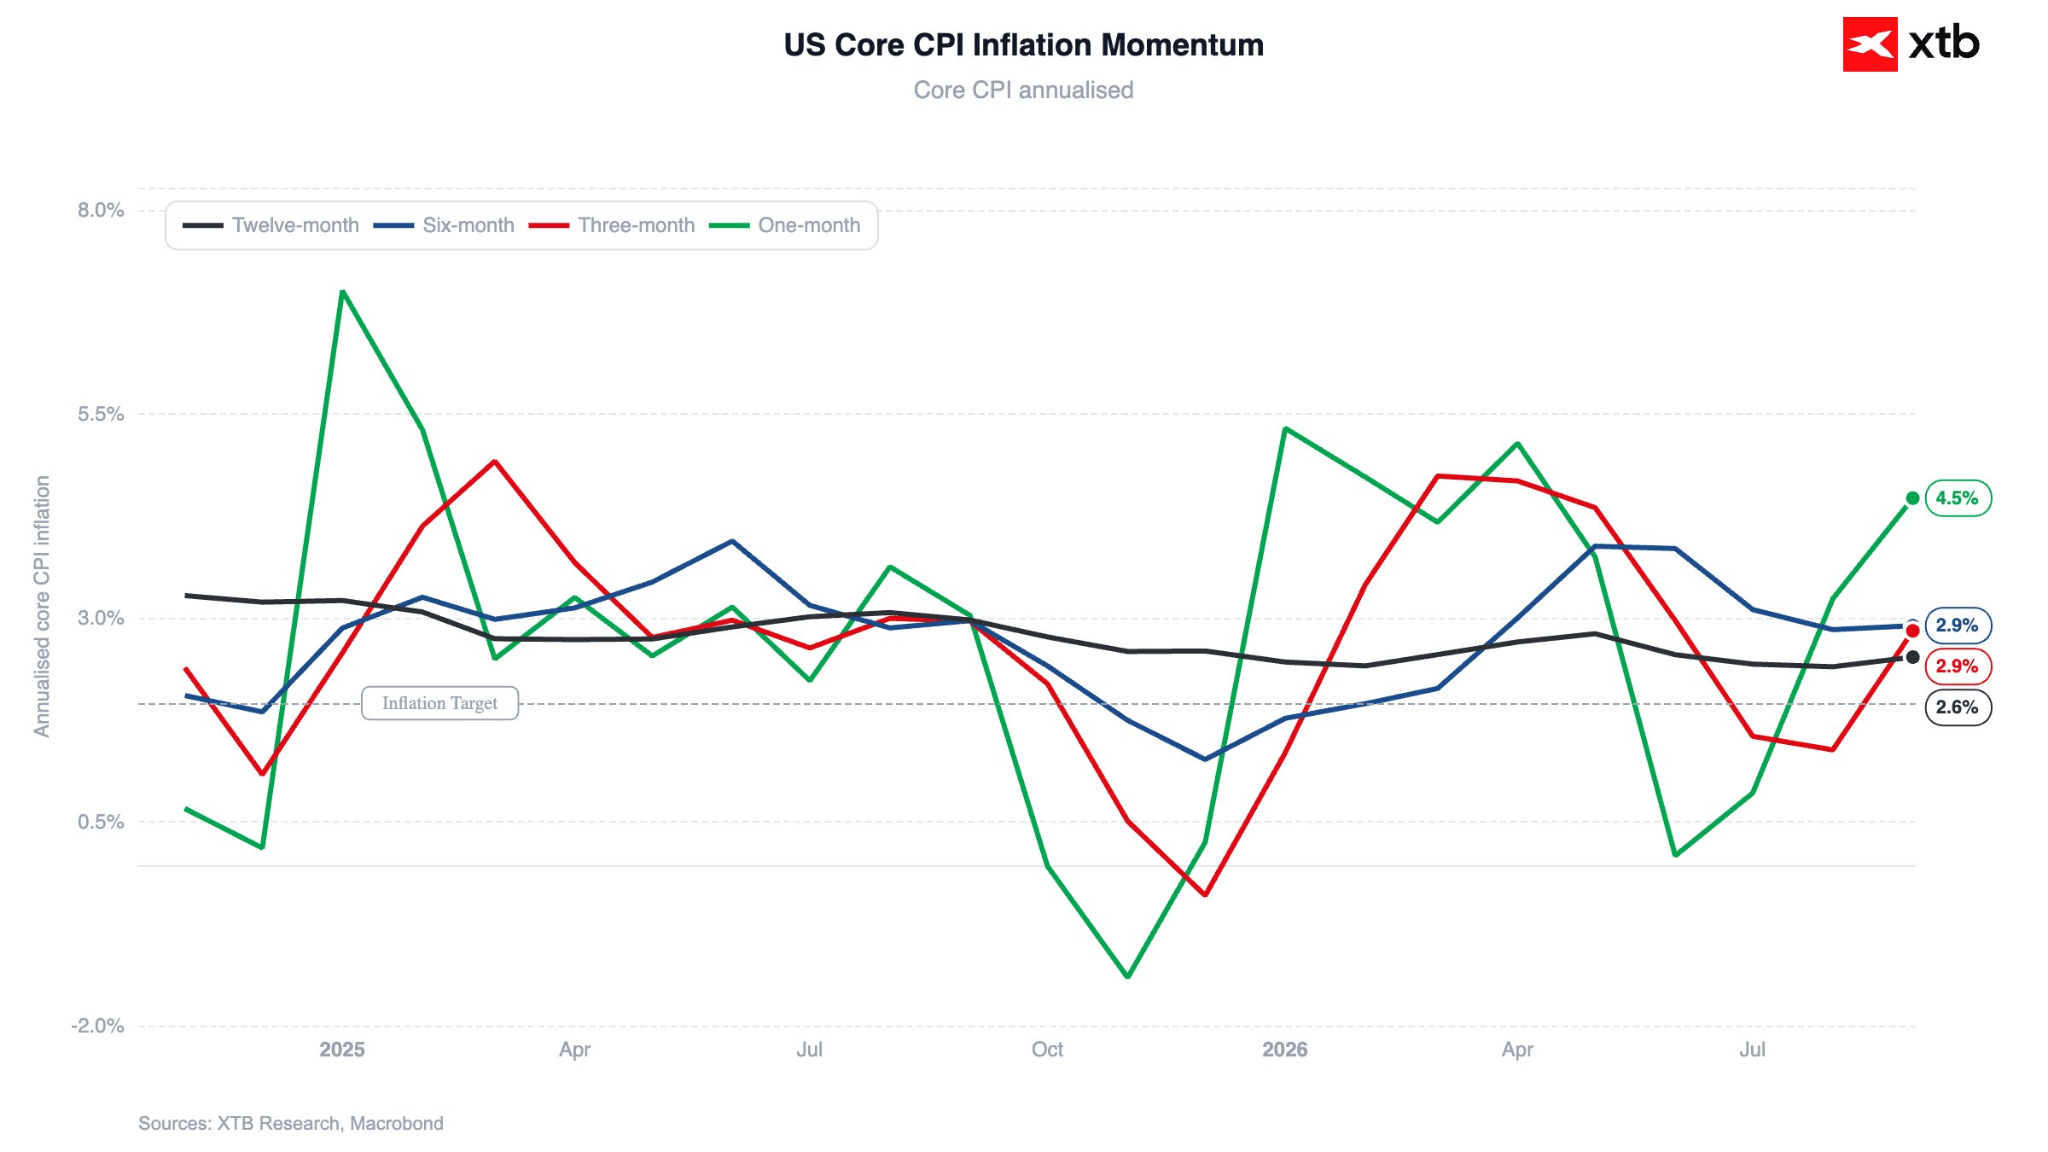
On a monthly basis, headline CPI increased by 0.6% (the steepest monthly gain in five months), while the core measure rose by 0.3%. Consequently, 3-month annualized core inflation momentum has re-accelerated above the Fed's target.
Figure 2: US core CPI inflation momentum (14.10.2026)
 Source: XTB Research, 14.10.2026
The breadth of inflationary pressures is also widening. In September, more than 52% of basket components recorded annualised price growth exceeding 3%, with 35% advancing at a rate above 4%.
However, it is notable that a substantial proportion of the core increase was attributable to a single component – Owner's Equivalent Rent (OER). Given the relative stability observed in the housing market over preceding months, questions remain regarding whether this spike represents a temporary anomaly.
Fixed income market
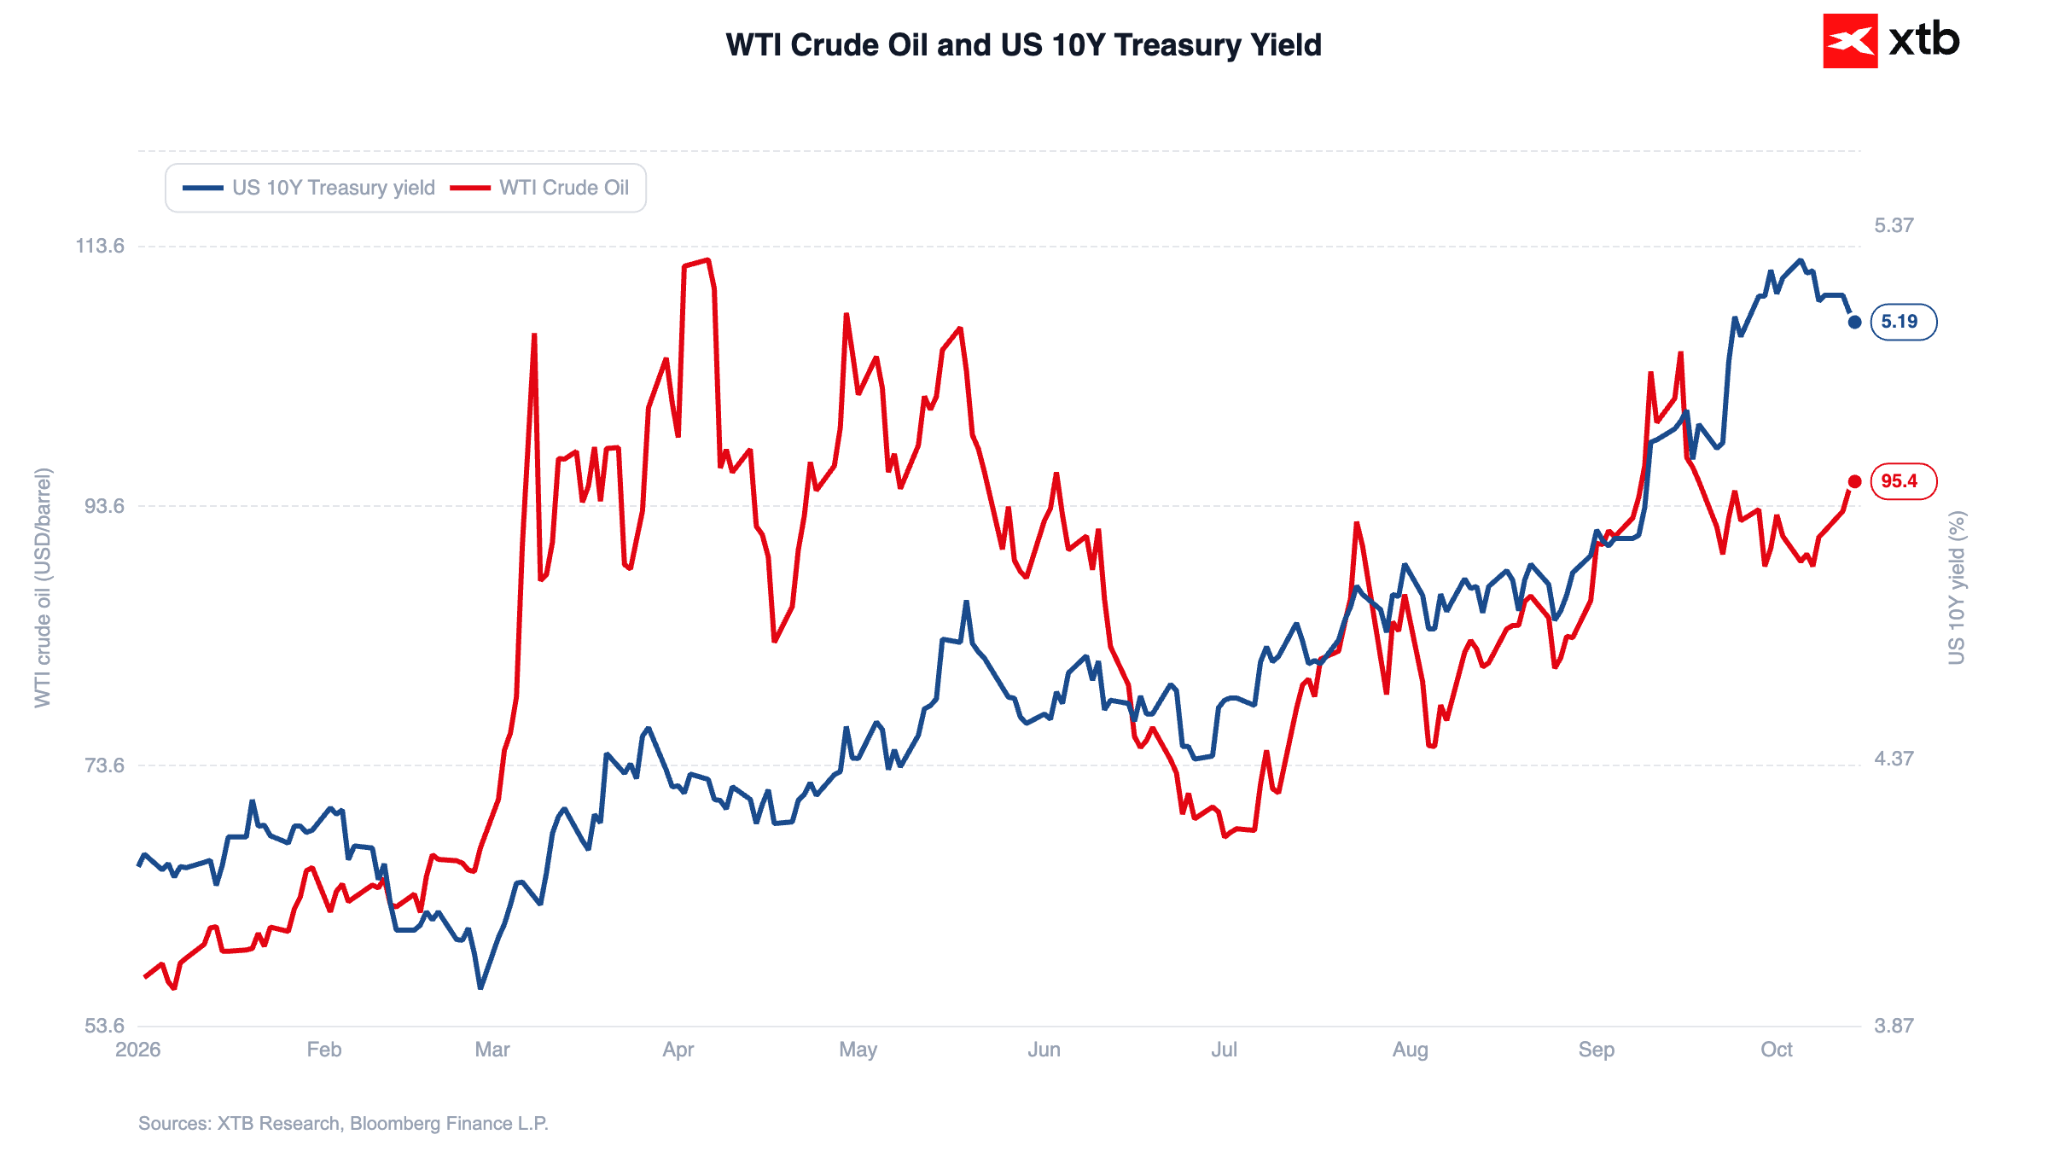
US Treasury yields spiked sharply following the release, although the movement was relatively short-lived. Benchmark 10-year yields briefly touched 5.33% before retreating to trade around 5.20%. Two-year Treasury yields, which are particularly sensitive to monetary policy expectations, briefly reached 4.95% before settling near 4.83%.
Figure 3: US 10-year Treasury yields and WTI crude oil (06.2026 - 10.2026)
 Source: XTB Research, 14.10.2026
Monetary policy and foreign exchange
Money markets swiftly repriced the anticipated trajectory of Fed interest rate decisions. Market-implied odds of an interest rate increase at the October meeting rose from approximately 20% yesterday to nearly 50%. This shift underpinned broader US dollar strength, with the greenback advancing against all G10 peers as EUR/USD approached 1.11.
Figure 4: Major currencies vs US dollar (05.10.2026 - 14.10.2026)
 Source: XTB Research, 14.10.2026
Equity markets
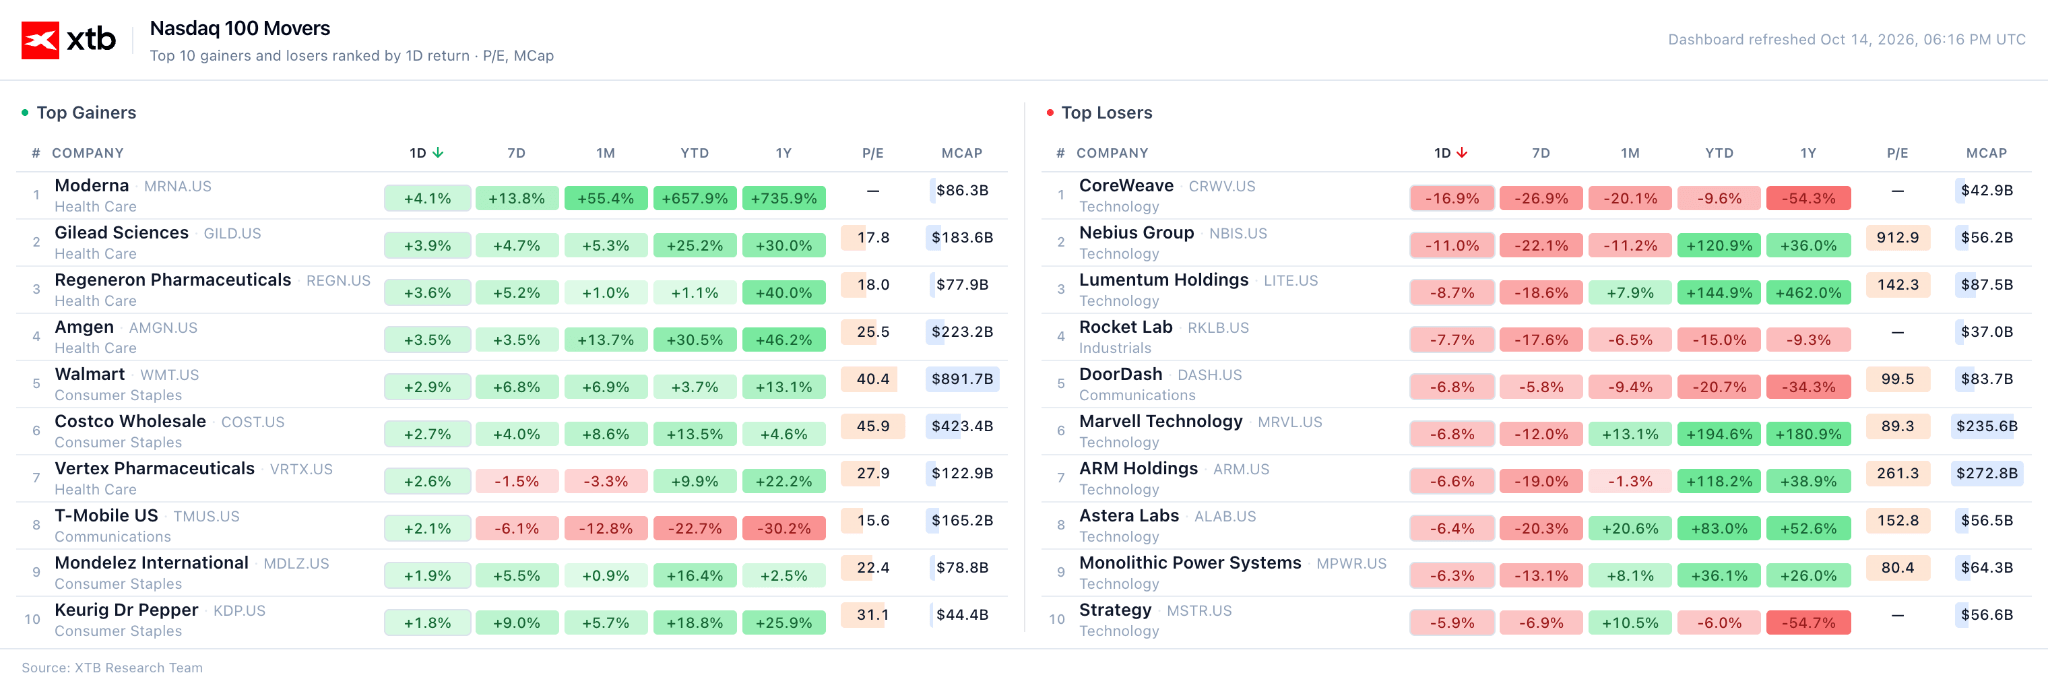
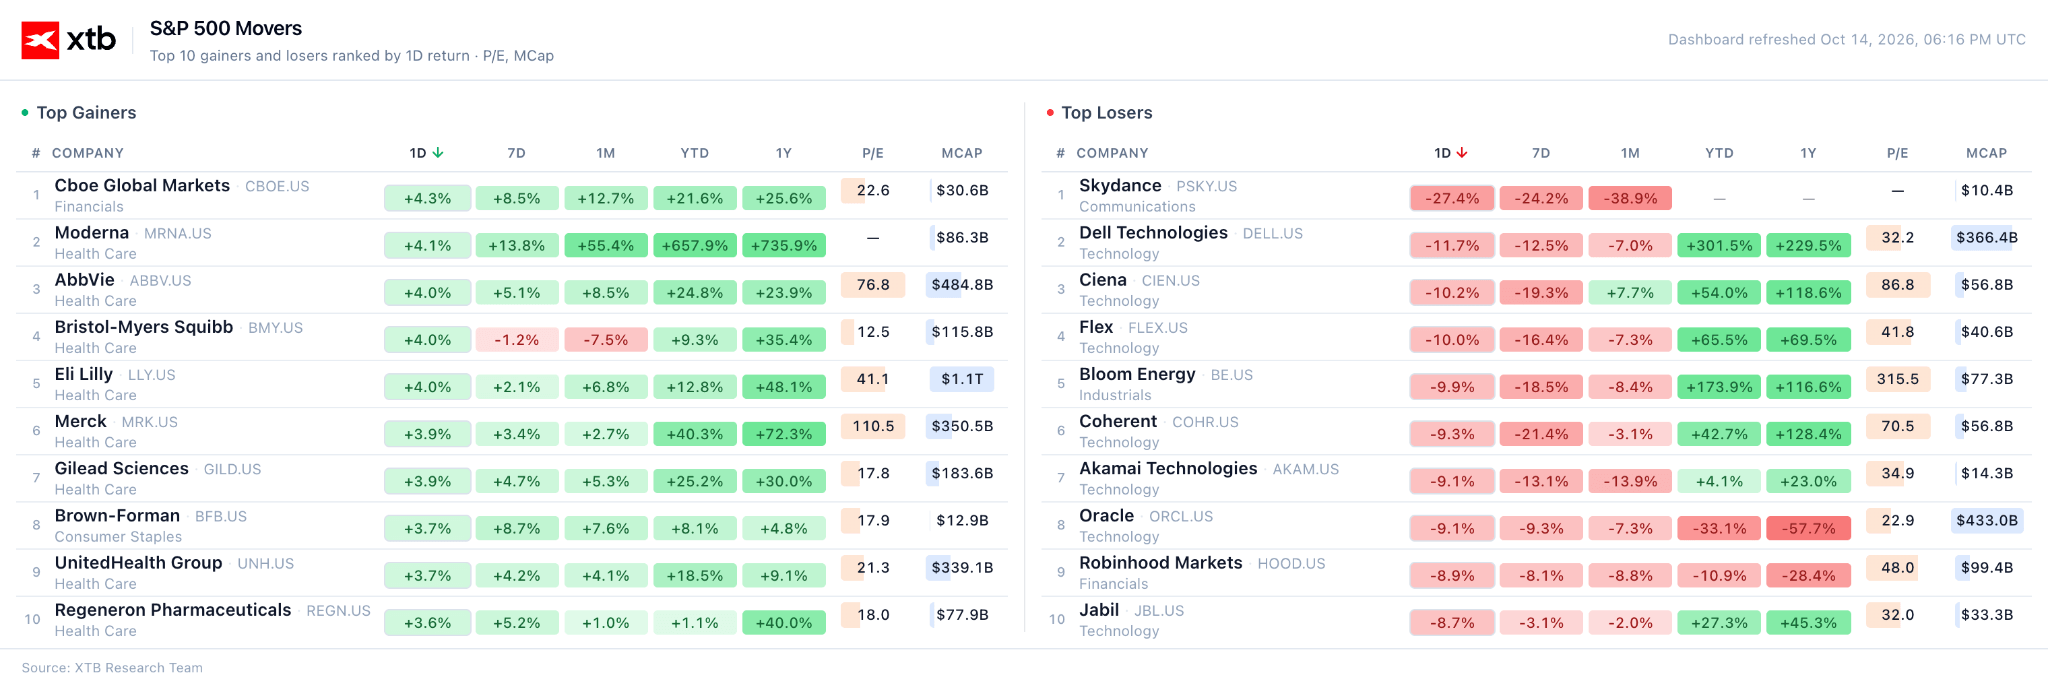
US equity indices are under noticeable pressure. The Dow Jones Industrial Average is down 0.5%, the S&P 500 has dropped 1.3%, while the tech-heavy Nasdaq 100 has fallen 2.1%.
Semiconductor stocks are suffering the steepest losses. The iShares Semiconductor ETF (SOXX), which has faced headwinds in recent sessions, is trading down nearly 4.5%.
Figure 5: Gainers and losers in the Nasdaq 100 (14.10.2026)
 Source: XTB Research, 14.10.2026
Market participants are increasingly questioning the sustainability of the artificial intelligence capital expenditure cycle, citing rising corporate leverage, elevated interest rates, stretched valuations, and intensifying competition (including from China's CXMT).
Figure 6: Gainers and losers in the S&P 500 (14.10.2026)
 Source: XTB Research, 14.10.2026
Precious metals under pressure
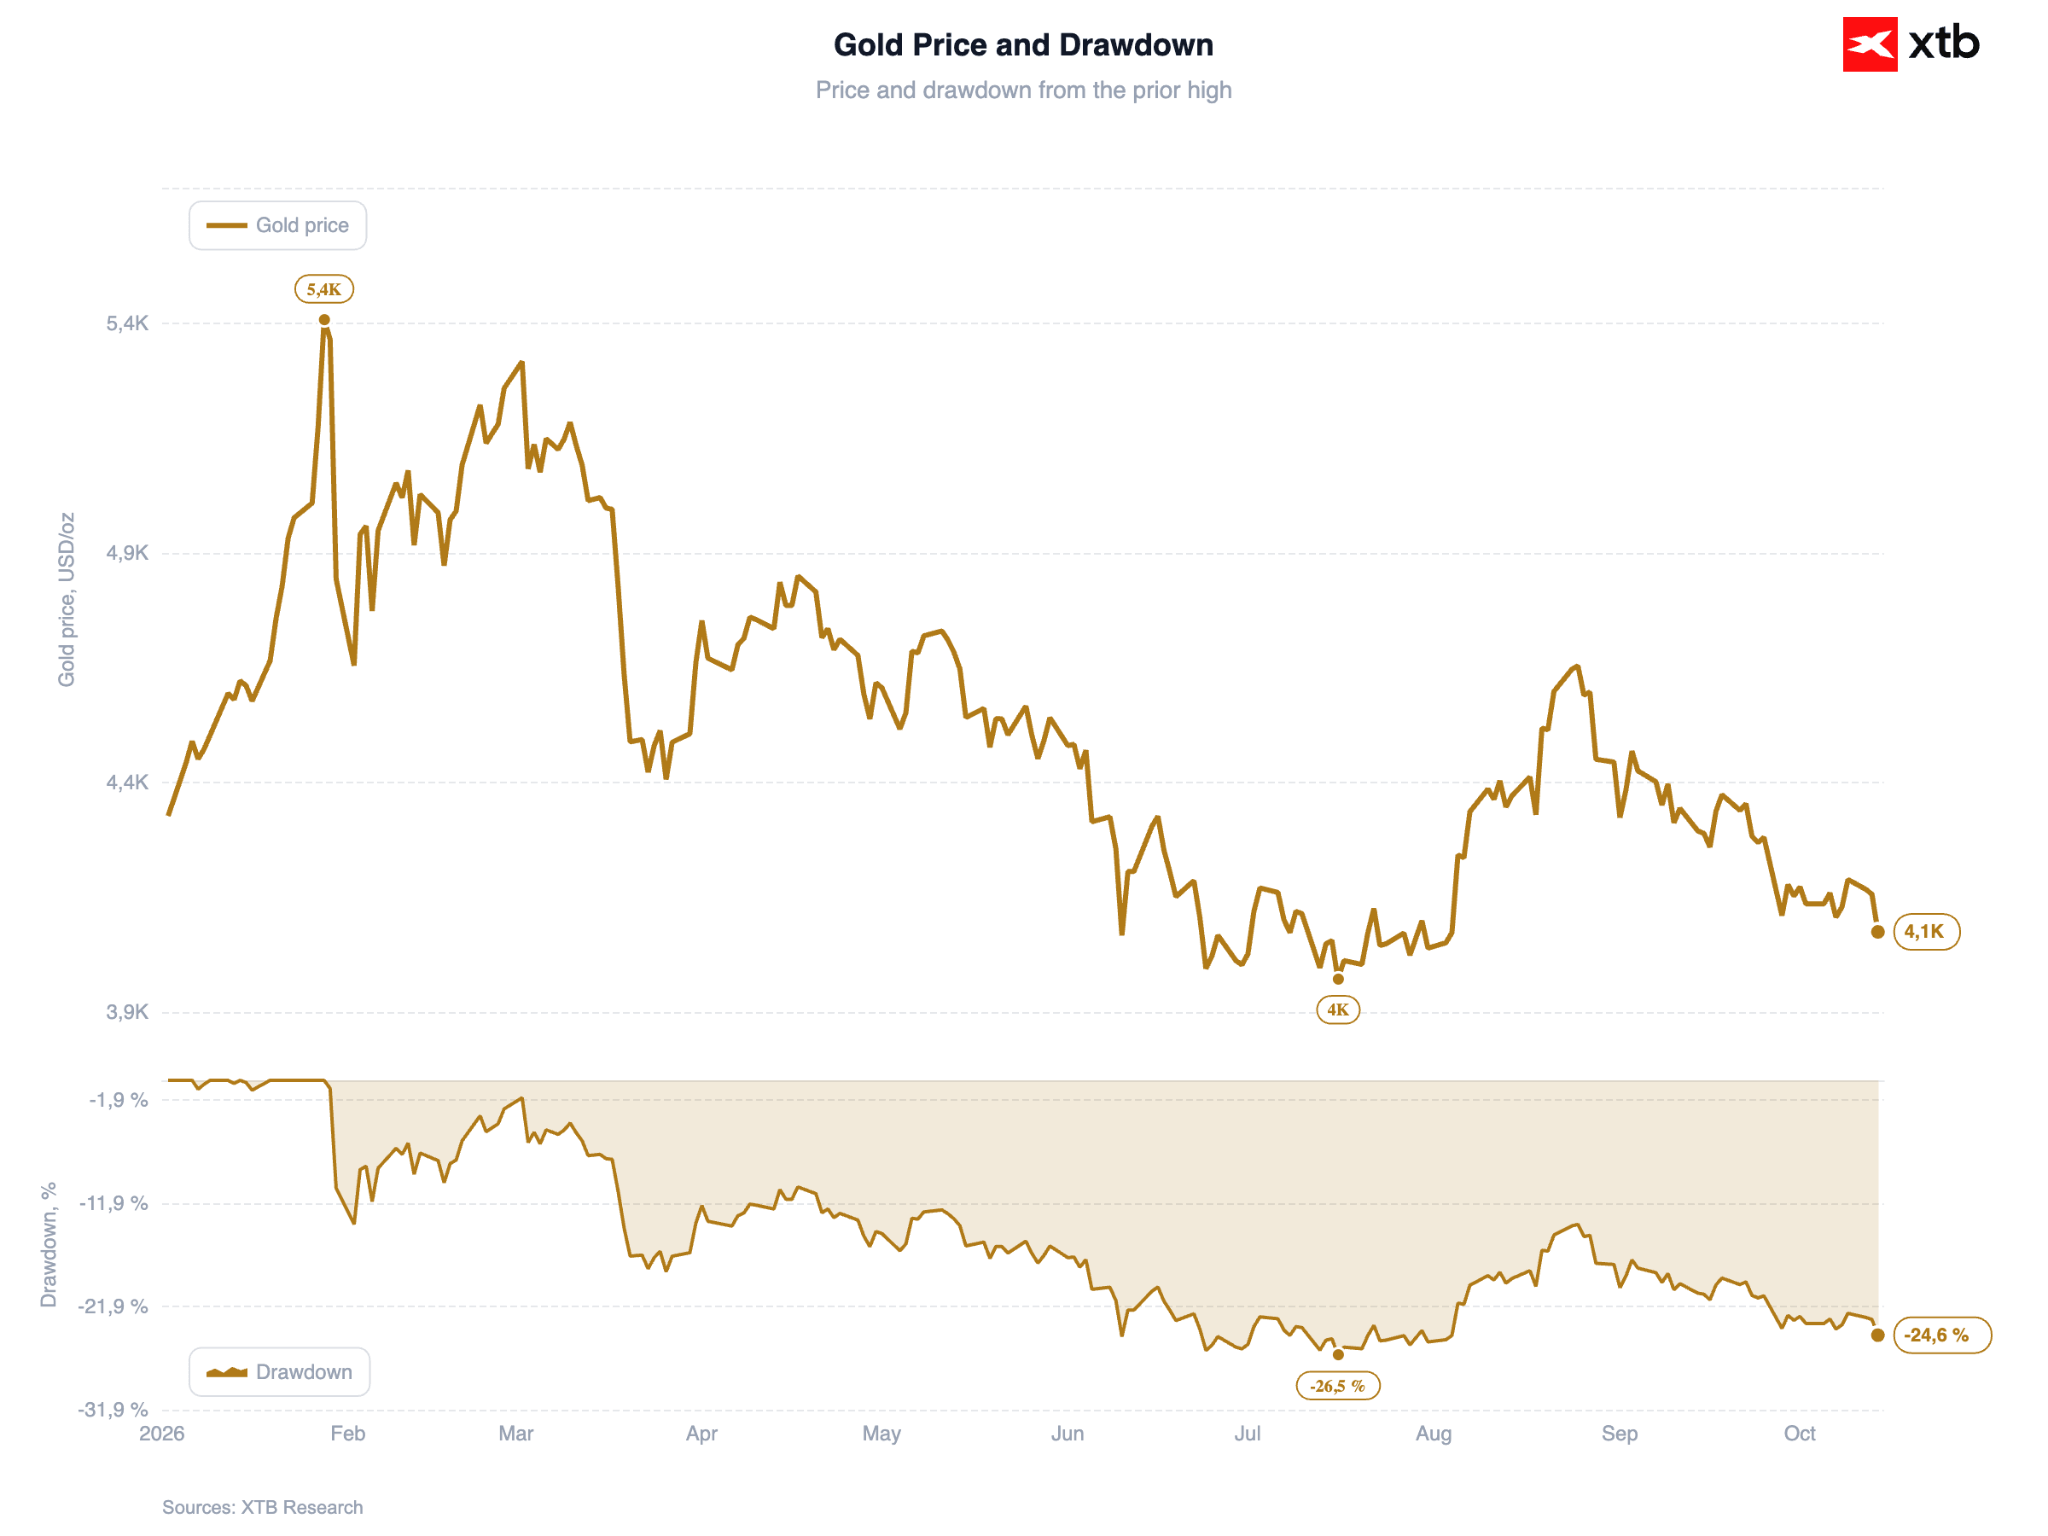
Gold is trading lower by approximately 2%, slipping below $4,090 per ounce. Silver has experienced an even sharper decline, falling 6%. The precious metals complex remains heavily constrained by the upward momentum in US real yields.
Figure 7: Gold (2026)
 Source: XTB Research, 14.10.2026
Energy commodities
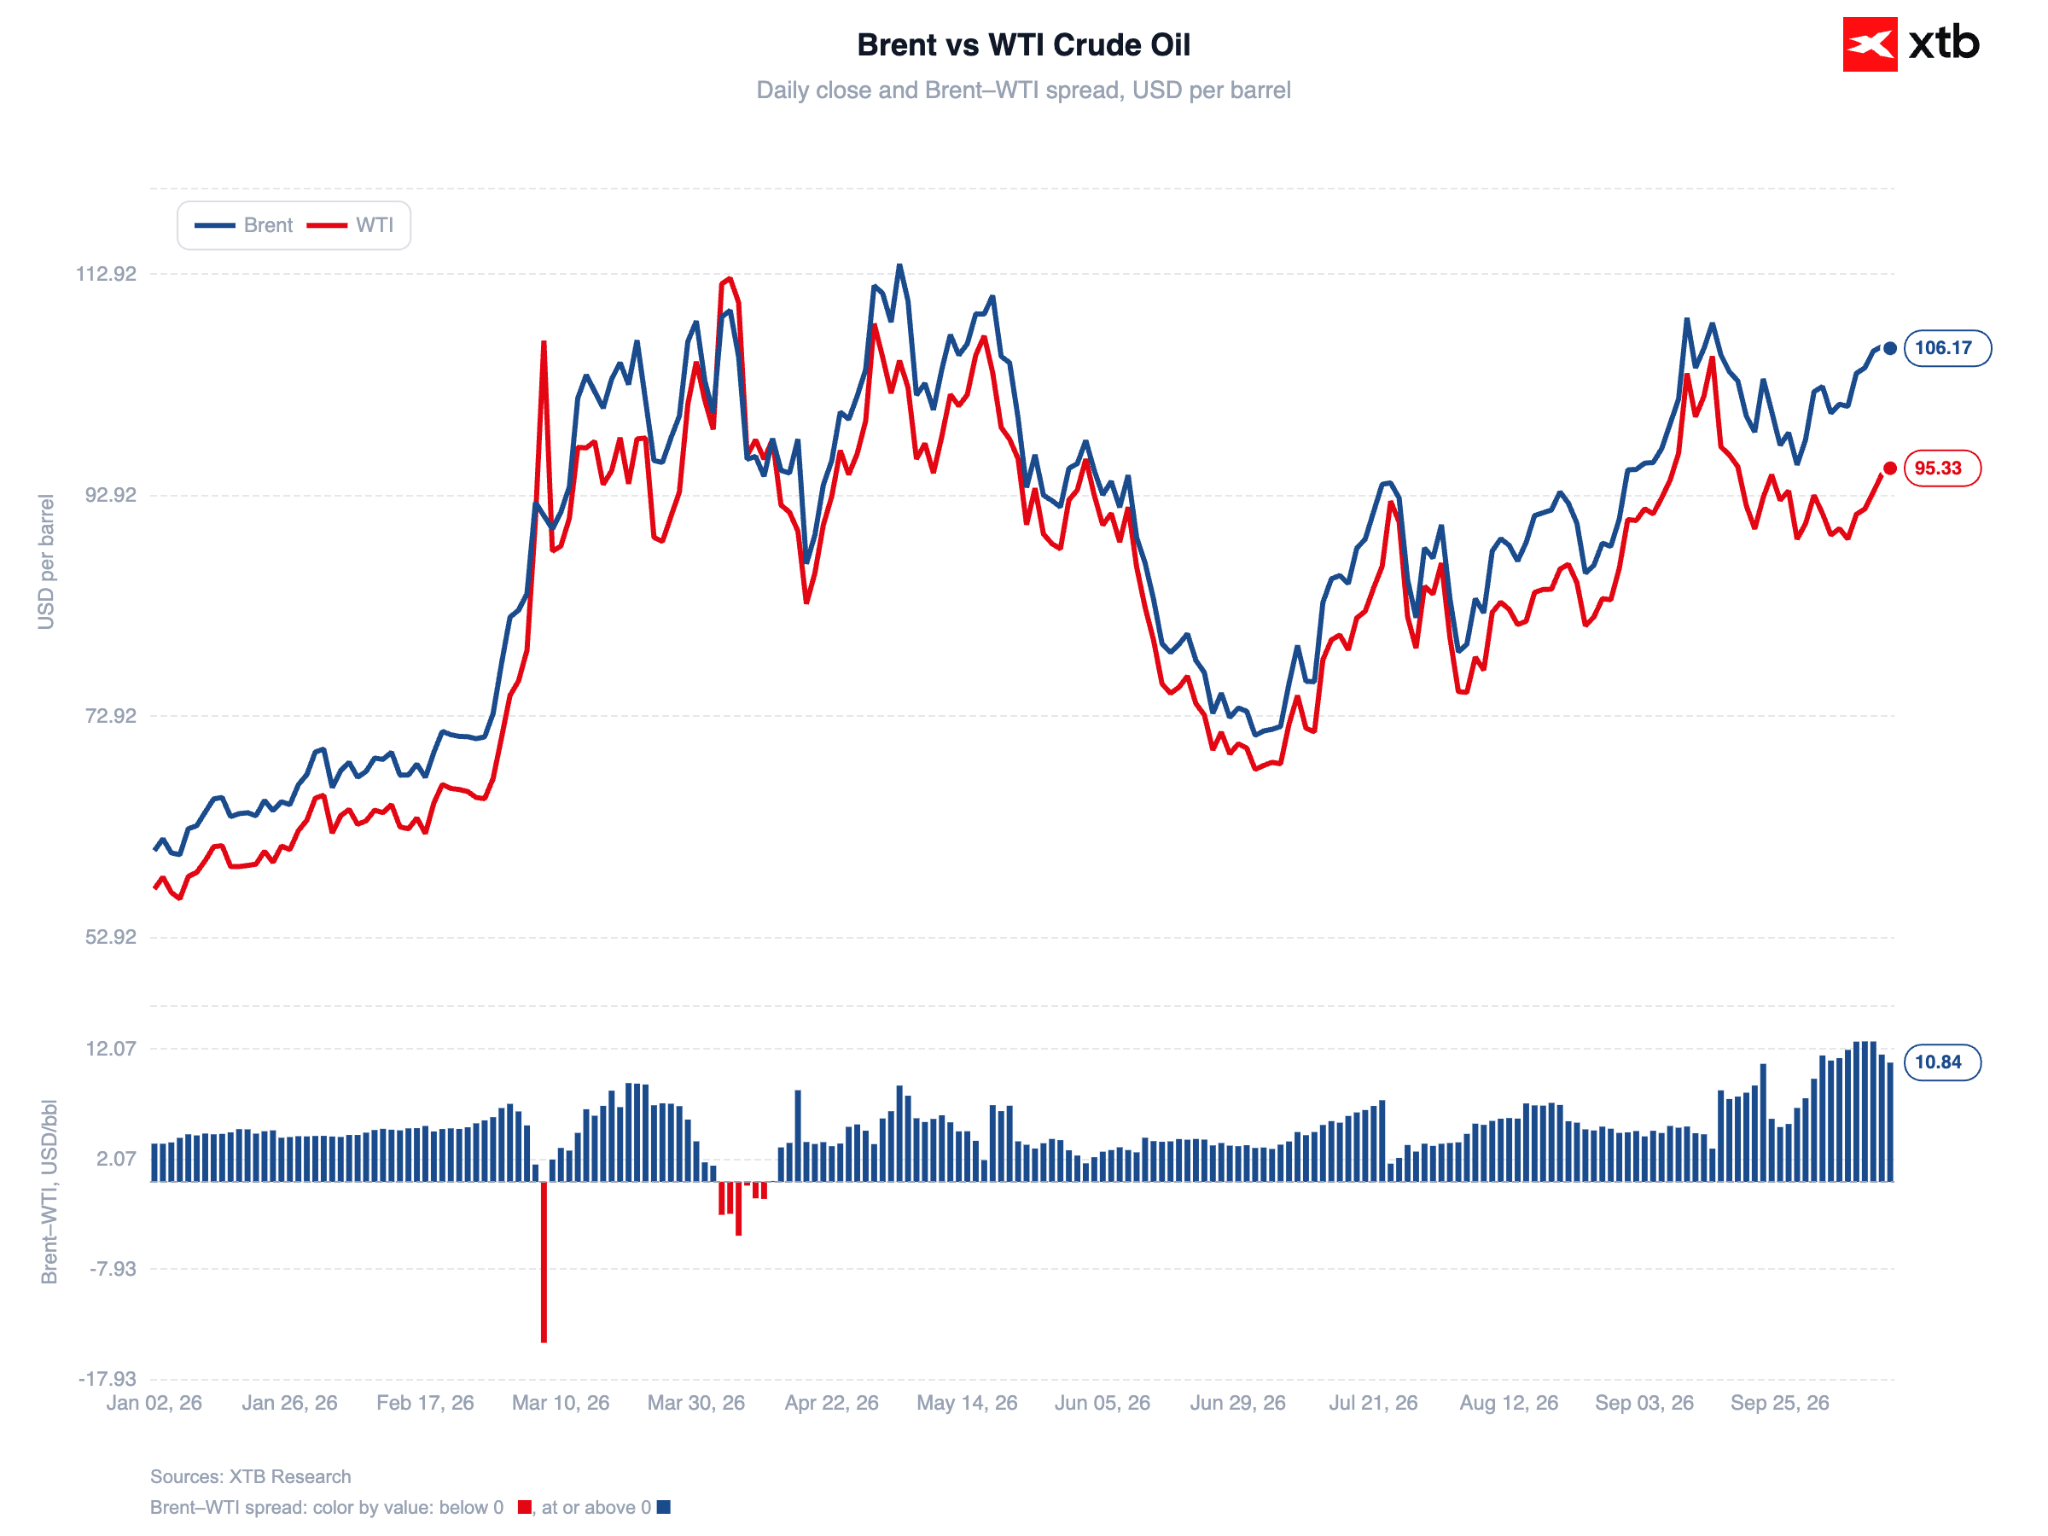
Geopolitical risk premiums in energy markets remain elevated following the conflict escalation in Saudi Arabia. Brent crude is up just over 0.5% ($106 per barrel), while WTI has advanced 1.4% (to around $95.5 per barrel). Houthi forces have continued strikes against Saudi infrastructure, targeting Saudi Aramco's headquarters in Dhahran and the main international airport. These developments occur less than two weeks ahead of the flagship Future Investment Initiative conference in Riyadh.
Figure 8: Brent and WTI crude oil (2026)
 Source: XTB Research, 14.10.2026
Former President Trump accused Houthi forces of deliberately inflating oil prices "at Iran's direction" ahead of the November US Congressional elections, remarking: "I'll be there after the Elections, and I will never forget!"
Additionally, Ukrainian drone strikes against Russian energy infrastructure and ongoing security threats to maritime tankers in the Strait of Hormuz continue to provide fundamental support to energy prices.
—
Michał Jóźwiak, Financial Markets Analyst at XTB



US Open: CPI reading weighs on American indices (14.10.2026)

US inflation concerns rise


POET: A “meme stock” in photonics, is there still hope?


US Open: Earnings season kicks off on a high note (13.10.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.