


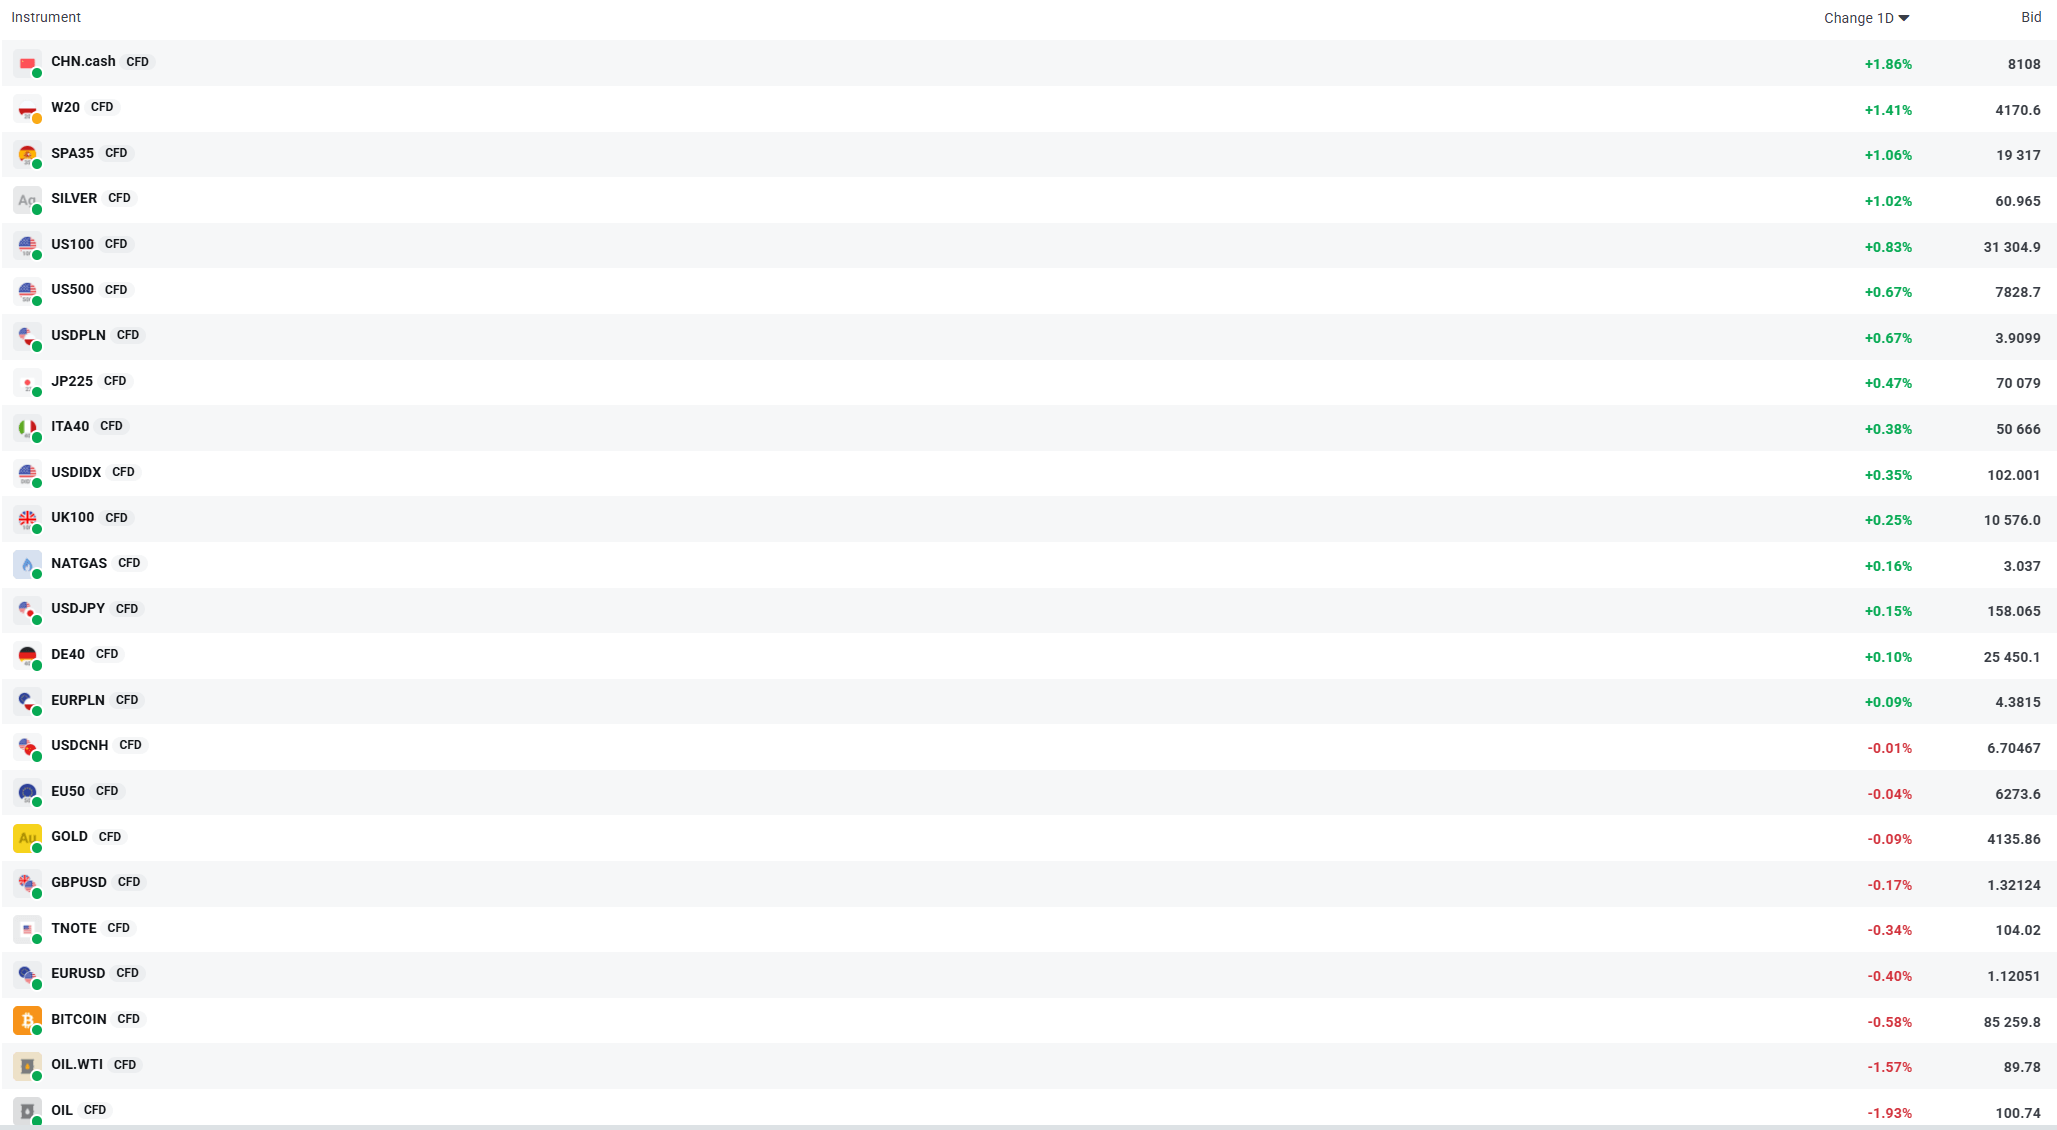
Market volatility was evident just before 8.00 pm in key markets. Source: XTB
- The main driver of volatility. Market sentiment was shaped by US bond yields, which remained close to multi-year highs, reaching around 5.34 per cent for ten-year bonds – their highest level since 2002. Despite this pressure, investors were buying technology companies, which currently act as a sort of hedge against the debt market thanks to their low sensitivity to interest rates and strong demand linked to artificial intelligence. As a result, Wall Street remained remarkably calm, and the Nasdaq index set a new all-time high. The market remains in a phase that analysts describe as resilient to further macroeconomic shocks.
- Geopolitics. A key event was the election in Brazil, in which the right-wing candidate Flavio Bolsonaro clearly defied the poll predictions and progressed to the second round, becoming the clear favourite in the markets. Tensions in the Middle East remain a concern, linked to the Israeli-US conflict with Iran and Houthi attacks on Saudi Aramco facilities, which are sustaining the risk premium in commodity prices. In Europe, investors are concerned about France’s fiscal situation ahead of the 2027 elections and the risk of the problems spreading across the entire eurozone.
- Macroeconomic data. The September ISM index for US services fell to 54.9 points from 55.4 in August, coming in slightly below forecasts but still above the expansion threshold. Of particular concern was the jump in the prices paid sub-index to 74 points – its highest level in over four years – suggesting that inflationary pressure will persist in 2027. Employment in the services sector returned above the expansion threshold to 50.1 points. Following weaker labour market data on Friday, investors have all but ruled out a Fed rate rise in October, and attention is now turning to Wednesday’s minutes from the September meeting.
- Indices. The Nasdaq hit a record high, the S&P 500 gained around 0.6 per cent, whilst the Dow Jones remained close to its opening level. In Europe, the broad-based STOXX 600 rose slightly, but the Paris index lost around 1 per cent and slipped to six-month lows amid concerns over France’s finances. In Asia, the Japanese Nikkei stood out with a strong rise of 2.4 per cent. On the CFD markets, the Chinese index and the Polish W20 performed strongly, with the latter gaining over 1.4 per cent.
- Shares. The rally was driven by technology companies, including Nvidia, Meta, Microsoft and Tesla, as well as Taiwan Semiconductor and SpaceX following reports of a collaboration with Elon Musk’s chip project, whilst Intel fell. PTC saw spectacular gains, rising by around 34 per cent following news of its acquisition by Schneider Electric, as did biotech firm Vaxcyte, which rose by around 30 per cent. Brazilian banks Itau Unibanco and Banco Bradesco also rose sharply, as did the EWZ fund, which gained over ten per cent following the election result. DraftKings and RXO also stood out positively following reports of their acquisition by C.H. Robinson.
- Currencies. The euro slipped to a 17-month low against the dollar, briefly falling to around 1.116 before recouping some of its losses amid concerns over French debt. The dollar strengthened across the board, with its index reaching its highest level since April 2025, supported by high bond yields. The Japanese yen remained weak despite Prime Minister Takaichi’s assurances that debt issuance was under control. Pressure from the dollar was evident in the zloty market, with the USDPLN pair rising by around 0.7 per cent.
- Commodities. Oil prices fell after the G7 countries announced they would release 100 million barrels from their reserves, whilst exports from the Middle East rose above pre-war levels. The price of a barrel of WTI fell by around 1 per cent, whilst CFD contracts fell even more sharply, with oil prices dropping by as much as 2 per cent. However, the declines were limited by persistent supply concerns and a high geopolitical premium. Gold remained stable at around $4,137 per ounce, whilst silver rose sharply, gaining over 1 per cent.
- Cryptocurrencies. Sentiment in the digital assets market was cautious against the backdrop of a strong dollar and high bond yields. Bitcoin fell by around 0.6 per cent, remaining under pressure amid growing risk aversion in this asset class.

BREAKING: U.S. ISM PMI for services comes in below expectations🚨


Market Wrap: France’s Budget, Spain’s Elections. Politics Returns to the Markets

💶Chart of the Day: EURUSD at Lowest Since May 2025 Amid French Fiscal Crisis

Economic Calendar - Key Services PMIs for Europe and the US, and Central Bankers' Decisions
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.