


Stock Market 📈
-
European stock markets are rebounding, supported by falling expectations of a Fed rate hike following weaker US labor market data.
-
The German index is up by over 0.1%, the British FTSE 100 gains nearly 0.4%, and the Spanish IBEX 35 rises by more than 0.5%.
-
The French CAC 40 fell to a 6-month low due to political and budgetary uncertainty in the country.
Companies 🏢
-
Schneider Electric is acquiring PTC for $22.6 billion, offering approximately a 40% premium over the pre-announcement share price, which is intended to accelerate growth in industrial software and artificial intelligence.
-
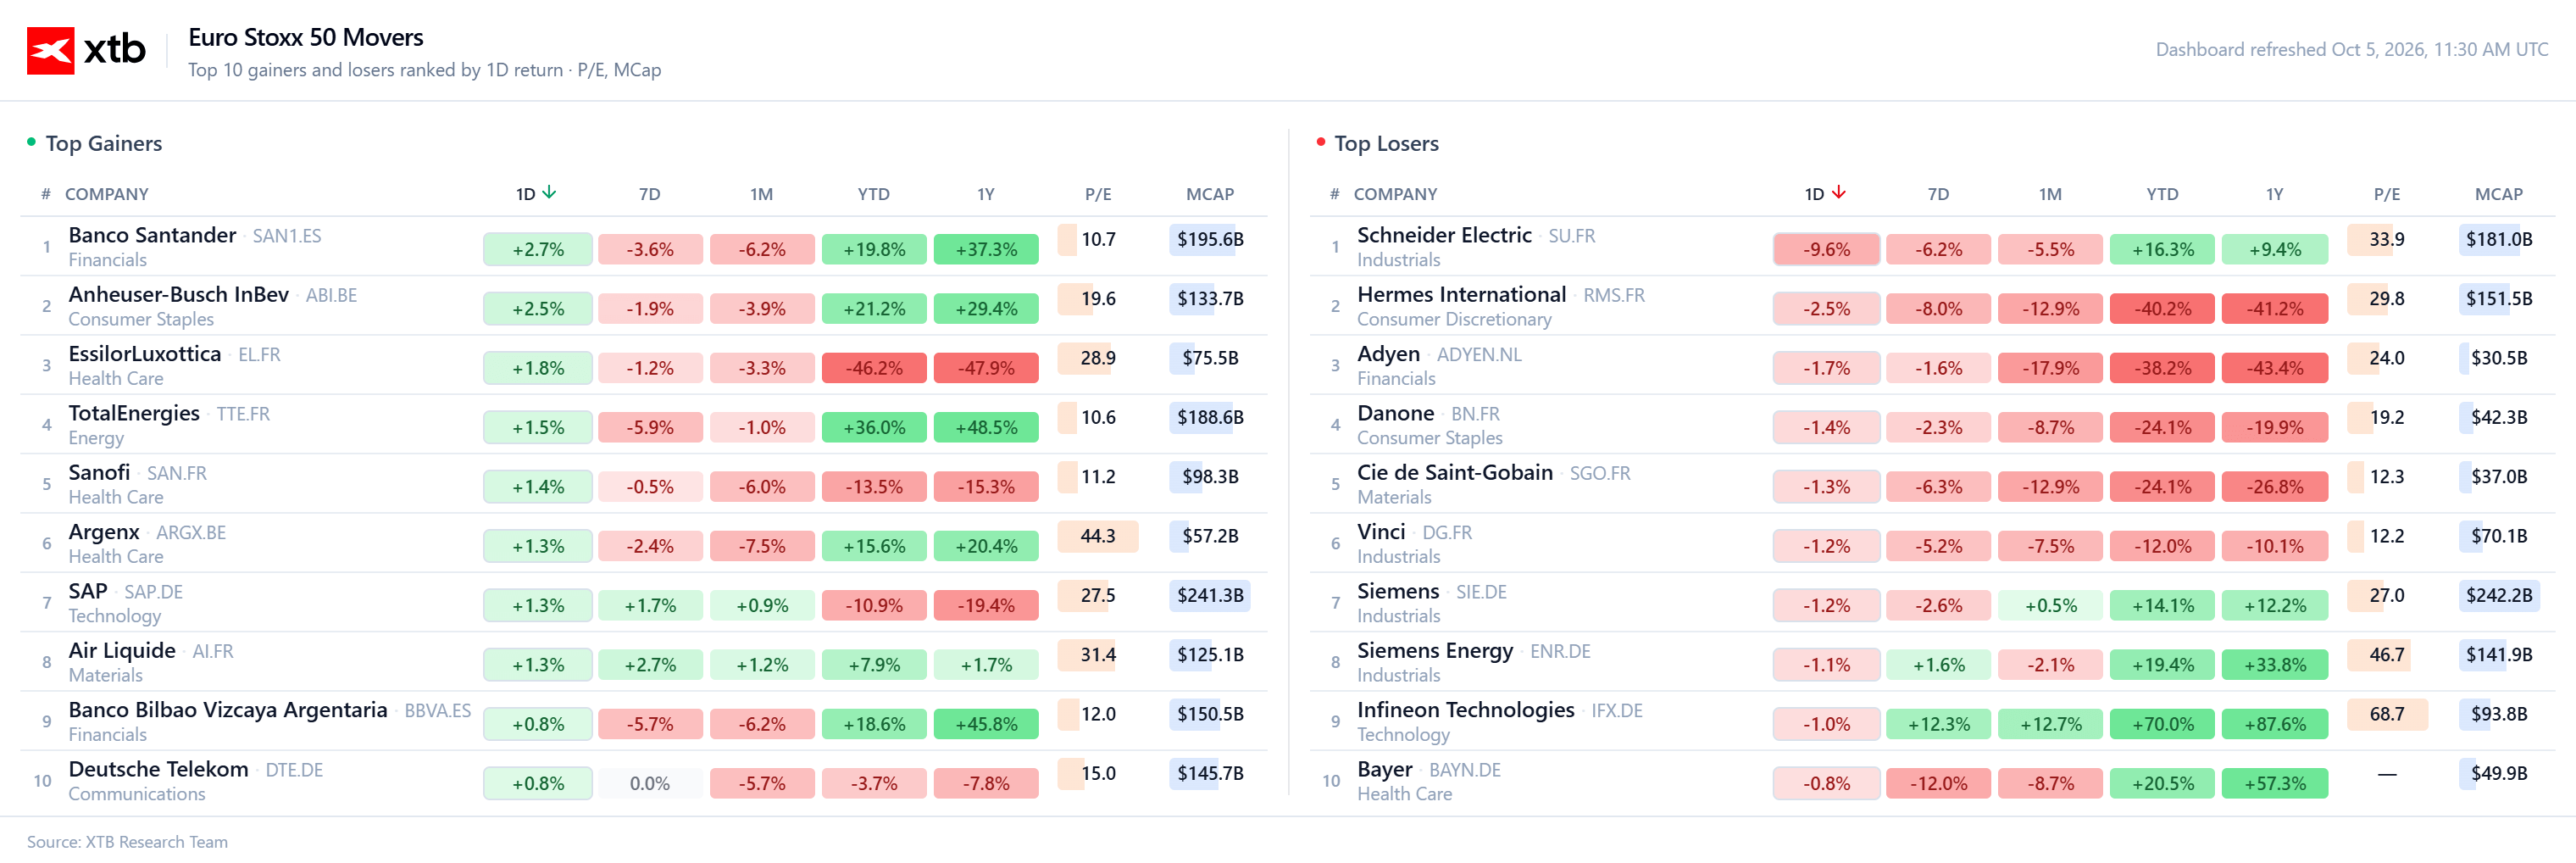
Schneider Electric shares were losing around 9% in the morning in reaction to the high transaction price and financing method—via the issuance of €5–6 billion in new shares (shareholder dilution) and taking on €16–17 billion in debt.
Macroeconomics and Politics 🌍
-
Eurozone PMI positively surprised, showing the fastest activity growth in over three years.
-
Higher inflation, driven mainly by energy prices, may nevertheless limit the ECB's room for further monetary easing.
-
France remains a major source of risk in Europe due to investor concerns that the government will struggle to pass its deficit reduction plan through a divided parliament ahead of next year's elections.
-
The yield on French 10-year bonds approached 5%.
-
Pedro Sánchez announced snap parliamentary elections in Spain for November 29 after failing to pass key housing reforms.
-
Polls in Spain give the advantage to the opposition People's Party (PP), likely supported by the far-right Vox, which could mark the first far-right participation in government since the return to democracy. The snap election is a risky attempt by Sánchez to regain support and keep Spain on a left-wing course.
Currencies 💵
-
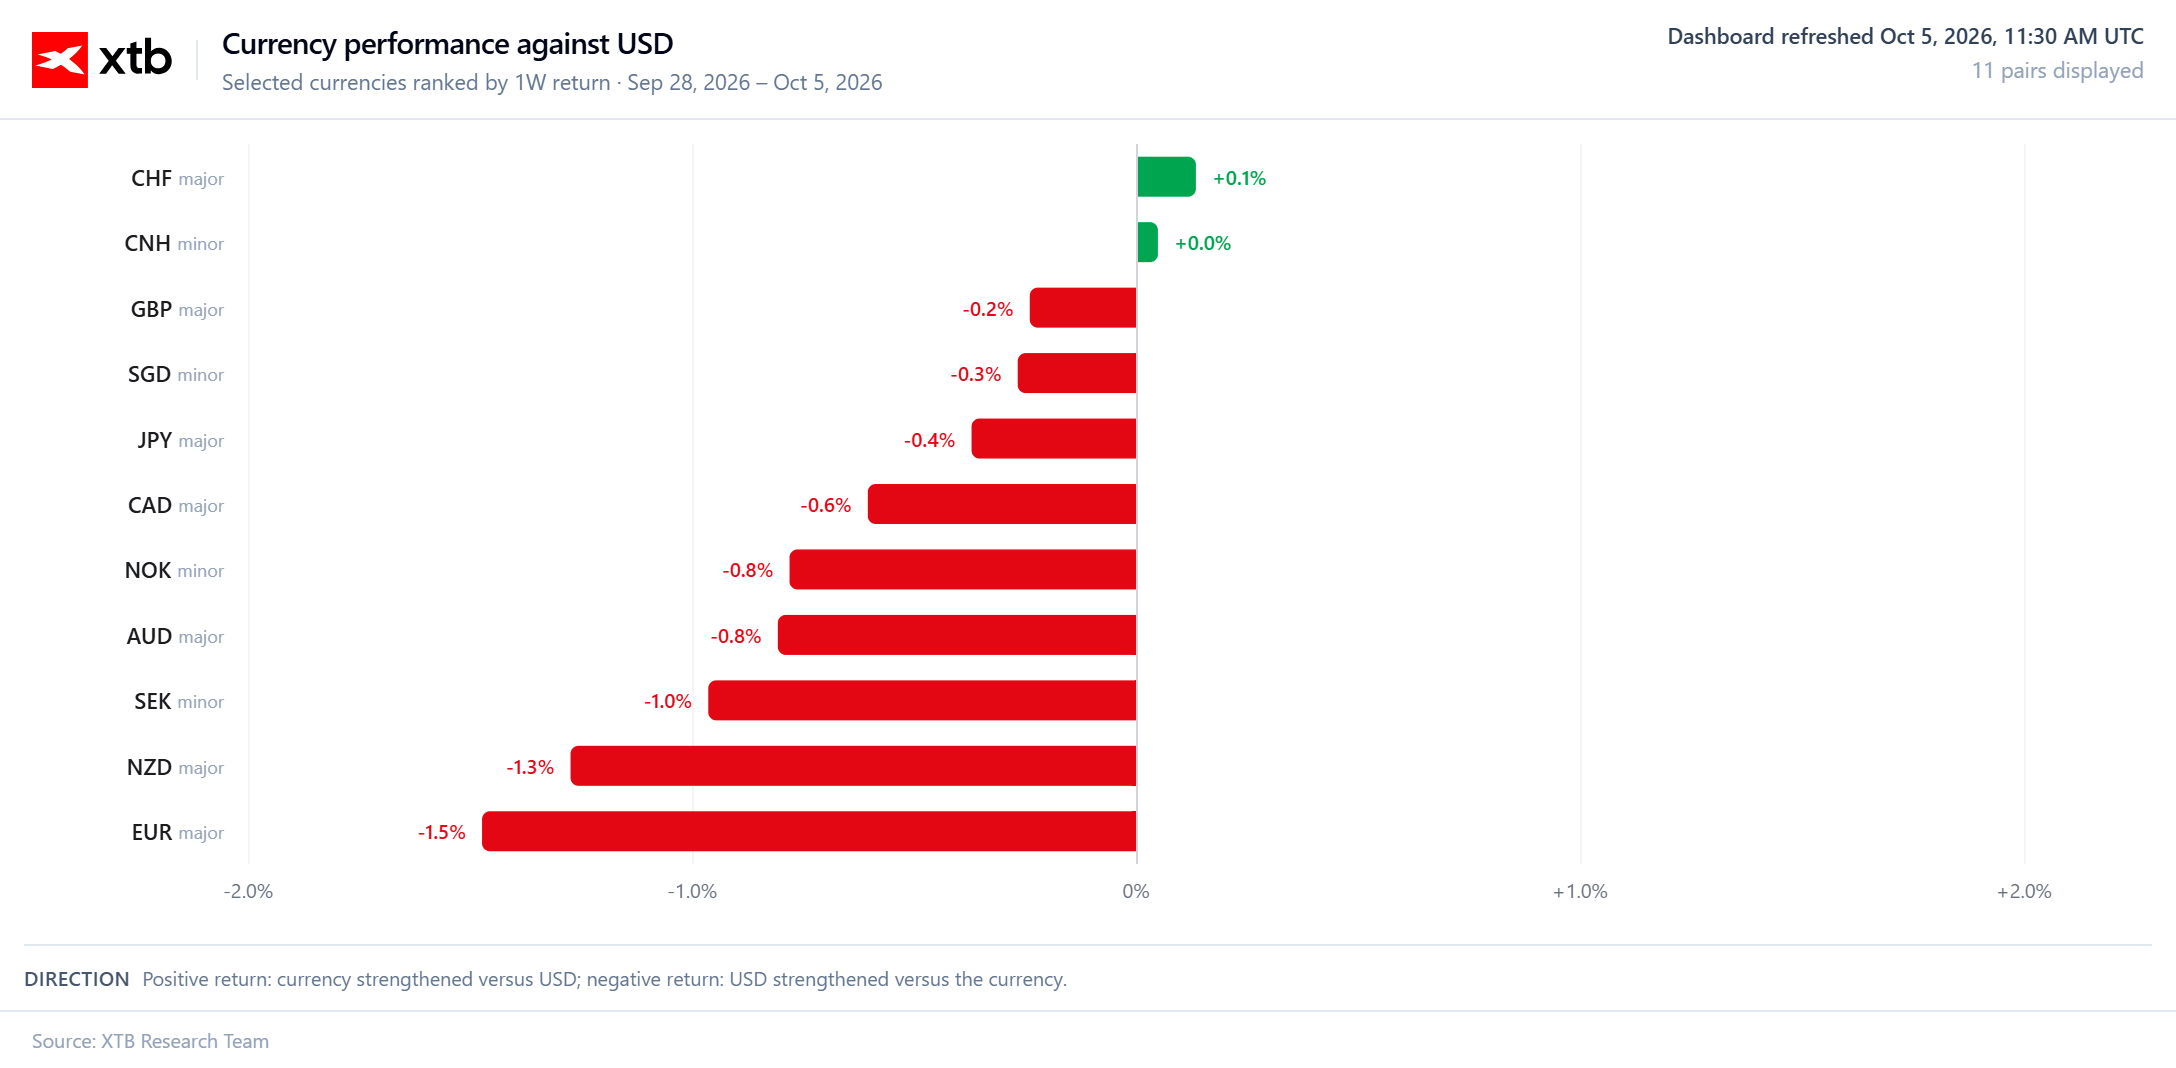
The euro hit a multi-month low, impacted among other factors by political and fiscal pressure in France.
Commodities and Energy 🛢️
-
Middle East oil exports returned to pre-war levels—at times reaching 19.5–22.5 million barrels per day in the last week of September, with a 7-day average of 18.5 million barrels per day.
-
The supply increase stems mainly from larger shipments from Saudi Arabia and the recovery of Iraqi exports through the Strait of Hormuz, helping ease market tensions, particularly in Asia.
-
LNG exports through the Strait of Hormuz in September rose to their highest level since February.
-
The situation in Hormuz remains tense—at least seven attacks on tankers were reported in the last week.
-
Positive sentiment prevails in the precious metals market: gold futures are gaining about 0.5%, holding near $4,150 per ounce, while silver rises by over 2.5%, approaching $62 per ounce.
Cryptoassets 🪙
-
Gains are also visible in the cryptocurrency market: Bitcoin is up about 0.2%, hovering around $86,000, while Ethereum gains 0.5%, breaking above $2,700.

Schneider Electric pays a high price for AI and software growth


💶Chart of the Day: EURUSD at Lowest Since May 2025 Amid French Fiscal Crisis

Economic Calendar - Key Services PMIs for Europe and the US, and Central Bankers' Decisions
Morning Briefing: Dollar gains, oil falls. EURUSD at multi-month lows
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.