


The defense sector has remained one of the strongest investment themes in global equity markets over the past several years. High defense spending, the war in Ukraine, security tensions in the Middle East and rising military orders have supported both corporate revenues and valuations. The picture is now becoming more complex, however: some companies continue to benefit from record defense budgets, while risks related to elevated valuation multiples, the cost of expanding production capacity and potential shifts in geopolitical priorities are becoming increasingly important.
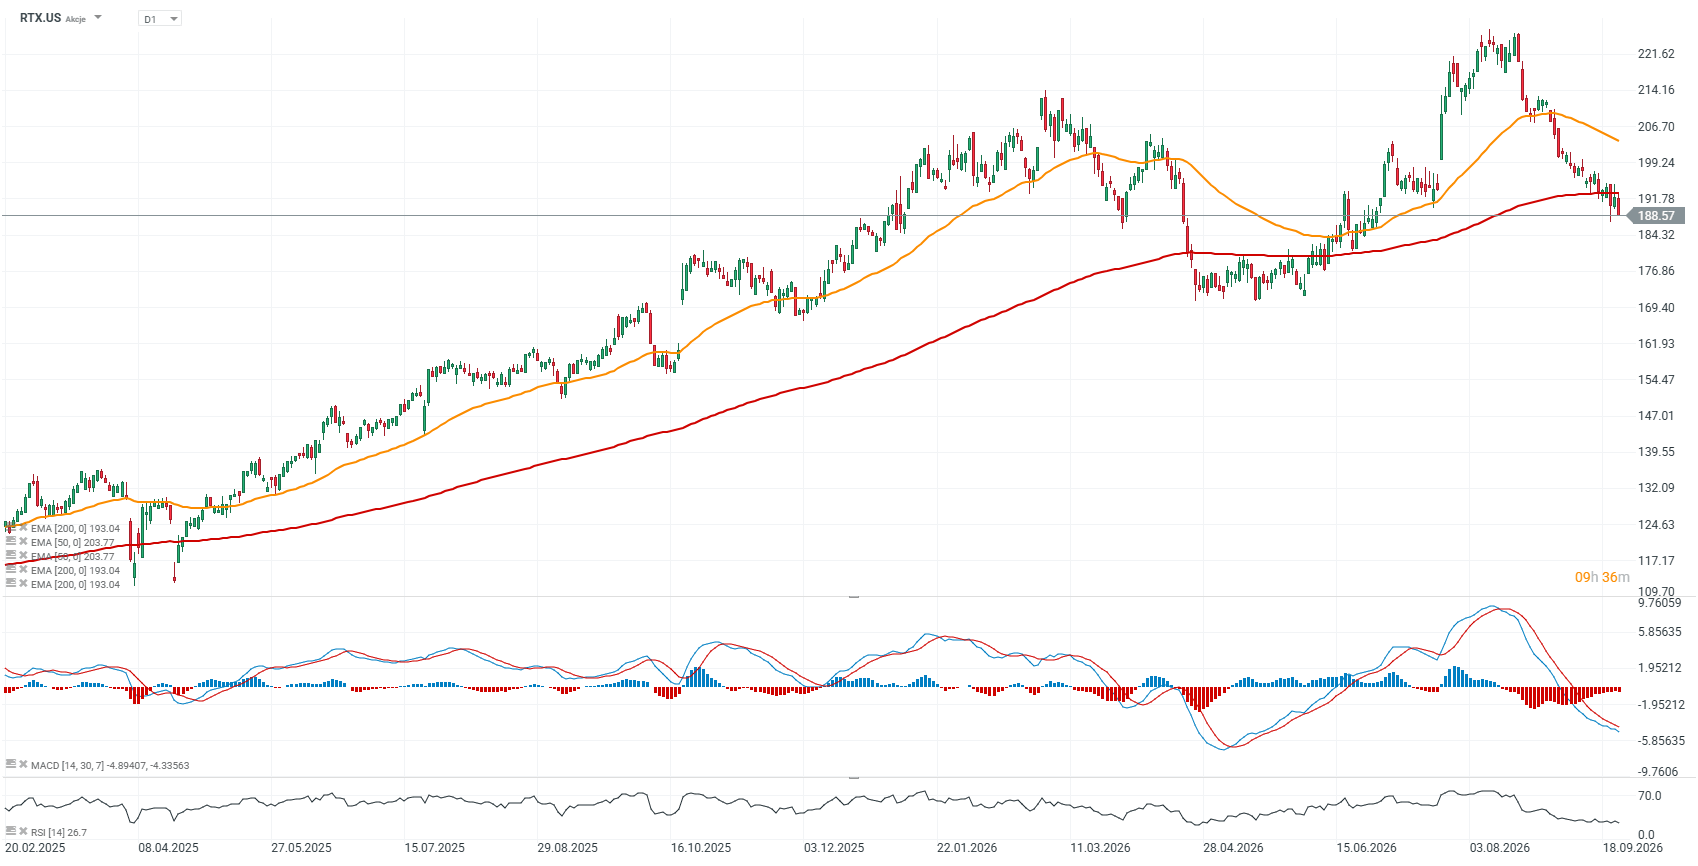
At the same time, warfare appears to be becoming increasingly “technological,” which raises questions about the business models of some traditional defense contractors when competing with companies such as Palantir and, potentially in the future, U.S. Big Tech firms with access to advanced artificial intelligence capabilities. The issue is far from one-dimensional, however. This year, even RTX Corp, the largest U.S. defense contractor formerly known as Raytheon and widely seen as a beneficiary of expanded Patriot, THAAD and PAC-3 production, has struggled. Its shares have fallen below a key long-term moving average and are down around 20% from their peak. So what is weighing on the defense sector?
RTX chart, D1 interval
RTX Corp shares have pulled back and are now trading below the EMA200, shown by the red line, for the first time since May this year. Even so, the stock has gained nearly 115% over the past five years, compared with roughly 72% for the S&P 500 and 98% for the Nasdaq 100. So has RTX benefited from the megatrend? Absolutely, but periods of weakness are inevitable.
 Source: xStation5
Defense stocks after several years of impressive gains
The U.S. defense sector, and especially its European counterpart, has enjoyed several years of very strong expansion, so some profit-taking should not come as a surprise. The war in Ukraine, higher NATO spending and the need to replenish ammunition and equipment inventories have translated into a sharp increase in order backlogs for major defense manufacturers. At the same time, investors are increasingly questioning whether the pace of growth seen in recent years can be sustained.
Valuations across many European defense companies remain elevated, while investors are paying closer attention to backlog quality, margins and the actual ability of companies to scale production. Geopolitics also remains an important factor. Any de-escalation of the war in Ukraine or temporary improvement in U.S.-China relations could reduce part of the geopolitical risk premium that has supported the sector in recent years.
European defense companies still trade at a substantial premium
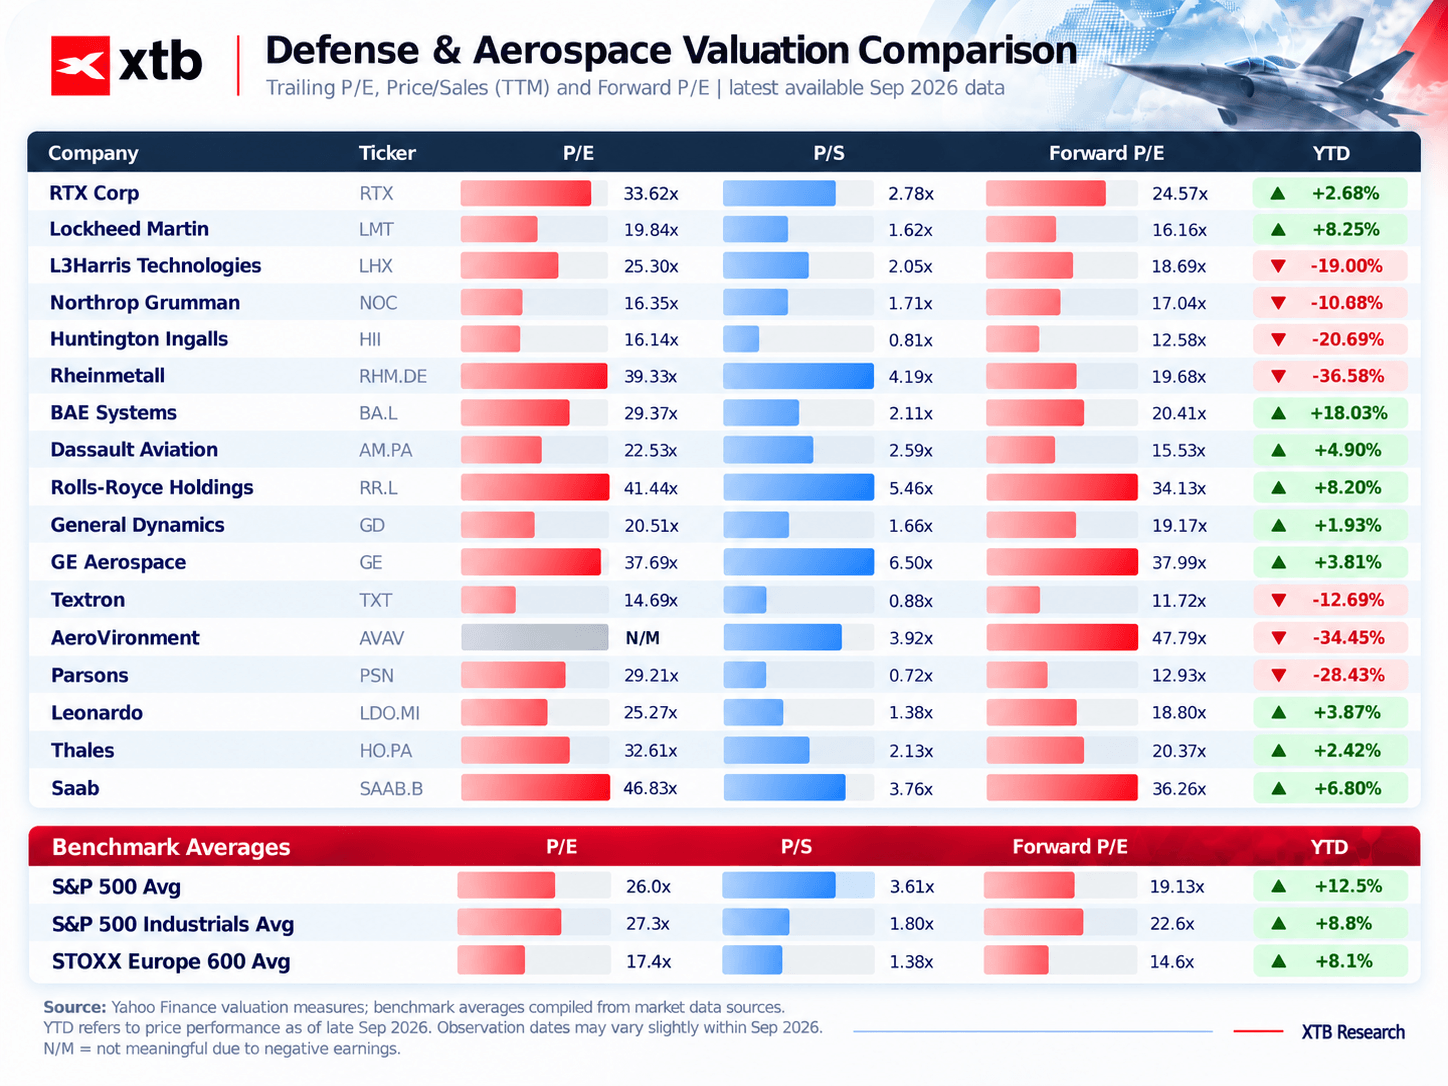
The largest European defense companies continue to trade at significantly higher valuations than the broader market. Rheinmetall trades at a price-to-earnings ratio close to 40, while Saab trades at more than 46 times earnings. Elevated multiples are also visible in companies such as Rolls-Royce, GE Aerospace and several aerospace and missile technology manufacturers. By comparison, the average P/E ratio for the S&P 500 is around 26, while the STOXX Europe 600 trades at roughly 17 times earnings. This shows that investors are still willing to pay a significant premium for exposure to rising defense spending.
Not all companies look equally expensive, however. Lockheed Martin, Northrop Grumman, Huntington Ingalls, General Dynamics and Textron trade much closer to historical valuation standards for the U.S. industrial sector than some of the most highly valued European names. Some are even valued 30% to 40% below the broader index average, including Huntington Ingalls, which builds aircraft carriers, and Textron, which is focused on aviation and helicopters.
One potential cushion for the sector is therefore the relatively lower valuation of some large U.S. defense contractors.
Source: XTB Research, Yahoo Finance
Europe’s “defense premium” is becoming harder to justify
In Europe, a key question is increasingly whether record order books will actually translate into sustainable earnings growth. A large backlog does not automatically guarantee high profitability, especially when fulfilling contracts requires significant increases in employment, new factories and higher capital expenditure.
A good example is the large Bundeswehr frigate contract involving Rheinmetall that was cancelled despite more than EUR 2 billion already being spent. This may make investors more cautious about the “quality” of defense order books in Europe. High valuations also leave less room for error. When multiples are far above the broader market average, even a modest disappointment in growth can trigger a much stronger share-price reaction.
Political risk should not be ignored either. In Western Europe, including Germany, right-wing parties advocating a normalization of economic relations with Russia have been gaining popularity. It is not difficult to imagine that a political shift in this direction could, at least temporarily, weaken confidence in the durability of rising defense spending.
In the U.S., the cost of expanding production capacity is becoming a problem
U.S. defense companies face a somewhat different set of challenges. Demand for missiles, air-defense systems and space technologies remains strong, but increasing production requires substantial investment. With bond yields still elevated, the cost of capital remains relatively high, while the Pentagon may become more cautious in deploying public funds against the backdrop of very large and rising government debt.
For companies such as RTX, Lockheed Martin and General Dynamics, this means having to finance new production lines, build inventories and execute multi-year government contracts at the same time. Large strategic programs, including missile production expansion and projects related to Golden Dome, may support revenues over the long term, but they can initially weigh on cash flow.
Smaller companies under the greatest pressure. What does it mean?
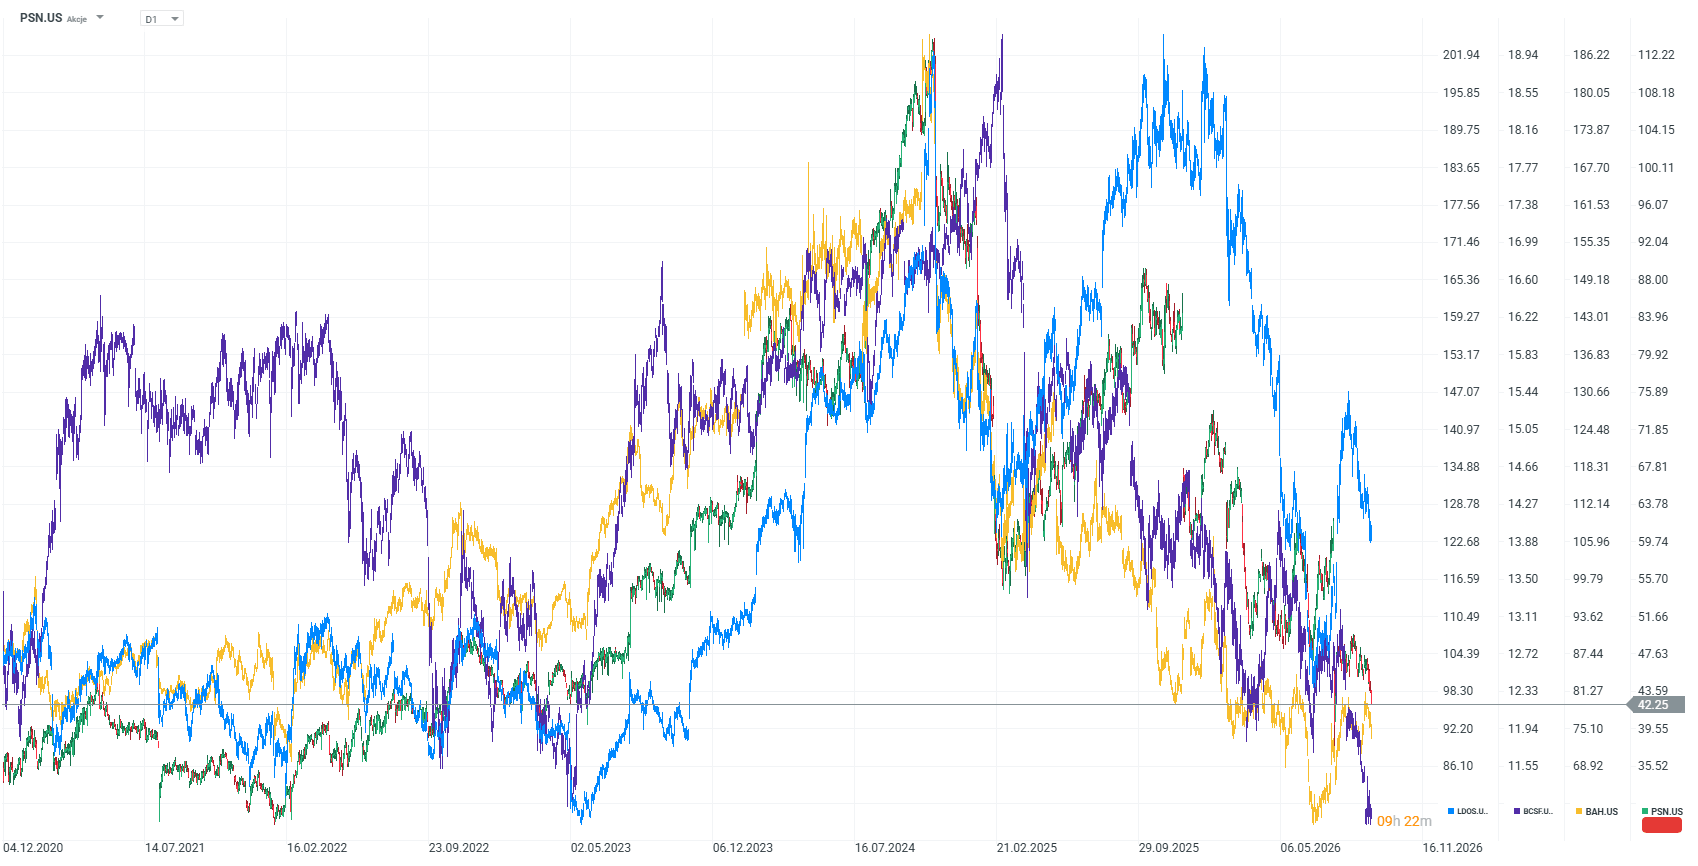
The performance of a number of small and mid-sized defense suppliers looks significantly weaker. AeroVironment, Parsons, Booz Allen Hamilton, BNTX Technologies and others have posted sharp declines, while some of the largest contractors have delivered much more stable performance. Smaller companies are generally more sensitive to individual contracts, cost increases and changes in procurement schedules. They also tend to have less negotiating power with major customers and prime contractors.
Over the longer term, another potential risk is growing competition from technology companies. In areas such as drone technologies, autonomous combat systems, data analytics and artificial intelligence, traditional defense suppliers are increasingly competing not only with one another, but also with rapidly growing technology companies.
The defense sector is therefore no longer simply a bet on higher military spending. Company selection, valuation, backlog quality and the ability to convert rising revenues into cash flow and profits are becoming increasingly important. The chart below shows the share prices of Parsons, Leidos, BAE and Booz Allen Hamilton, companies that have experienced declines of more than 50%.
All of this suggests that investors are likely to remain selective when choosing defense stocks. Companies most exposed to changes in the nature of warfare, including aircraft carriers, helicopters, military consulting and “second-tier” infrastructure, could remain at a discount for longer, while key producers of missiles, space systems and critical technologies may emerge from the correction in a stronger position. It is difficult to argue that the era of geopolitical instability is already behind us. This remains a long-term trend that may continue to support the strongest businesses with strategic technologies and production assets.
 Source: xStation5


US Open: Wall Street moves higher as oil slides 🗽 Synopsys shares jump on HSBC upgrade

Microsoft is turning Copilot into a revenue Engine for AI



Market Wrap: Further rise in oil prices weighs on European stocks (24.09.2026)



Daily Summary: US dollar reaches new highs, Wall Street, gold and bitcoin fall (23.09.2026)
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.