


The morning brings a return to risk-off mode, even though the previous session on Wall Street was strong (S&P 500 +0.58%, Nasdaq +1.05%). Investors have digested Meta’s and Tesla’s earnings, and sentiment has clearly deteriorated. The epicenter of the sell-off today is in Asia—CHN.cash (-3.16%) , which fits the picture of a Chinese bear market (the CSI 300 has fallen 20% from its June peak, marking its tenth consecutive week of declines amid an oversupply of power, a weak real estate market, and eroding retail investor confidence). Japan is also looking weak—JP225 (-2.76%). In the U.S., the pressure is once again shifting to tech companies vulnerable to the funding boom in AI—US100 is down 1.63%, significantly more than the broader US500 (-0.86%) . Europe is also in the red: EU50 -1.08%, DE40 -0.77%, ITA40 -0.94%, while the UK100 (-0.28%) is holding up slightly better.
The precious metals market saw a marked reversal of the previous trend—SILVER plummeted 3.07% to around $56.1, while GOLD fell by 1.12% below $4,100 (around $4,094), testing the key support level of $4,100–$4,117; a sustained decline below this level opens the way to the psychological level of $4,000. Rising yields and higher oil prices are putting pressure on metals. It is oil that is on the other side today—driven by a geopolitical premium (reports of plans to strike Iran again after the midterms, intensified Houthi attacks on Saudi Arabia) OIL is up 1.66% to about $107.5, and OIL.WTI is up 1.70% to about $99.4. In the foreign exchange market, the dollar is slightly weaker (USDIDX -0.19%) — EURUSD +0.15% to 1.1247, GBPUSD +0.10%, and USDJPY is down 0.63% to about 157.1. The risk-off sentiment isn’t sparing cryptocurrencies either — BITCOIN -2.66% to about 82,400 USD.
What's driving the market today:
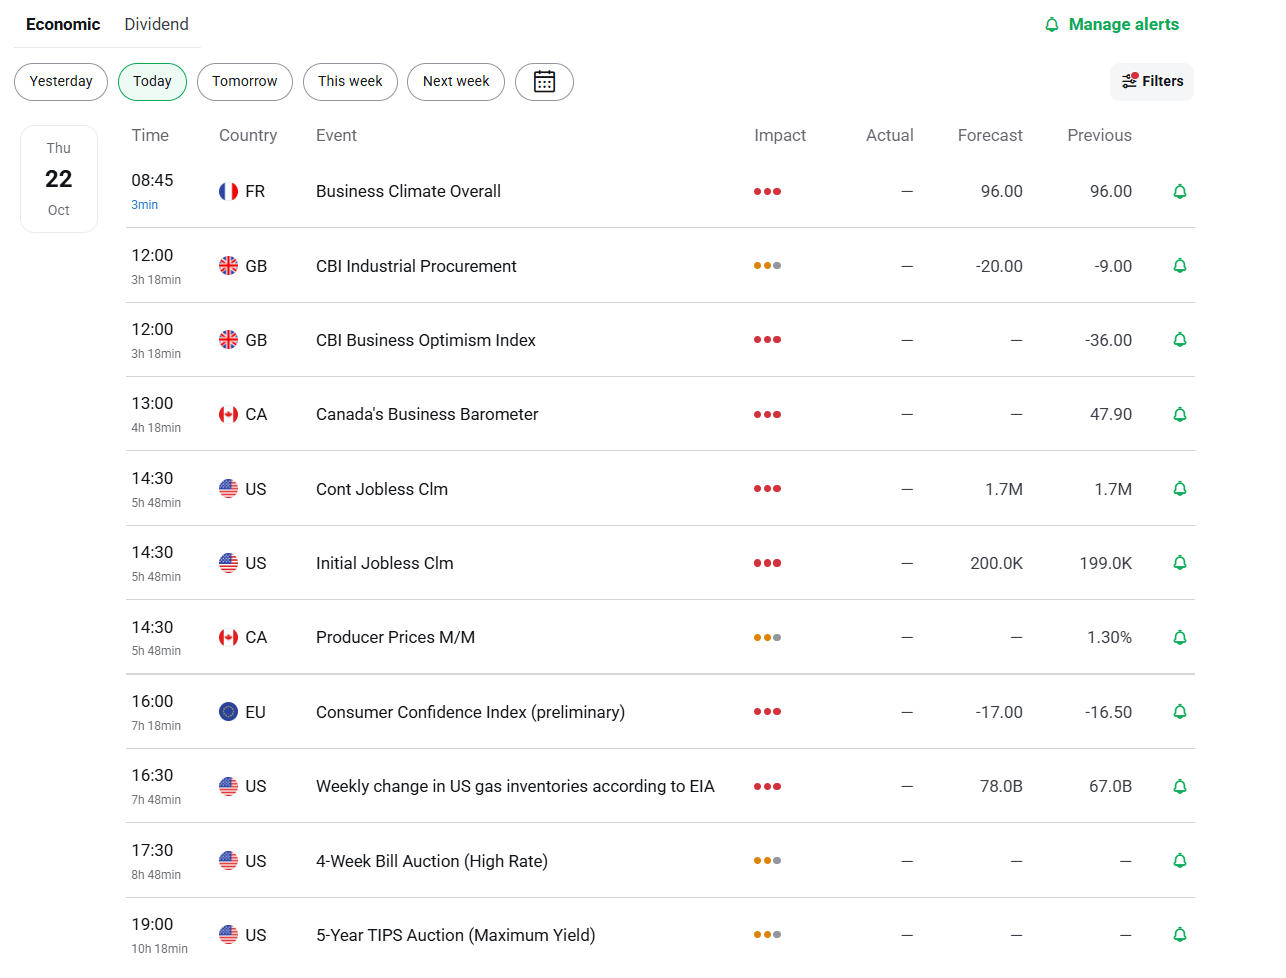
This trading session is light on macroeconomic data. News from Asia included a slowdown in inflation in New Zealand (3.7% y/y vs. a forecast of 3.8%) and the Bank of Korea’s decision to keep interest rates at 3.00%, leaving the door open for a move in November. Here in Poland, at 9:00 a.m., we’ll see the Polish retail sales figures (year-over-year). However, the highlight of the day remains the U.S. weekly initial jobless claims at 14:30 (consensus around 200,000), followed by the EIA natural gas inventory report at 16:30.
The earnings season is setting the pace. Yesterday was dominated by reports from Meta (record revenue up 26% year-over-year to $64.6 billion and a strong forecast for Q4, but capex up 80% year-over-year and negative free cash flow—the cost of the “all-in on AI” strategy) and Tesla (a positive surprise in earnings quality and talk of a potential merger with SpaceX). Today, before the market opens, Procter & Gamble (PG.US), Western Digital (WDC.US), and Lockheed Martin (LMT.US) will report before the market opens, and Valero Energy (VLO.US) will report after the market closes. Bill Ackman’s appearance on CNBC (around 5:00 p.m.) will also draw attention.
In the broader context, it will be worth watching whether the Asian sell-off (particularly the Chinese bear market) and this morning’s weakness will intensify at the U.S. market open, as well as whether a further rise in oil prices will reignite inflation fears and put pressure on central banks.



Daily Summary: SpaceX and the tech sector drive Wall Street, oil retreats sharply below $97

Russia is selling off gold reserves. Why, to whom, and does it matter for the market?
BREAKING: US oil inventories fall more than expected, but distillate build cools enthusiasm

RBA turns increasingly hawkish as markets reprice November rate hike expectations ⚔️
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.