


This morning’s trading is marked by a global flight from risk, which had its epicenter in Asia overnight. The sell-off in the tech sector on Wall Street spilled over to the markets in Korea and Japan, and futures for major indices are heading into Europe in negative territory. The sharpest decline is being seen in Japan’s JP225 (-2.59%), which is being dragged down by a sell-off in memory and semiconductor equipment manufacturers. The tech-heavy US100 (-1.07%) is also performing poorly, while the broader US500 (-0.32%) and European indices (EU50 -0.50%, DE40 -0.18%) are holding up slightly better—this is a typical picture of a trading session in which companies sensitive to the cost of financing AI expansion are under the most pressure.
At the other end of the spectrum are precious metals. GOLD (+0.93%) is consolidating its position as a safe haven around $4,142 per ounce, as is SILVER (+1.38%), driven by a weaker dollar and falling bond yields. The dollar index (USDIDX -0.40%) is pulling back after reaching a multi-month high, which is supporting major currency pairs—EURUSD is up 0.52% to 1.1210, and GBPUSD is up 0.48% . Interestingly, oil prices are falling despite tensions in the Strait of Hormuz—OIL is down 2.05%, and OIL.WTI is down 1.38%, which the market attributes to reports of a possible easing of sanctions on the “shadow fleet.” The risk-off sentiment is also affecting cryptocurrencies—BITCOIN -0.83% (approx. $80,900).
What's driving the market today:
Among the morning data releases, the spotlight was on the UK’s GDP for August, which came in better than expected—the economy grew by 0.1% MoM (forecast: -0.1%) and as much as 2.1% YoY versus the expected 1.7%, the highest rate since August 2022. The pound rose in response, and gilt yields fell across the entire yield curve. On the other hand, data from Australia disappointed—employment fell by 39,300 jobs (forecast: +20,000), which weighed on the Australian dollar and reduced expectations for an RBA rate hike in November.
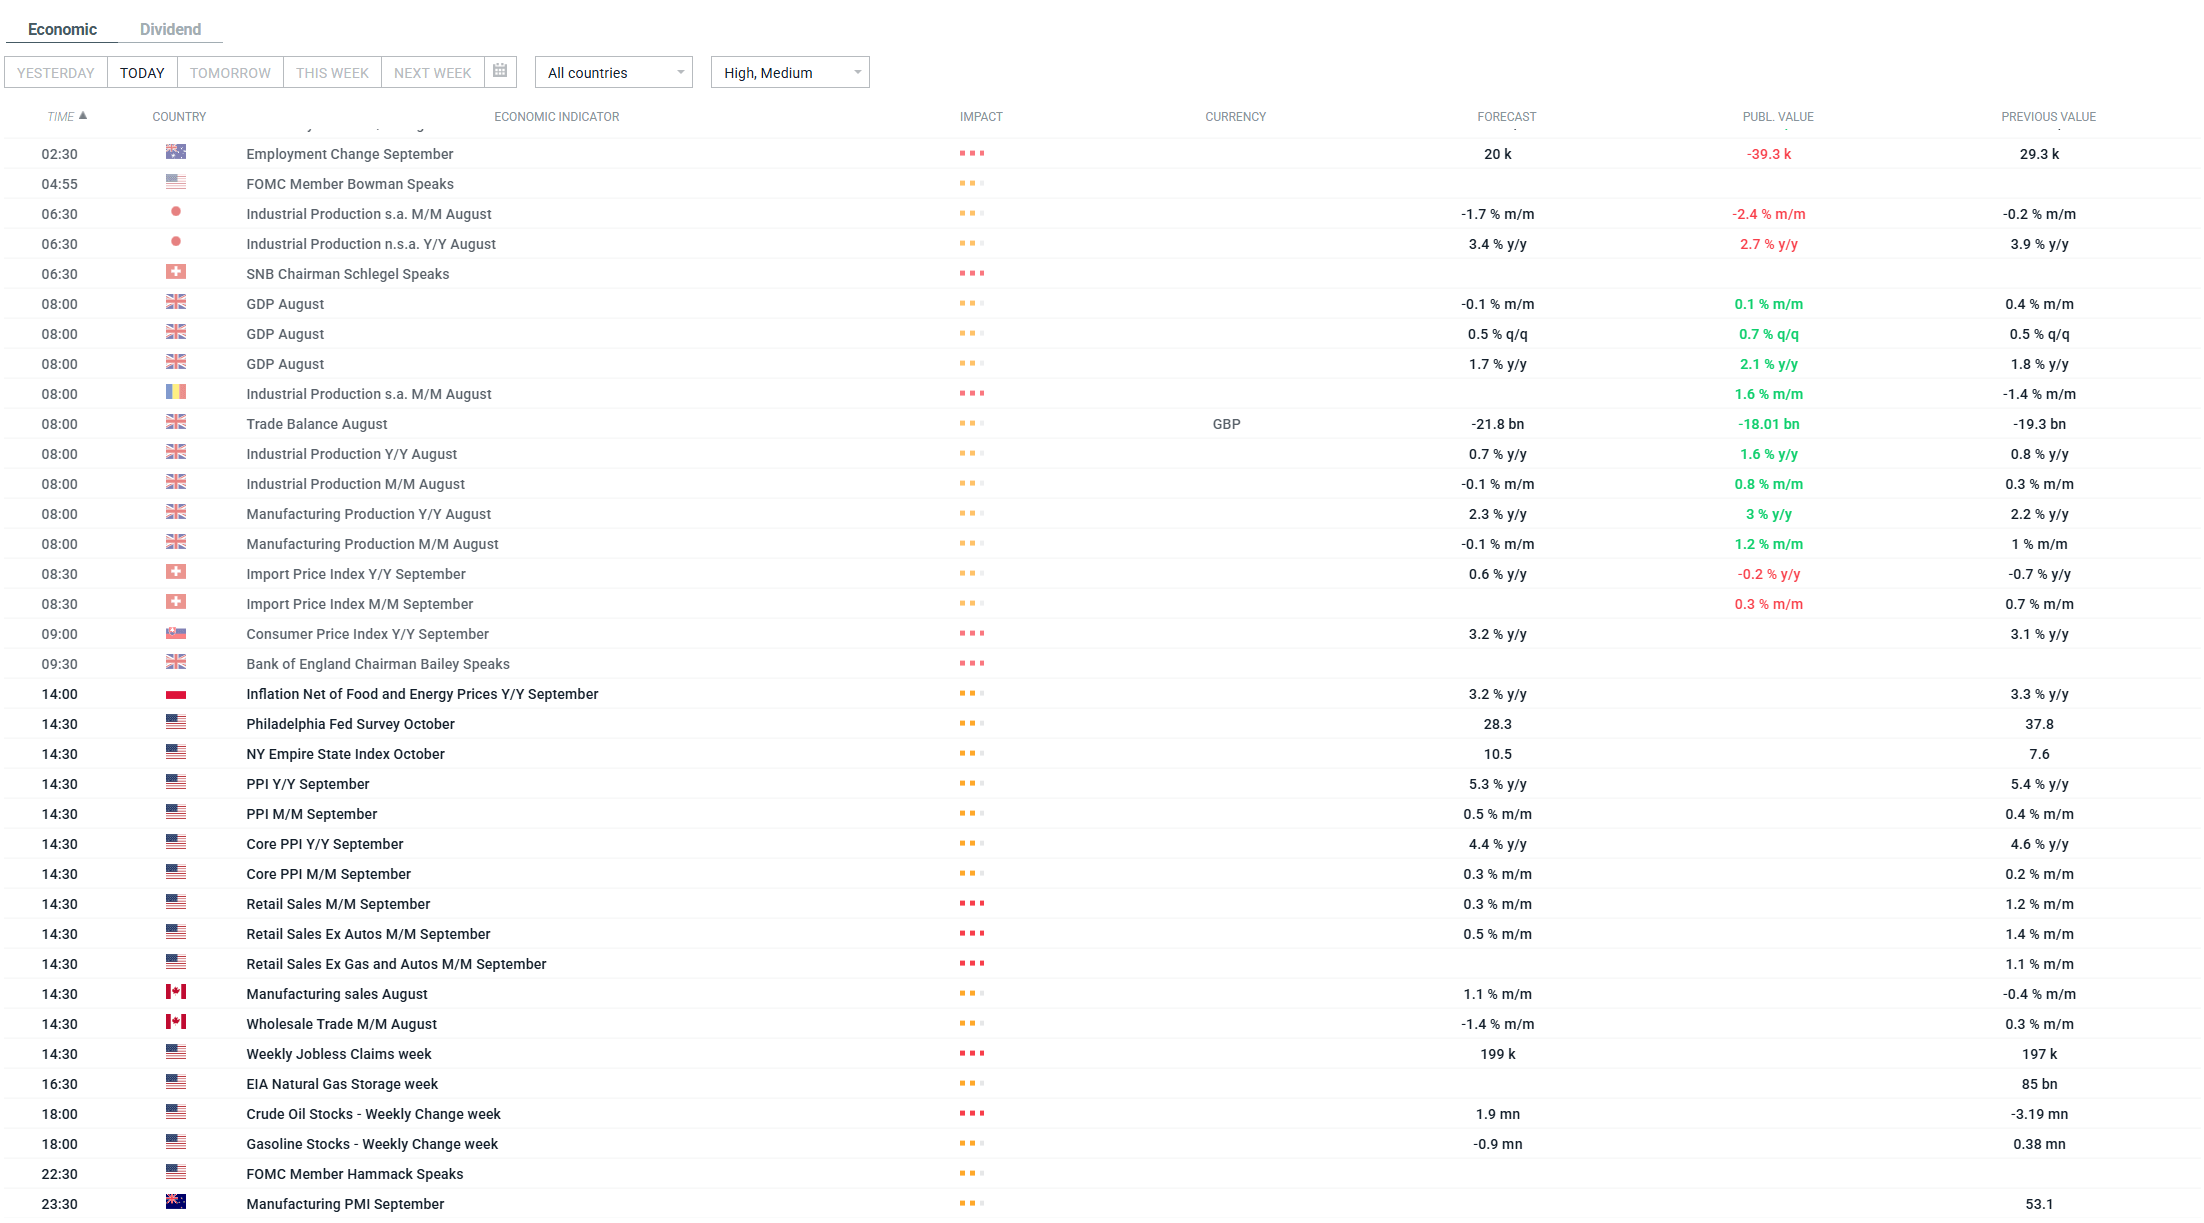
The key macroeconomic release is still ahead of us—at 2:30 p.m., we’ll see a full set of U.S. data: September’s PPI, retail sales, and weekly unemployment insurance claims. Following Tuesday’s hotter-than-expected CPI reading, these figures could further tip the balance of expectations regarding the Fed, with the market currently pricing in about a 29% chance of an October rate hike. It’s also worth keeping an eye on a series of speeches by Fed officials in Bangkok, including Federal Reserve Chairman Kevin Warsh.
On the earnings front, TSMC delivered a positive signal for the AI sector—its sixth consecutive record quarter, with net income up 68.7% year-over-year ($23.7 billion) and raised revenue forecasts for 2026. This is a strong counterargument to growing doubts about the profitability of AI spending, though for now it is not enough to reverse the morning’s defensive sentiment across the broader market.


🚨Morning Wrap: A weaker dollar, strong gold, and a tech sector in free fall—what’s driving the market❓

Daily Summary: Rising inflation weighs on markets, semiconductors suffer most (14.10.2026)


US Open: CPI reading weighs on American indices (14.10.2026)
US inflation concerns rise
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.