


- Australia reported a trade surplus of 0.50 billion AUD, falling short of the expected 2.00 billion AUD.
- Japanese manufacturing sentiment improved, though the Tankan index reading slightly missed consensus forecasts.
- Traders are focusing on US ISM manufacturing data and speeches from major central bank officials.
- The Asian session was marked by the release of the Japanese Tankan report and disappointing foreign trade data from Australia. Japanese manufacturing sentiment improved relative to the previous quarter, but the reading fell slightly short of forecasts, while the service sector saw a slight weakening.
- In turn, Australia's trade surplus shrank drastically to just AUD 0.50 billion compared to the expected AUD 2.00 billion, putting pressure on Antipodean currencies.
- During the day, investors will focus on the final manufacturing PMI readings from the Eurozone and the UK, and in the afternoon on the key US ISM manufacturing index and weekly jobless claims.
- The day is also characterized by an exceptionally dense schedule of public appearances by members of the FOMC (including Waller, Bowman, Jefferson), the ECB (Christine Lagarde), and Bank of England Governor Andrew Bailey. In China, it is a public holiday (bank holiday).
Key Releases from the Asian Session
- Japan: Tankan Index for manufacturing stood at 24 pts vs. 25 pts consensus and previous reading of 22 pts. Despite the quarterly improvement, the result slightly disappointed markets.
- Japan: Tankan Index for services fell to 35 pts (forecast: 36 pts, previous: 37 pts), indicating a moderate cooling of sentiment in the non-manufacturing sector.
- Japan: Final Manufacturing PMI reached 54.1 pts, perfectly matching the consensus and preliminary reading (54.1 pts), confirming solid expansion in the sector.
- Australia: Goods trade balance closed with a surplus of just AUD 0.50 billion vs. forecasted AUD 2.00 billion (previous: AUD 1.35 billion), impacted by strong import growth (+5.8%).
Macroeconomic Calendar
- All day China - Bank Holiday (market closed)
- 00:00 US - Speech by FOMC member Neel Kashkari
- 01:50 Japan - BOJ Summary of Opinions
- 03:30 Australia - RBA Financial Stability Review
- 08:00 UK - Nationwide House Price Index m/m. Consensus: 0.0%. Previous reading: 0.2%.
- 08:30 Australia - Commodity Prices y/y. Previous reading: 15.5%.
- 08:30 Switzerland - Consumer Price Index (CPI) m/m. Consensus: 0.0%. Previous reading: 0.4%.
- 08:30 Switzerland - Retail Sales y/y. Consensus: 2.1%. Previous reading: 2.3%.
- 09:15 Eurozone - Spain: Manufacturing PMI. Consensus: 50.2. Previous reading: 49.5.
- 09:50 Eurozone - France: Final Manufacturing PMI. Consensus: 50.3. Previous reading: 50.3.
- 09:55 Eurozone - Germany: Final Manufacturing PMI. Consensus: 53.8. Previous reading: 53.8.
- 10:00 Eurozone - Final Manufacturing PMI. Consensus: 52.7. Previous reading: 52.7.
- 10:00 Eurozone - Italy: Monthly Unemployment Rate. Consensus: 5.8%. Previous reading: 5.8%.
- 10:00 UK - Speech by BoE Governor Andrew Bailey
- 10:30 UK - Final Manufacturing PMI. Consensus: 52.0. Previous reading: 52.0.
- 11:00 Eurozone - Unemployment Rate. Consensus: 6.4%. Previous reading: 6.4%.
- 11:30 US - Challenger Job Cuts y/y. Previous reading: -38.5%.
- 12:35 Eurozone - Speech by Bundesbank President Joachim Nagel
- 14:00 UK - Speech by MPC member Catherine Mann
- 14:30 US - Weekly Jobless Claims. Consensus: 201k. Previous reading: 197k.
- 15:05 US - Speech by FOMC member Thomas Barkin
- 15:05 US - Speech by FOMC member Susan Collins
- 15:05 US - Speech by FOMC member Jeffrey Schmid
- 15:30 Canada - Manufacturing PMI. Previous reading: 53.0.
- 15:30 Eurozone - Speech by ECB President Christine Lagarde
- 15:45 US - Final Manufacturing PMI. Consensus: 56.9. Previous reading: 57.0.
- 16:00 US - Speech by FOMC member Christopher Waller
- 16:00 US - ISM Manufacturing Index. Consensus: 54.8. Previous reading: 54.6.
- 16:00 US - ISM Manufacturing Prices Paid Sub-index. Consensus: 72.9. Previous reading: 71.1.
- 16:30 US - Natural Gas Storage Change. Consensus: 63 billion cubic feet (bcf). Previous reading: 53 billion cubic feet (bcf).
- 17:30 Switzerland - Speech by SNB President Martin Schlegel
- 19:30 US - Speech by FOMC Vice Chair Philip Jefferson
- 21:00 US - Speech by FOMC member Michelle Bowman
- 21:05 Canada - Speech by BoC Senior Deputy Governor Carolyn Rogers
- 21:30 US - Speech by FOMC member Lisa Cook
Corporate Earnings
- Accenture (before market open)
- Nike (after market close)
Markets to Watch
- USDJPY — The pair is rising towards the 158.20 level due to monetary divergence and weaker-than-expected Tankan readings, and today's series of speeches by Federal Reserve members as well as the ISM index could trigger increased volatility.
- AUDUSD — The Australian dollar remains under heavy pressure following a worse-than-projected August trade balance (surplus of just AUD 495 million vs. expected AUD 2 billion) and amid concerns over commodity market health and the absence of Chinese investors.
- EURUSD — The European currency will react to a series of final manufacturing PMI readings from key Eurozone economies and Christine Lagarde's speech at 15:30, before facing key US ISM data.
USDJPY: Technical Analysis (D1)
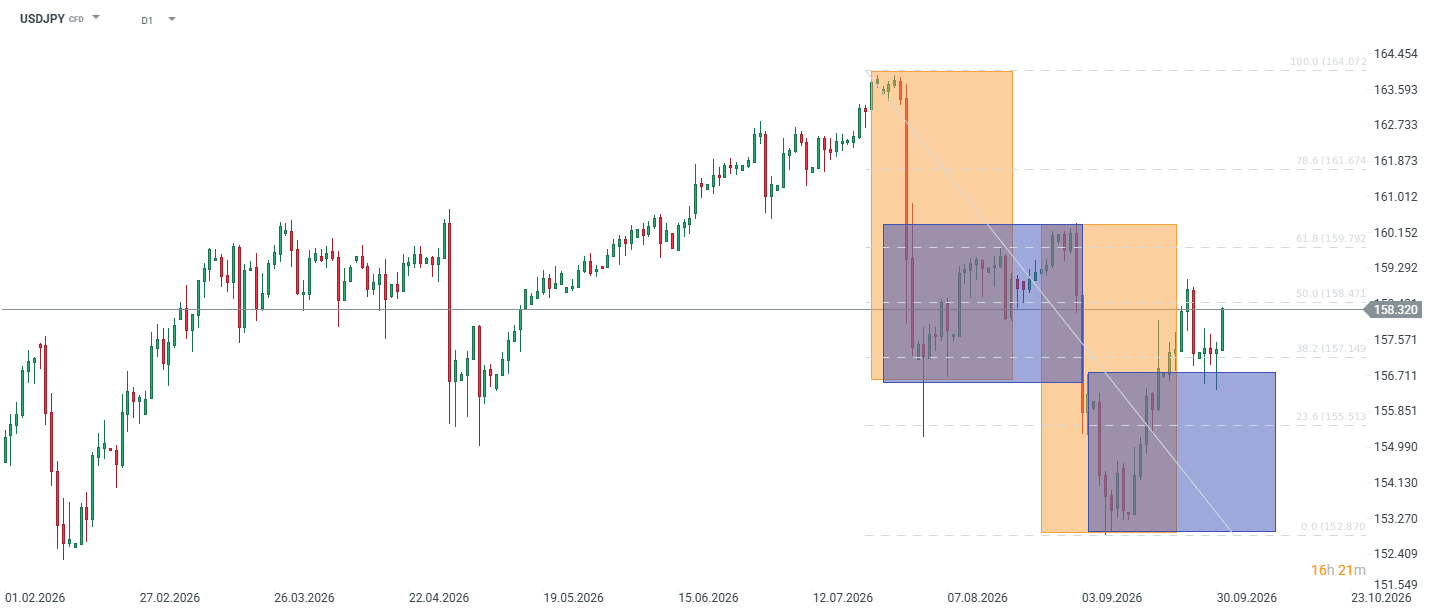
The pair is defending the support zone at the 38.2% Fibonacci retracement level (157.15) of the entire downward movement from 164.07 to 152.87. The reaction is visible as the price rebounds and returns to 158.32, right around the 50% retracement level at 158.47.
After peaking in mid-July, the market dropped to 152.87 in early September before initiating a rebound that halted at 160.15 near the 61.8 percent retracement (159.79). Another downward wave brought quotes back down to 38.2%, where demand re-emerged.
As long as 157.15 remains intact on daily closes, the initiative belongs to the buyers. The nearest resistance is 158.47, and overcoming it opens the way to 159.79 and the peak at 160.15. Losing support, on the other hand, means testing 155.51 (23.6 percent retracement), and lower down, the September low at 152.87.


Morning Wrap: Tech Rally in Asia Following Micron Results and Weakening Yen Despite Hawkish BoJ



📊Daily Summary: PCE inflation slowdown brings relief to Wall Street, but oil continues gains despite return of supply

⚪Platinum: surplus returns after three years of deficit, and price falls below key support. Is there a chance for recovery?

BREAKING: Drop in distillate stocks encourages oil to rebound
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.