


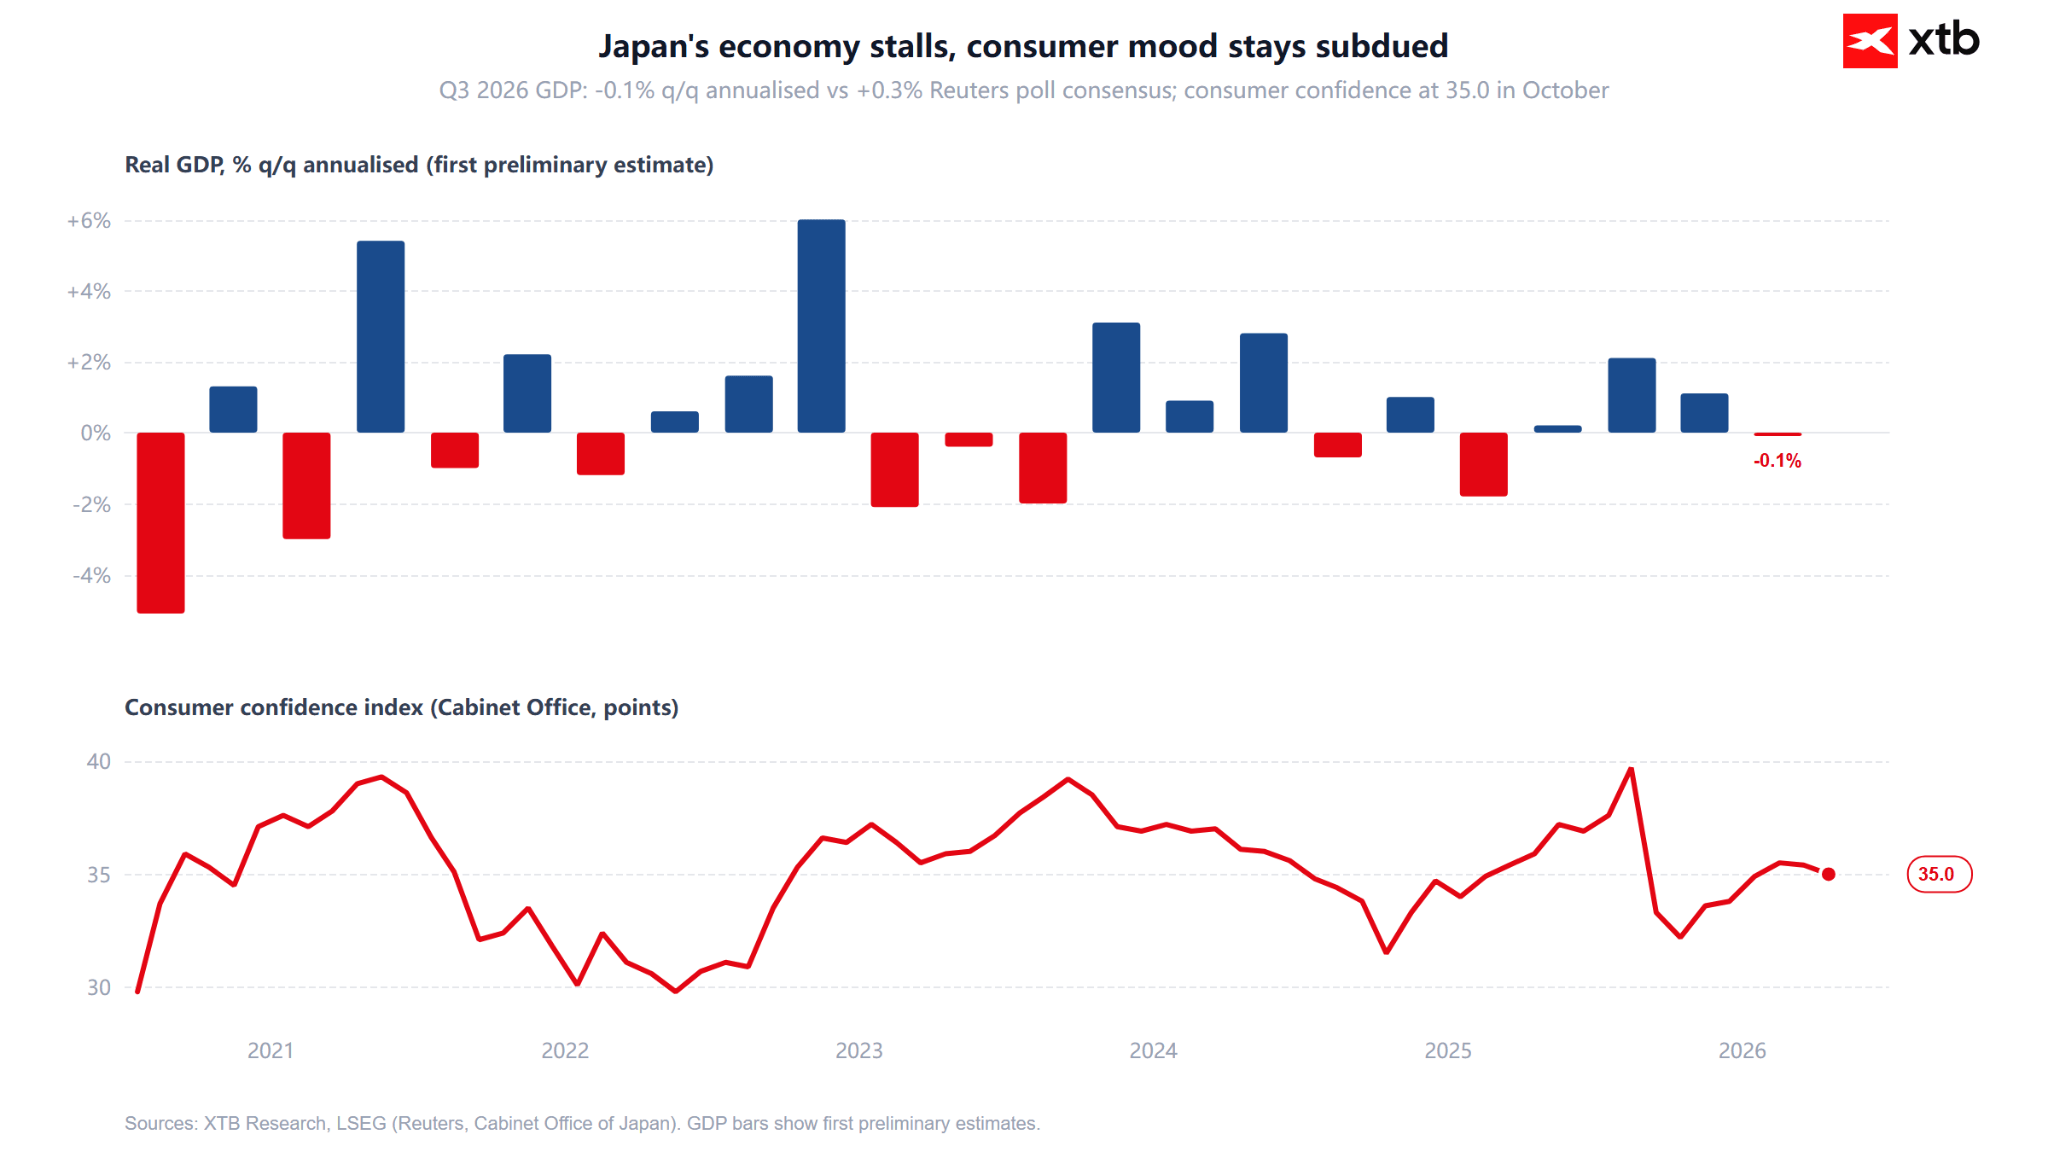
The beginning of the week is marked by a clear cooling of macroeconomic data from Asia and rising geopolitical tensions. The published data package from China turned out to be a disappointment: industrial production and retail sales growth slowed significantly, and the decline in fixed-asset investment deepened, signaling weakening domestic demand despite government stimulus efforts. Meanwhile, preliminary GDP for Japan for the past quarter indicated economic stagnation (0.0% q/q), although hawkish statements from Bank of Japan board member Hajime Takata suggest readiness for further interest rate hikes to bring them closer to a neutral level.
In the commodities market, attention is focused on reports from the Middle East, where incidents involving oil tankers hitting sea mines occurred in the eastern part of the Strait of Hormuz, pushing up the risk premium on the crude oil market. Later today, investors will concentrate on European industrial production, the CPI inflation data package from Canada (crucial for the Bank of Canada's interest rate path), and numerous speeches by Federal Reserve officials, including an evening speech by the Fed Chair.
Key Releases from the Asian Session
- Japan: Preliminary Q3 GDP slowed to 0.0% q/q (consensus: 0.1%, previous: 0.4%), signaling a lack of economic growth and faltering private consumption.
- Japan: Preliminary GDP Price Index rose by 2.4% y/y, below market expectations of 2.6% y/y (previous: 2.6% y/y), indicating slightly weaker price pressure in the economy.
- Japan: Revised industrial production rose in September by 2.0% m/m (consensus and preliminary reading: 2.2% m/m), confirming a moderate recovery in the manufacturing sector, but below initial estimates.
- China: Retail sales grew in October by just 0.4% y/y compared to expected 0.8% y/y and 1.1% y/y previously, confirming continued weakness in Chinese consumer sentiment.
- China: Industrial production increased by 4.8% y/y, missing forecasts of 5.3% y/y (previous: 5.5% y/y), reflecting a slowdown in foreign and domestic demand.
- China: Fixed-asset investment fell year-to-date by 8.1% y/y (consensus: -7.0% y/y, previous: -7.2% y/y), indicating a deepening investment crisis in the property and industrial sectors.
- China: New home prices fell in October by 0.15% m/m (previous: -0.14% m/m), confirming the lack of a sustainable bottom in the real estate market.
- China: Urban unemployment rate dropped slightly to 5.1% (consensus and previous: 5.2%), providing the only relatively stable element in today's data set.
Macroeconomic Calendar
- 03:00 China - National Bureau of Statistics (NBS) Press Conference
- 11:00 Eurozone - Industrial Production m/m. Consensus: 0.3%. Previous reading: -0.5%.
- 11:00 USA - Speech by Fed Board Member (Michael Barr)
- 14:30 Canada - Consumer Price Index (CPI) m/m. Consensus: 0.3%. Previous reading: 0.1%.
- 14:30 Canada - Median CPI y/y. Consensus: 2.0%. Previous reading: 1.9%.
- 14:30 Canada - Trimmed CPI y/y. Consensus: 1.9%. Previous reading: 1.8%.
- 14:30 Canada - Common CPI y/y. Consensus: 2.5%. Previous reading: 2.4%.
- 14:30 Canada - Core CPI m/m. Consensus: 0.2%. Previous reading: 0.0%.
- 14:30 USA - New York Empire State Manufacturing Index. Consensus: 17.6. Previous reading: 25.5.
- 15:05 USA - Speech by New York Fed President (John Williams)
- 18:00 USA - Speech by Fed Chair (Kevin Warsh)
- 20:15 USA - Speech by Cleveland Fed President (Beth Hammack)
- 21:00 New Zealand - RBNZ Financial Stability Report
- 22:45 New Zealand - Food Price Index (FPI) m/m. Previous reading: 0.0%.
23:50 Australia - Speech by RBA Governor (Michele Bullock)
Corporate Earnings
- Trip.com Group Limited (TCOM) – release during the day, EPS forecast: $1.07; key barometer of Chinese consumer spending on tourism and international travel.
- Baidu, Inc. (BIDU) – pre-market, EPS forecast: $0.57; important test of AI technology monetization and online advertising demand in China.
- Tyson Foods, Inc. (TSN) – pre-market, EPS forecast: $0.65; indicator of cost pressure in the food market and the health of US household budgets.
Markets to Watch
- Crude Oil (Brent / WTI) – explosions of two tankers in the Strait of Hormuz area due to hitting sea mines create a direct risk of disruption at a crucial global transit point, supporting oil prices and raising questions about maritime route safety.
- Canadian Dollar (CAD / USDCAD) – release of the comprehensive October inflation package will be crucial for expectations regarding the Bank of Canada's next steps; core metrics (median and trimmed CPI) rising above consensus could limit expectations of further aggressive rate cuts and strengthen the "Loonie".
- US Dollar (USD) and US Bond Yields – a series of scheduled speeches by Federal Reserve representatives, led by Williams and Warsh, as well as the regional Empire State reading will test market pricing regarding the December FOMC rate decision.



Daily Summary: PPI Inflation slows down, but EURUSD approaches 1.10



Three Markets to Watch Next Week (13.11.2026)


Economic Calendar: U.S. PPI inflation takes center stage. What will today's session bring❓


Daily Summary: Oil Rebounds, EURUSD Falls Sharply 🗽 Wall Street Stabilizes After Nvidia Sell-Off
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.