


European index futures are posting modest gains but remain close to two-month lows and are heading for their weakest week since April 2026. Investors are concerned about the combination of high energy prices, higher interest rates and the risk of stagflation. The Stoxx Europe 600 is up around 0.5% today but is down more than 2% for the week. The DAX and FTSE 100 are both gaining around 0.5%, while the CAC 40 is up approximately 0.6%. Oil prices remain the main source of pressure. Brent crude rose to around $110 per barrel overnight on Friday, its highest level in four months, and despite pulling back toward $105, it is still up more than 10% this week amid the risk of further supply disruptions.
Key developments in Europe
-
Tanker traffic through the Persian Gulf remains heavily restricted following direct clashes between U.S. forces and the Iranian navy, while the seizure of Yemen’s Mocha port by Iran-backed Houthis increases the threat to Saudi oil export routes in the Red Sea.
-
The ECB raised its deposit rate by 25 bp on Thursday to 2.50%, the highest level since April 2025. The decision highlights the central bank’s growing concerns that rising commodity prices could spill over into core inflation.
-
Eurozone CPI inflation accelerated to 3.3% y/y in August, with energy prices rising 14.3%. Money markets are currently pricing in a probability of more than 90% for a third ECB rate hike before year-end. Despite this, EURUSD remains relatively flat today.
-
Higher bond yields and rising production costs have hit growth, industrial and consumer stocks particularly hard, increasing pressure on European equities in recent days alongside weakness in Wall Street indices.
-
Global investors are focused today on U.S. CPI data at 14:30. Following a strong NFP report showing employment growth of 162,000, a higher-than-expected inflation reading could further strengthen expectations for a Fed rate hike at its September 16 meeting.
-
In individual stocks, Vetoquinol is up 16% despite a 22% y/y increase in first-half net profit, flatexDEGIRO is down 5% following the resignation of its supervisory board chairman, while Alstom is gaining around 2.2% after securing contracts worth more than €1.2 billion.
UK data surprise analysts
UK GDP rose 0.4% m/m versus expectations of 0.0% and 0.3% previously. Sterling strengthened against the U.S. dollar as the improvement visible in today’s UK data was broad-based.
-
On a 3M/3M basis, GDP rose 0.4% versus a forecast of 0.3% and 0.4% previously.
-
GDP increased 1.6% y/y versus expectations of 1.0% and 1.1% previously.
-
UK industrial production rose 0.2% m/m in August versus an expected decline of 0.2% and a previous drop of 0.2%.
-
Industrial production increased 0.6% y/y versus a forecast of 0.2% and a previous decline of 0.2%.
-
Manufacturing production rose 0.9% m/m versus expectations of 0.2% and a previous decline of 0.5%.
-
Manufacturing production increased 2.6% y/y versus 0.5% previously.
-
The goods trade balance came in at -£20.96 billion versus expectations of -£22.4 billion and -£23.01 billion previously.
-
The non-EU goods trade balance came in at -£9.66 billion versus -£10.45 billion previously.
-
Construction output increased 0.1% m/m versus expectations of 0.1% and a previous decline of 0.1%.
-
Services output rose 0.4% m/m versus 0.0% previously.
UK data came in clearly stronger than expected, indicating that the economy entered the second half of the year with more momentum than the consensus had anticipated. GDP rose 0.4% m/m in August versus expectations of stagnation, while the 1.6% y/y growth rate significantly exceeded the 1.0% forecast, reducing concerns about a sharp slowdown in activity. Manufacturing stood out particularly positively, with output rising 0.9% m/m and 2.6% y/y, suggesting that the improvement in economic conditions is not limited solely to the services sector. Another positive signal is the narrowing of the trade deficit, although its level remains high and continues to represent a structural weakness of the UK economy. From a market perspective, the data set is supportive for sterling and may limit the Bank of England’s room for rapid monetary easing, particularly if resilient economic growth is accompanied by persistent inflationary pressure.
GBPUSD chart (H1 interval)

Source: xStation5
Alstom secures contracts worth more than €1.2 billion in the UK
European rail industry giant Alstom has signed contracts with TransPennine Express worth a combined more than €1.2 billion for the supply and long-term maintenance of a new fleet of battery-electric trains in northern England. The agreement includes the delivery of 29 five-car BEMU trainsets worth around €930 million and maintenance contracts valued at approximately €230 million.
The new trains, designed and manufactured in the UK, will mark the first deployment of the Adessia platform in the British market and are intended to support the Transpennine Route Upgrade and the decarbonisation of rail transport.
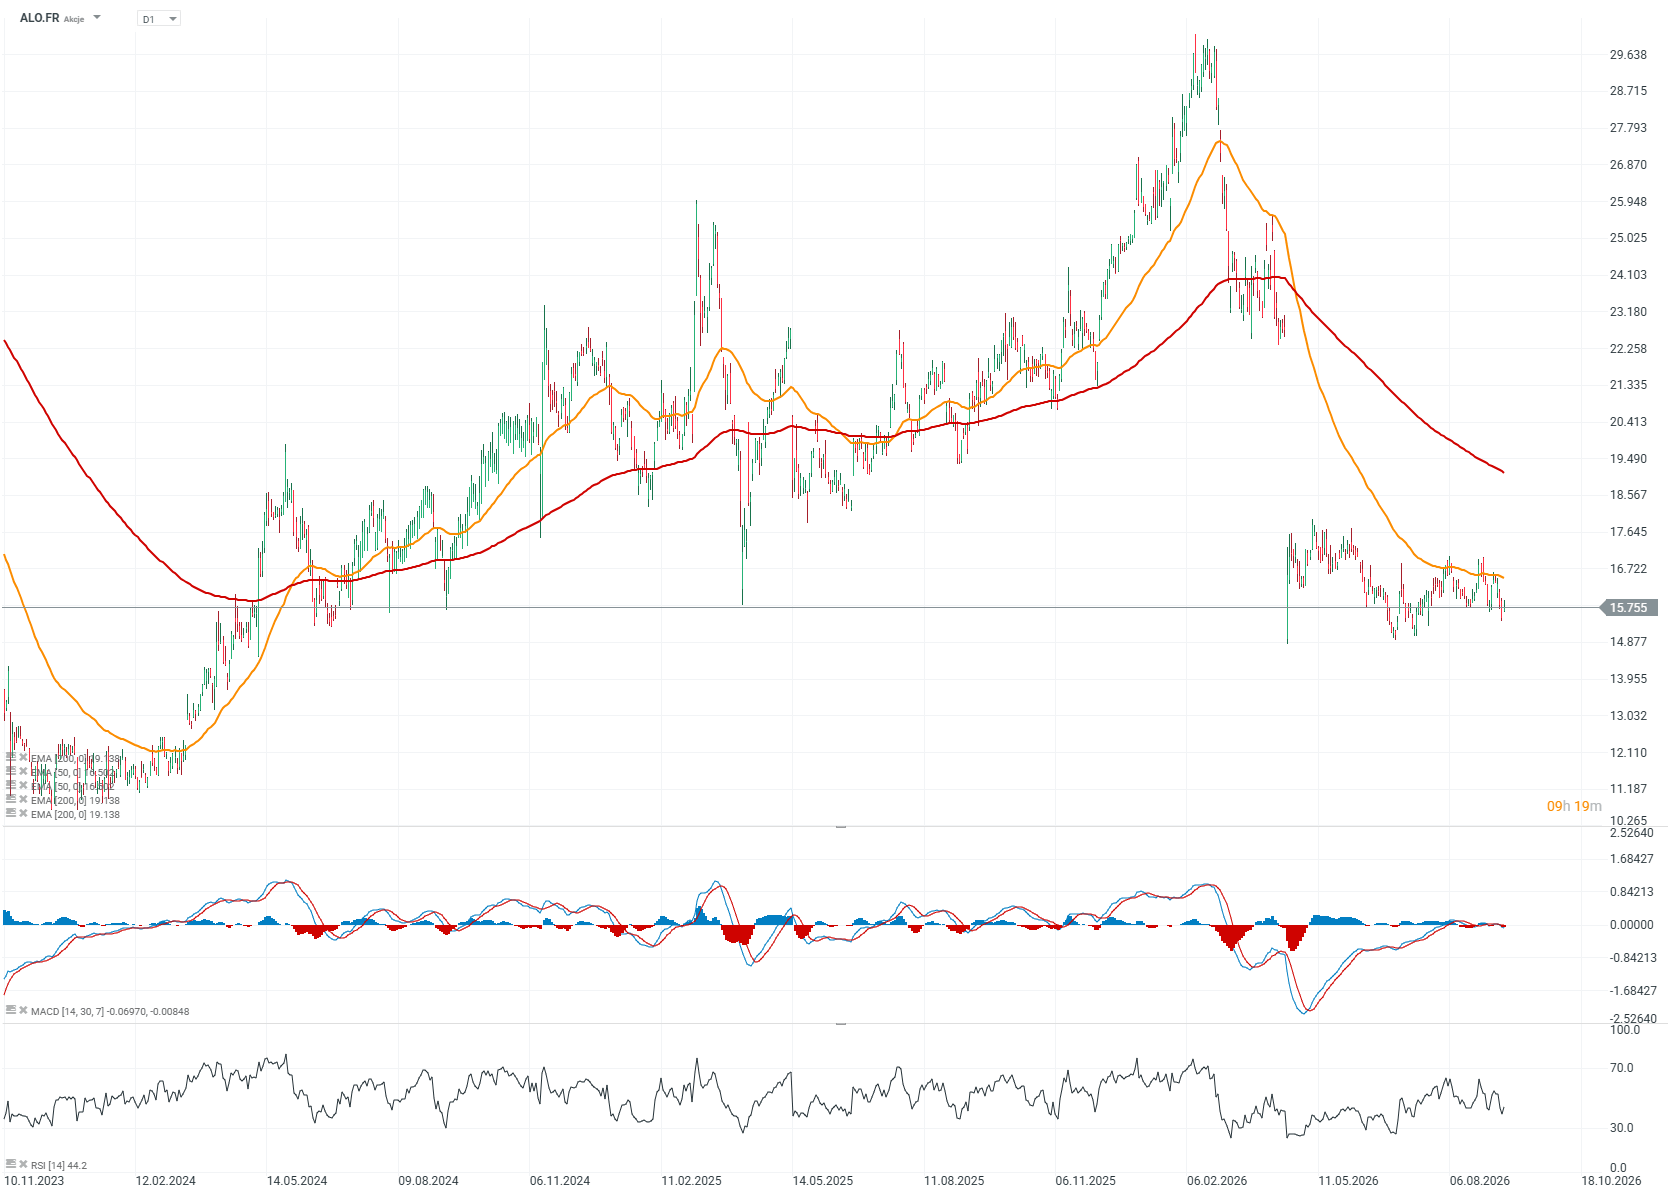
Deliveries are expected to begin in 2032, while the project also includes charging infrastructure and maintenance, demonstrating the broad scope of Alstom’s capabilities in delivering comprehensive rail projects. Alstom shares are still trading around 50% below their February 2026 highs.
Alstom chart (ALO.FR), D1 interval
The stock’s reaction to the contract appears very muted and has failed to reverse sentiment around the company’s shares. The stock is trading around 20% below its 200-day EMA and has remained in a deep downtrend since the spring of this year.
Source: xStation5

EURUSD extends its decline 📉 Are high energy prices weighing on Europe?

⛩️Chart of the Day: JP225, Nikkei Plays Its Own Tune (01.10.2026)

Eurozone Manufacturing Shows Slightly Better Final PMI Data 💡

📉 NATGAS falls 1.2%. What about winter?
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.