


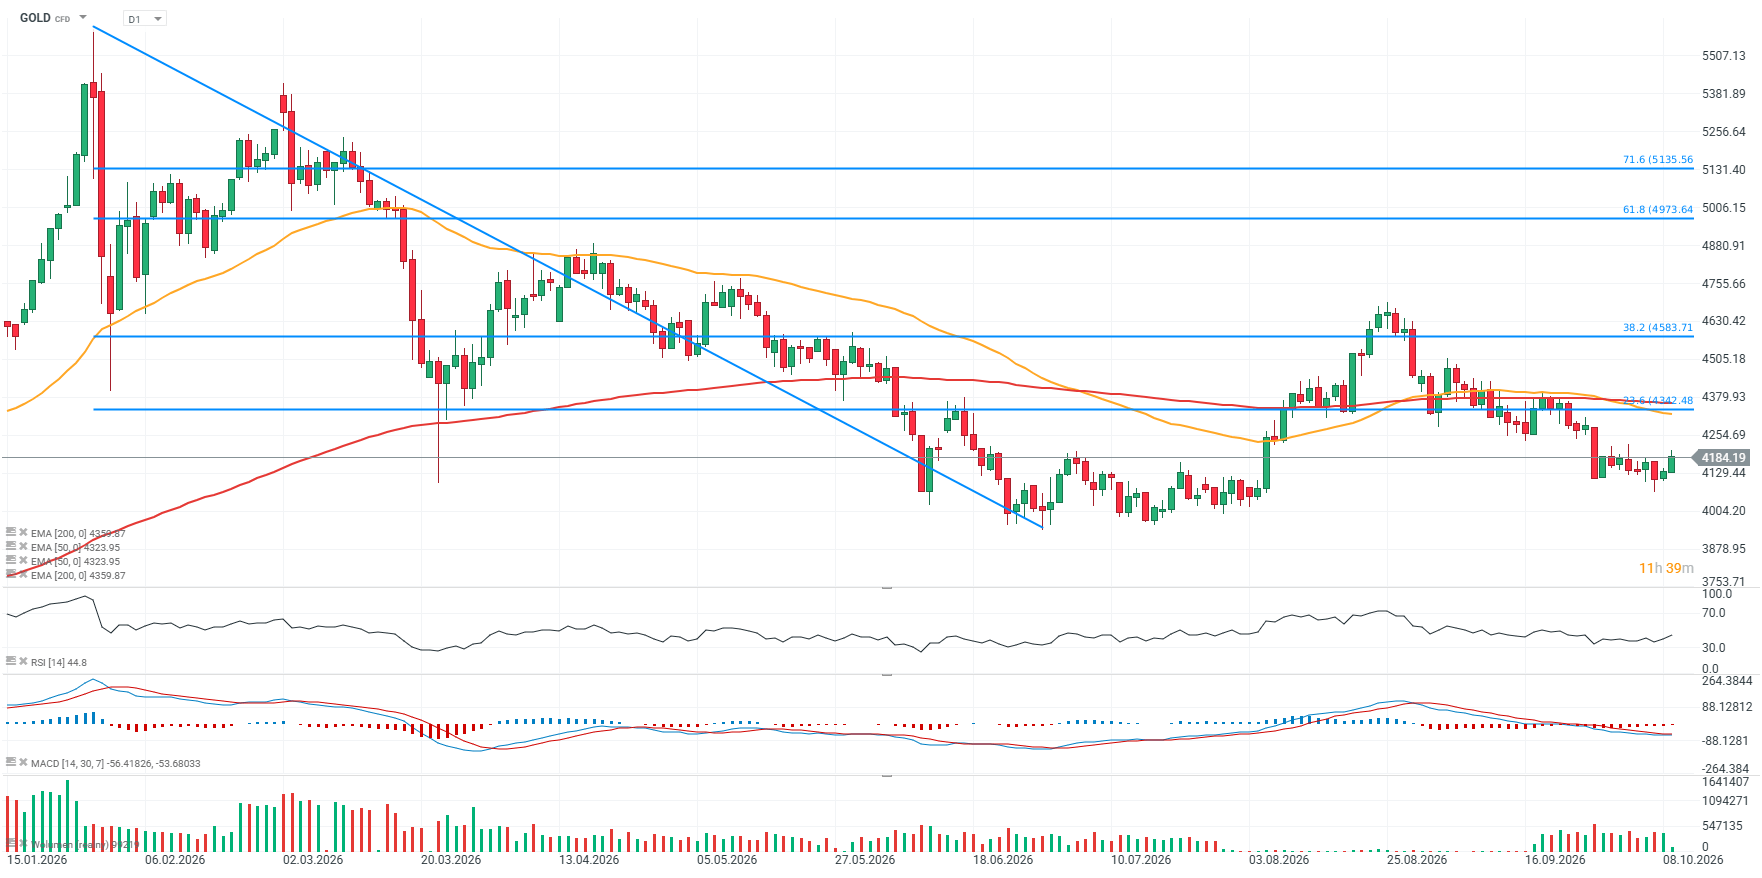
Gold (GOLD) is up nearly 1.2% today, having gained as much as 1.5% at the session high as it attempts to move back toward $4,200 per ounce. The metal appears to have formed a local bottom around $4,070–4,150 per ounce, with investors now trying to push prices out of a multi-day consolidation around these levels. Platinum and silver are both up around 2%, while a modestly stronger dollar and a slight rise in yields are not preventing precious metals from advancing today.
- Gold is stabilizing after its recent decline to the lowest level since early August, although the high US Dollar Index and elevated bond yields continue to exert pressure on precious metals. US Treasury yields remained elevated yesterday for a second consecutive session.
- At the same time, growing concerns over the high level of US debt may work in the opposite direction and support demand for gold as an alternative to fiat currencies and government assets. US Treasury yields remain high, but have fallen to around 5.25% from the local peak of 5.35% seen on Wednesday.
- The Fed minutes showed divisions among policymakers over the rationale for the September rate hike. Some participants focused on inflation risks stemming from price shocks, while a more hawkish group was also concerned about demand-driven inflation.
- The market is unable to identify a predetermined path for future Fed decisions, increasing uncertainty around gold and potentially keeping volatility elevated.
- Further rate hikes remain possible, although the pace of tightening may be flexible. The market is pricing in around a 17% probability of a hike in October and roughly an 81% chance of an increase in December.
- Geopolitical risks surrounding the Strait of Hormuz also remain in the background. The growing risk of attacks and shipping disruptions may increase demand for safe-haven assets, although a potential rise in energy prices could also keep inflationary pressure elevated and reinforce hawkish expectations for the Fed.
- The overall market picture is therefore mixed: high yields and a strong dollar are negative for gold, while concerns over US debt, uncertainty surrounding Fed policy, geopolitical tensions, and continued buying by central banks and ETFs provide support for demand for the metal.
GOLD (D1 timeframe)
 Source: xStation5
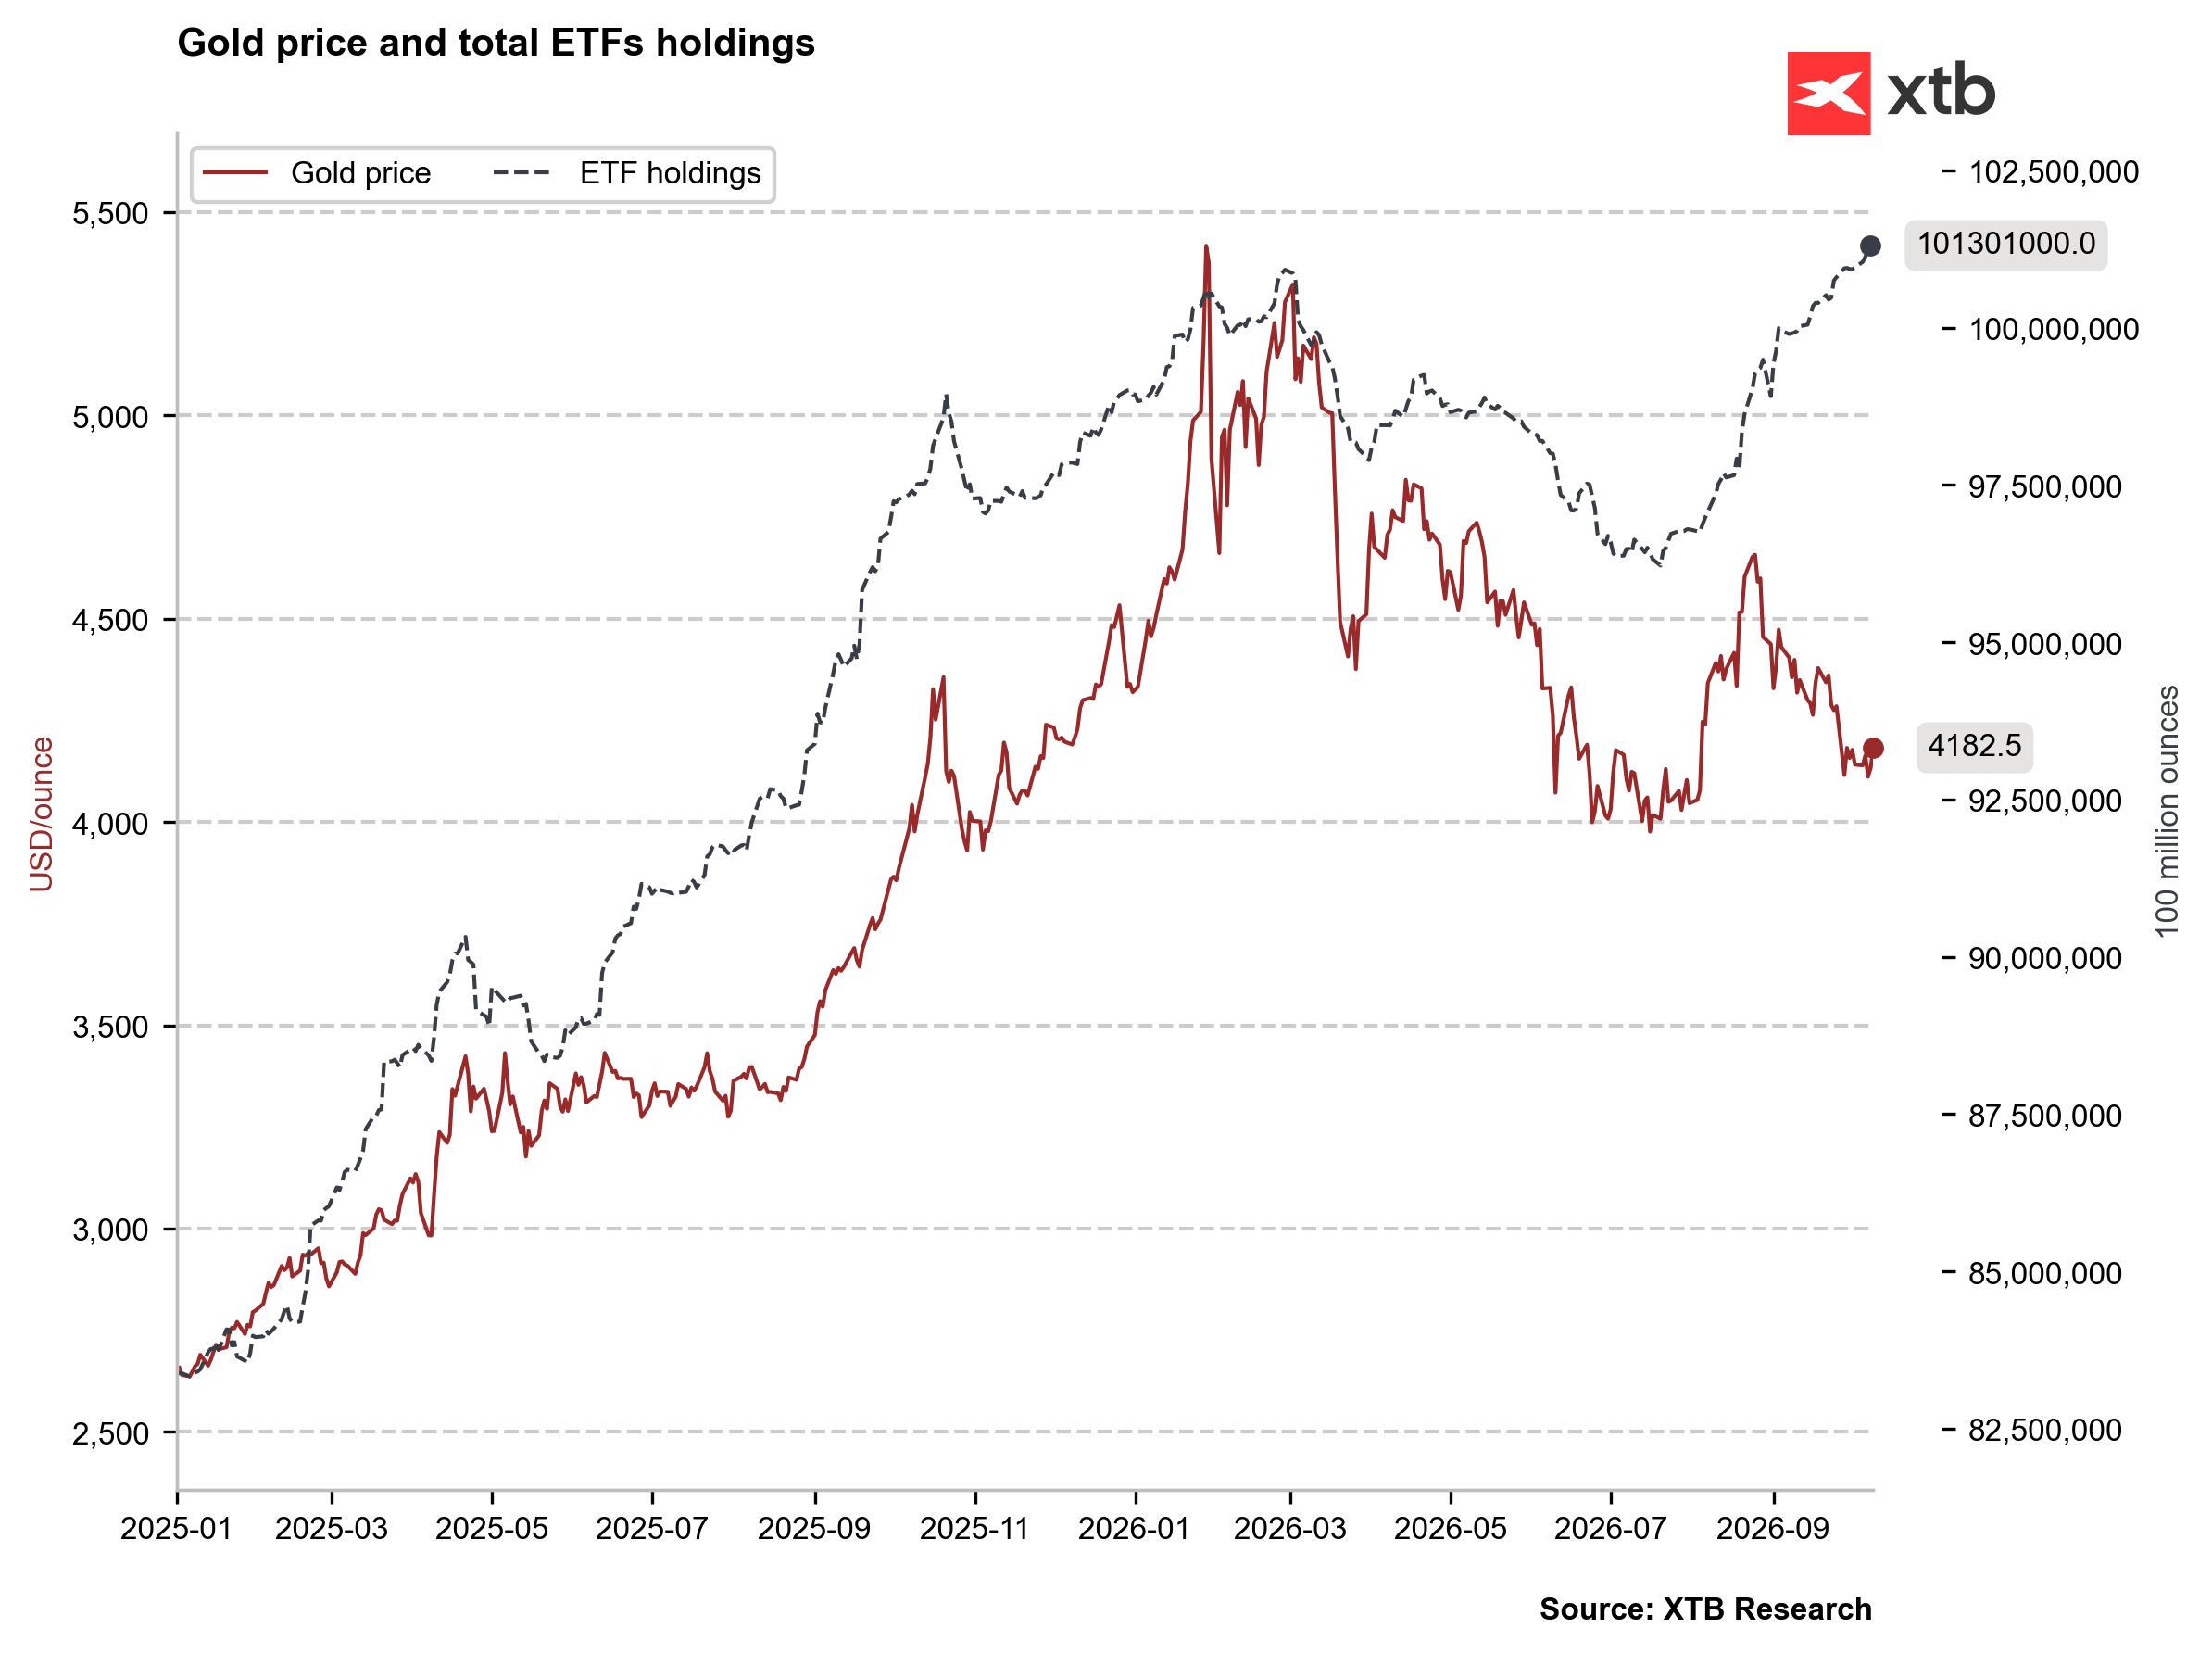
Gold price vs ETF holdings
The chart shows a clear divergence between the gold price and investor positioning through ETFs. While the metal has pulled back from this year’s highs toward around $4,200 per ounce, total gold holdings in ETFs have risen to fresh local highs above 101 million ounces. This suggests that some longer-term capital is using the decline in prices to increase exposure rather than reducing positions alongside the market. Such a setup can be interpreted as relatively constructive over the medium term, as ETF flows are not confirming the current weakness in price. At the same time, high ETF holdings alone do not guarantee a rebound, as short-term pricing may still be driven by the dollar, bond yields and expectations surrounding the Fed. The key question is therefore whether continued ETF inflows will eventually translate into stronger physical demand and renewed price momentum.
 Source: XTB Research
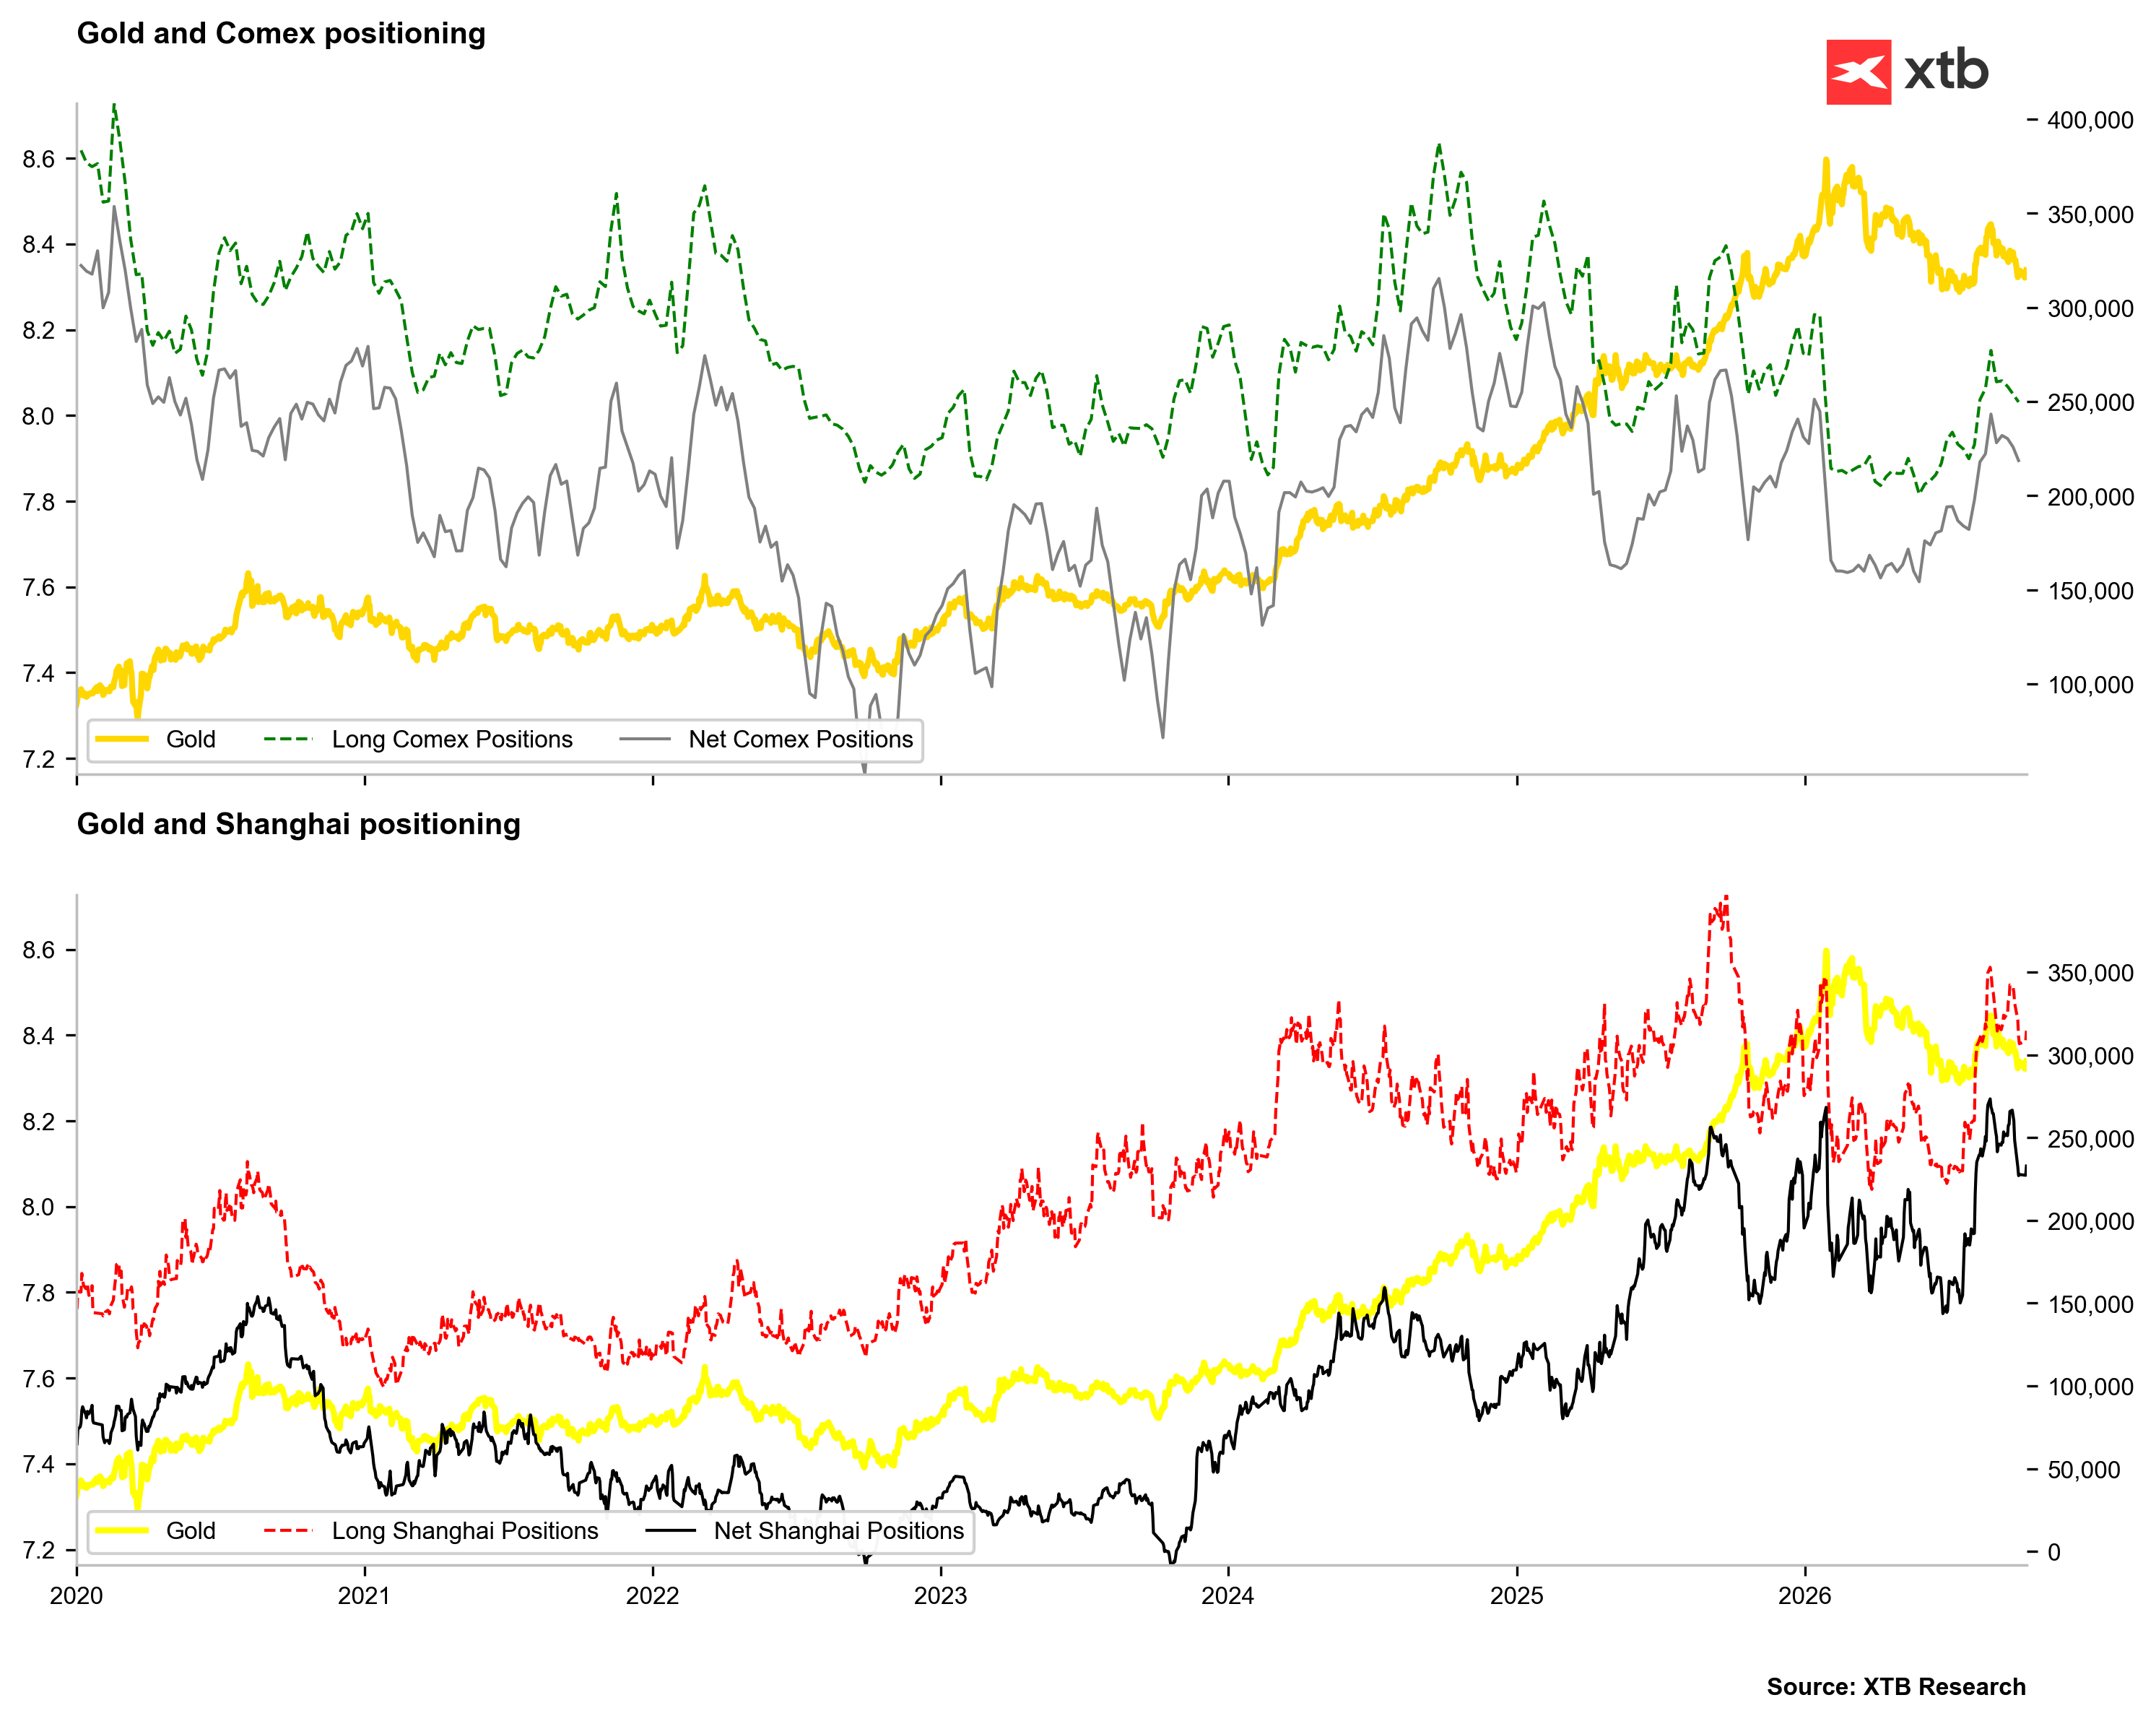
Gold positioning (COMEX/Shanghai)
Positioning on COMEX remains relatively elevated, but is no longer near the extremes seen during previous phases of strong gold appreciation, suggesting that some speculative optimism has already been reduced. Both long positions and net positioning on COMEX have rebounded from this year’s lows, but remain below local peaks, which may limit the risk of sharp deleveraging in the event of another sell-off. The Shanghai market looks even more interesting, where both long and net positions remain elevated relative to most of the period since 2020, pointing to persistently strong demand from Asian investors. The divergence between relatively cooler positioning on COMEX and stronger positioning in Shanghai may indicate that Western capital is more sensitive to interest rates and the US dollar, while Asian demand remains relatively resilient. This setup is moderately constructive, as it reduces the risk of extreme positioning while also showing that structural demand for the metal has not disappeared.
 Source: XTB Research

Nasdaq tries to recover losses 📈 Was the OpenAI revenue scare overdone?

Chart of the Day: EURUSD Stages a Rebound, but France and the Fed Could Cap the Upside


Economic Calendar: Canada’s Jobs Report in Focus


Morning Wrap: OpenAI Revenue Concerns Weigh on Wall Street
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.