


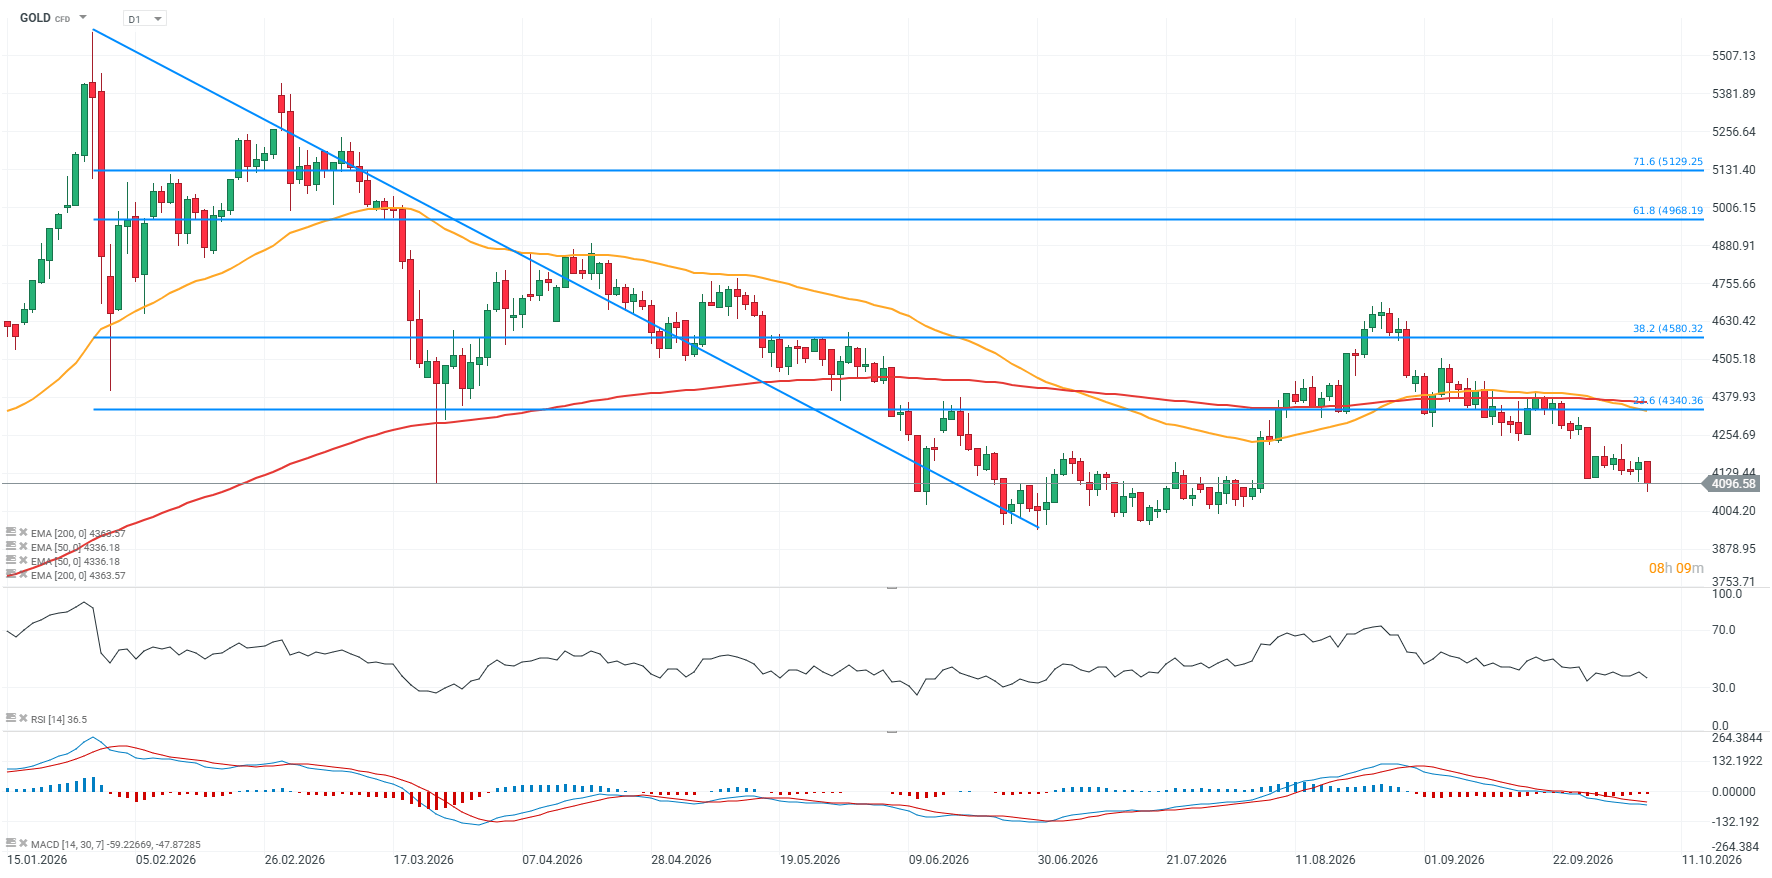
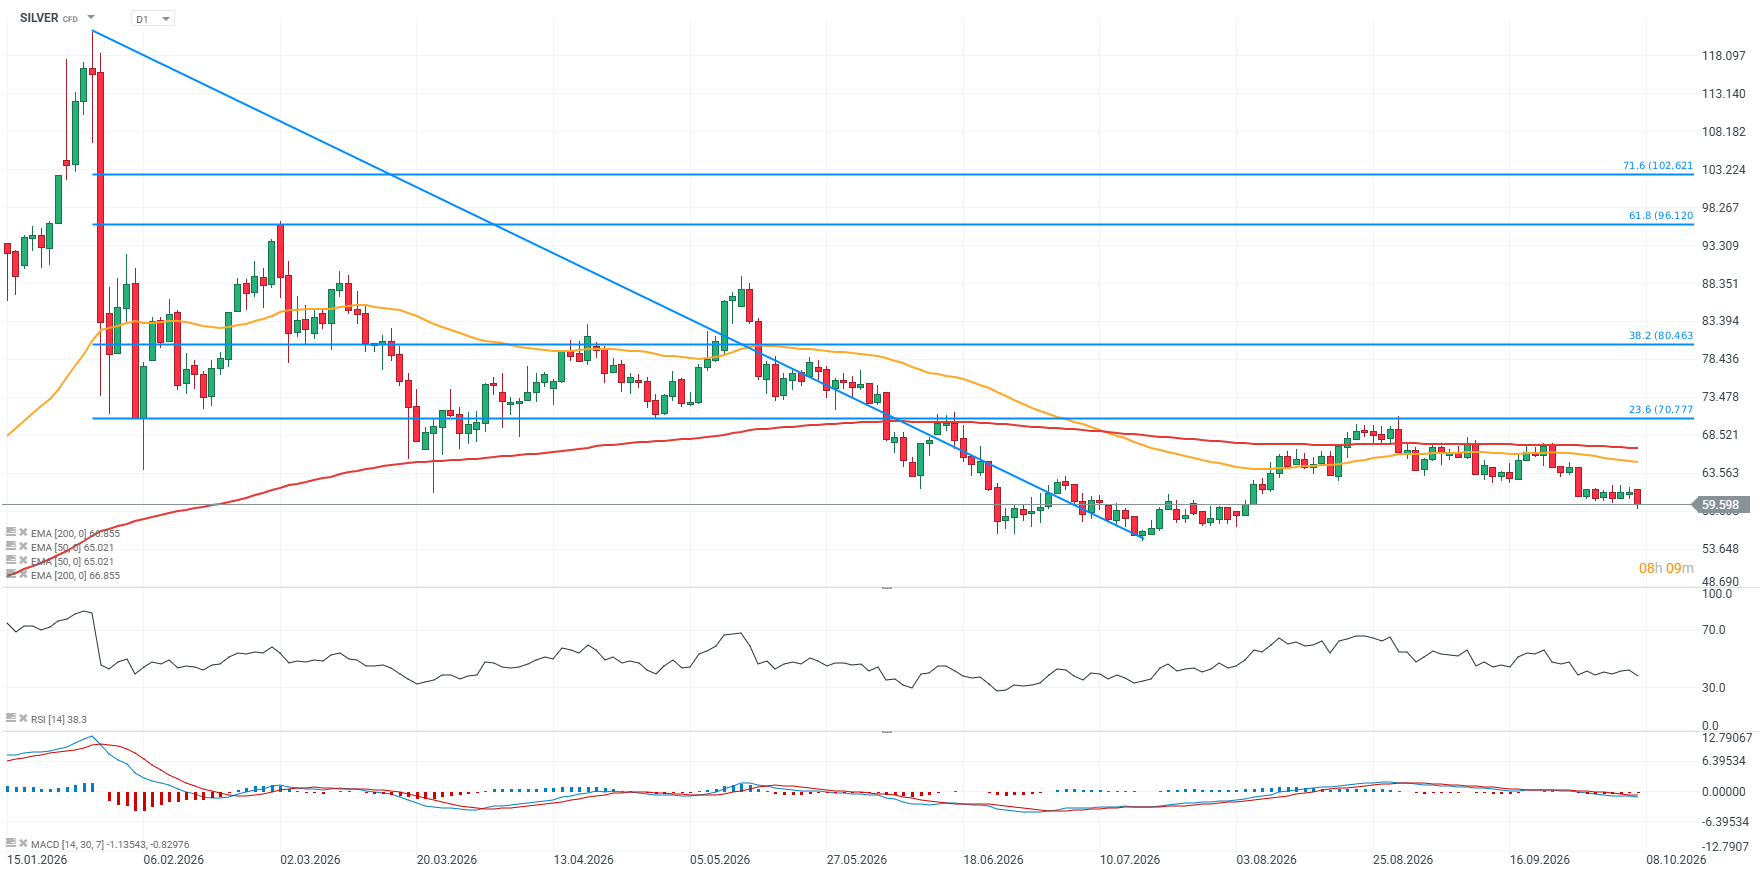
Gold is down nearly 2% today, falling below $4,100 per ounce, while silver is selling off by almost 3% and has slipped back below $60 per ounce. There are two main reasons behind the move. The first is that oil prices are rising again across global markets, even as tanker traffic through the Strait of Hormuz continues to normalize.
-
In addition, the yield on the 10-year US Treasury rose by nearly 8 basis points on Wednesday to around 5.35%, its highest level since April 2002. Such elevated yields increase financing costs across the economy and can weigh on non-yielding assets such as gold and Bitcoin.
-
Although inflows into gold-backed ETFs have increased recently and central banks continue to signal further purchases, this has so far failed to translate into higher prices. Almost the entire rally since August has now been erased, while investors are increasingly concerned about the prospect of further US rate hikes.
GOLD and SILVER charts (D1 timeframe)
 Source: xStation5
 Source: xStation5
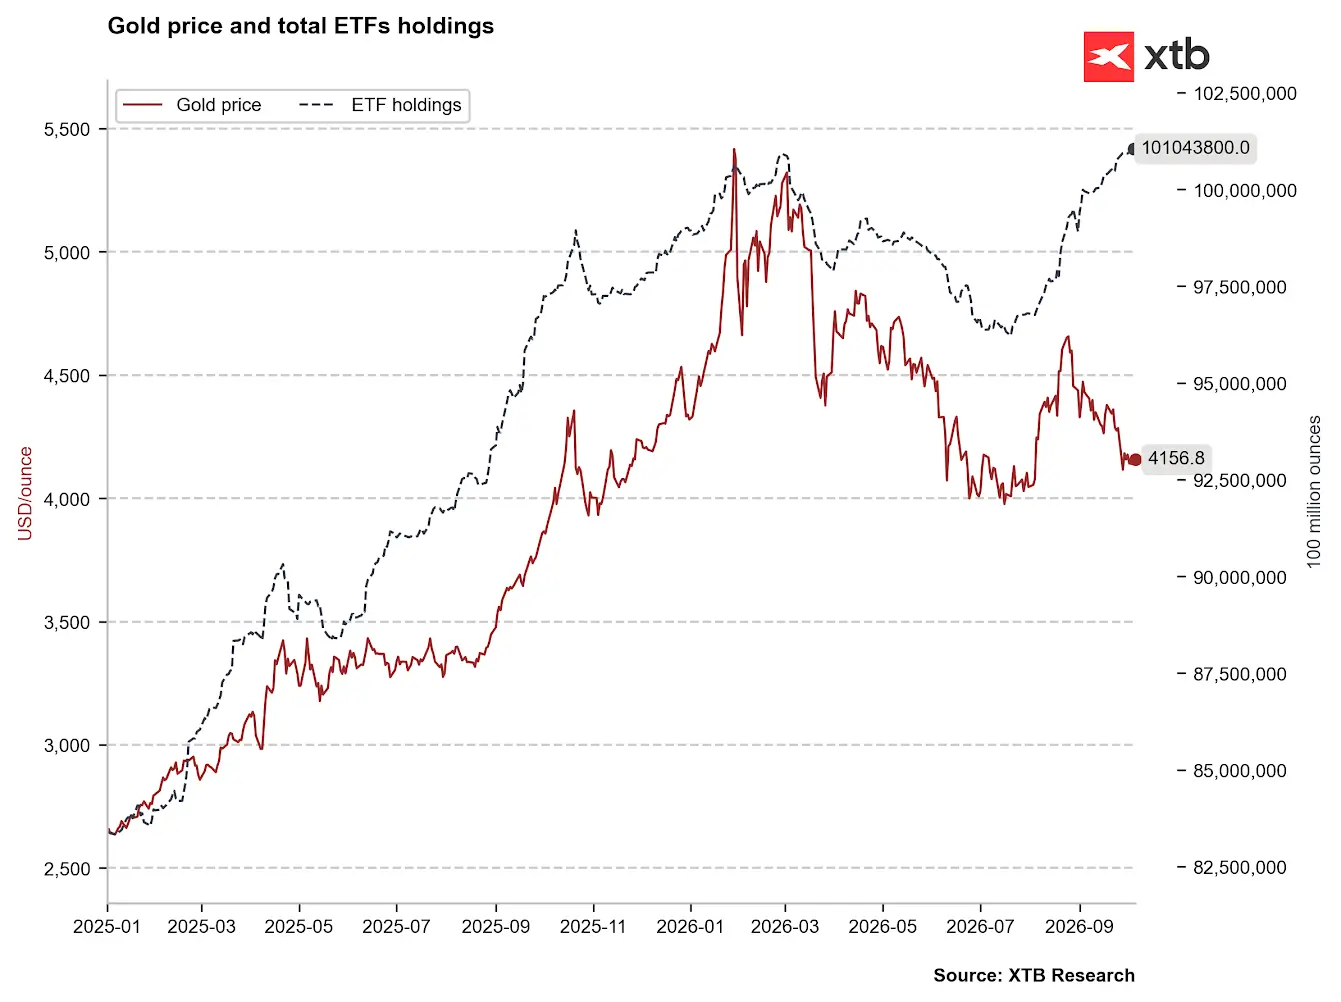
Gold price vs total ETF holdings
Total gold holdings in ETFs have risen significantly in recent months and now exceed 101 million ounces, reaching the highest level shown on the chart. Importantly, this increase in ETF exposure has taken place despite a sharp decline in the gold price from around $5,200–5,400 to roughly $4,157 per ounce. This divergence suggests that some investors are using the pullback to increase their exposure to gold rather than reducing positions alongside the price correction. If ETF inflows persist, they could become an important medium-term stabilizing factor for the market, even if pressure from high yields and interest rates remains elevated.
Source: XTB Research
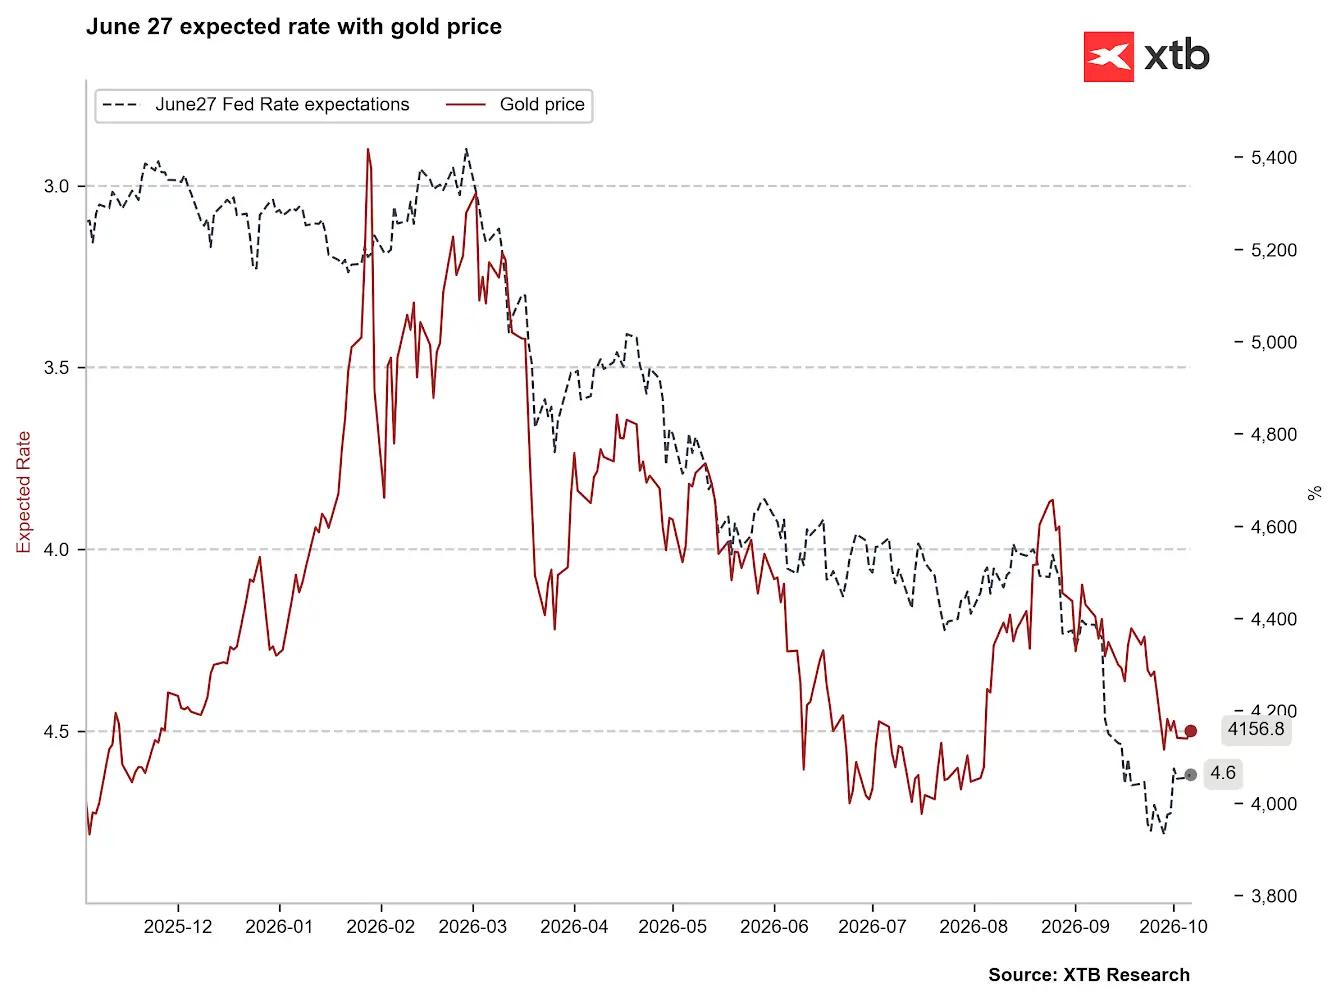
Expected Fed rate for June 2027 vs gold price
Expectations for the Fed funds rate in June 2027 have moved clearly higher, with the market now pricing a level of around 4.6%. At the same time, gold remains under pressure and is trading near $4,157 per ounce, well below this year’s highs. In recent months, the relationship has been relatively clear: higher expected interest rates have generally coincided with weaker gold prices, as higher rates increase the opportunity cost of holding a non-yielding asset. If the market continues to shift toward expectations of a more restrictive Fed policy stance, this could remain an important factor limiting gold’s upside potential.
Source: XTB Research


Large decline in crude inventories 🛢️📉


US Open: Wall Street in the Red 🚩 Nasdaq Falls 1% From Record Highs, Constellation Brands Back at March 2020 Level

Wheat Rebounds? 📈 Weak U.S. Planting, Russian Exports Down 75%

Bitcoin Hits a Wall. Will “Uptober” Bring a Crypto Correction?
The content of this report has been created by XTB S.A., with its registered office in Warsaw, at Prosta 67, 00-838 Warsaw, Poland, (KRS number 0000217580) and supervised by Polish Supervision Authority ( No. DDM-M-4021-57-1/2005). This material is a marketing communication within the meaning of Art. 24 (3) of Directive 2014/65/EU of the European Parliament and of the Council of 15 May 2014 on markets in financial instruments and amending Directive 2002/92/EC and Directive 2011/61/EU (MiFID II). Marketing communication is not an investment recommendation or information recommending or suggesting an investment strategy within the meaning of Regulation (EU) No 596/2014 of the European Parliament and of the Council of 16 April 2014 on market abuse (market abuse regulation) and repealing Directive 2003/6/EC of the European Parliament and of the Council and Commission Directives 2003/124/EC, 2003/125/EC and 2004/72/EC and Commission Delegated Regulation (EU) 2016/958 of 9 March 2016 supplementing Regulation (EU) No 596/2014 of the European Parliament and of the Council with regard to regulatory technical standards for the technical arrangements for objective presentation of investment recommendations or other information recommending or suggesting an investment strategy and for disclosure of particular interests or indications of conflicts of interest or any other advice, including in the area of investment advisory, within the meaning of the Trading in Financial Instruments Act of 29 July 2005 (i.e. Journal of Laws 2019, item 875, as amended). The marketing communication is prepared with the highest diligence, objectivity, presents the facts known to the author on the date of preparation and is devoid of any evaluation elements. The marketing communication is prepared without considering the client’s needs, his individual financial situation and does not present any investment strategy in any way. The marketing communication does not constitute an offer of sale, offering, subscription, invitation to purchase, advertisement or promotion of any financial instruments. XTB S.A. is not liable for any client’s actions or omissions, in particular for the acquisition or disposal of financial instruments, undertaken on the basis of the information contained in this marketing communication. In the event that the marketing communication contains any information about any results regarding the financial instruments indicated therein, these do not constitute any guarantee or forecast regarding the future results.